Italy Heat Pump Market (2025-2030)
The Italy Heat Pump Market was valued at $2321.1 Million in 2025 and projected to reach to $4572.9 Million by 2030, representing a compound annual growth rate of 14.5%. Italy's heat pump market is poised for substantial growth through 2030, driven by stringent EU environmental regulations and national renewable energy targets.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Italy Heat Pump Market Trends and Insights
- This growth trajectory reflects Italy's commitment to renewable energy adoption and decarbonization targets across residential and commercial sectors.
- Italy's strategic positioning within the European Union's Green Deal framework is accelerating heat pump deployment as a cornerstone technology for sustainable heating solutions. The Italian heat pump market is driven by favorable government incentives, including tax credits and subsidies that reduce installation costs for end-users.
- Italy's aging building stock and renovation mandates create substantial demand for efficient heating alternatives, positioning heat pumps as a critical component of Italy's energy transition strategy.
- Between 2025 and 2030, Italy is expected to see increased market penetration across both new construction and retrofit applications, supported by rising energy costs and climate commitments..
Key Market Statistics
- CAGR (2025-2030) 14.5% CAGR
- Market Size, 2025 ~USD 2321.1 Million
- Forecast, 2030 ~USD 4572.9 Million
- Country Italy
Italy Heat Pump Market Overview
Strong Market Valuation :
Italy's heat pump market is valued at USD 2,321.1 million in 2025, demonstrating significant investment in renewable heating solutions across the country's residential and commercial sectors.
Robust Growth Trajectory :
With a CAGR of 14.5% through 2030, Italy's market is expanding faster than the global average of 14.3%, driven by EU Green Deal compliance and national decarbonization mandates.
EU Green Deal Alignment :
Italy's strategic positioning within the European Union's Green Deal framework accelerates heat pump adoption, with regulatory incentives and subsidies supporting residential and commercial installations.
Forecast Growth Potential :
The market is projected to nearly double to USD 4,572.9 million by 2030, reflecting Italy's commitment to phasing out fossil fuel heating and achieving climate neutrality targets.
Italy Heat Pump Market Dynamics
- Government incentives, including tax credits and subsidies for residential retrofits, are accelerating adoption across both urban and rural areas.
- The commercial sector is increasingly investing in heat pump technology for building decarbonization, while residential applications remain the primary growth driver. The market's expansion is supported by improving technology efficiency, declining equipment costs, and growing consumer awareness of long-term energy savings.
- Italy's aging building stock presents significant retrofit opportunities, particularly in northern regions with higher heating demands.
- Strategic partnerships between manufacturers and installation networks are strengthening market penetration, positioning Italy as a key European heat pump market through the forecast period..
Market Ecosystem
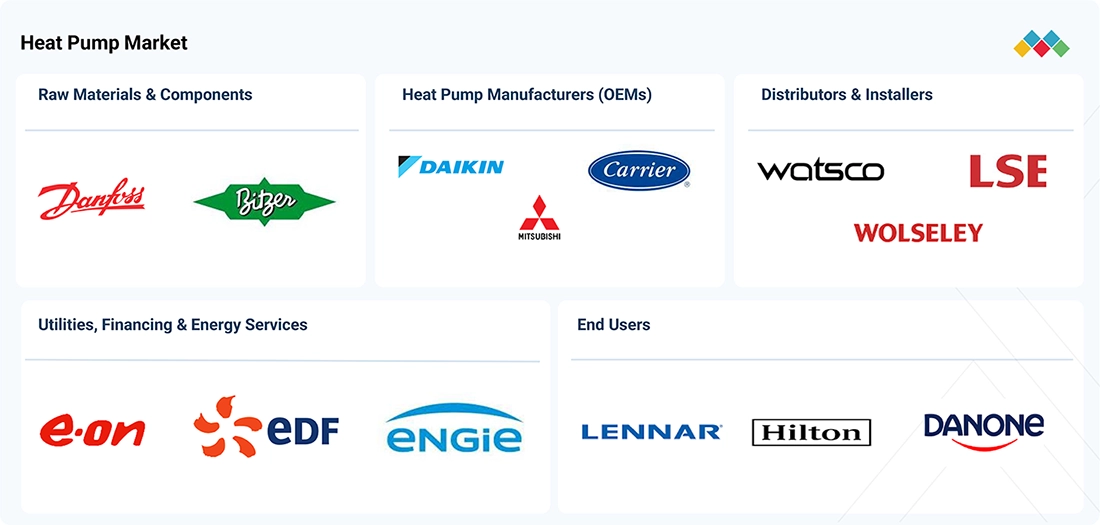
HEAT PUMP MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Carrier supplied a 2 MW high-temperature heat-pump system to a major bank estate in Glasgow, Scotland. The system combines five AquaSnap air-source heat pumps with four AquaForce water-source heat pumps to deliver 85°C hot water for district heating. | It enables high-temperature heating for an existing commercial estate, demonstrating heat pump applicability in retrofit and district heating environments. The system uses R-32 and R-1234ze low-GWP refrigerants, supporting the transition toward lower-emission heating technologies. |
 |
Mitsubishi Electric supplied Ecodan air-to-water heat pumps to 154 new homes in County Wicklow, Ireland, with each home equipped with a 6 kW system for space heating and domestic hot water. The company worked with the developer and installer on system design, heat-loss calculations, sizing, and commissioning. | It demonstrates Mitsubishi Electric's ability to integrate heat pumps at large residential-development scale, while standardized equipment, design support, and maintenance registration simplify deployment across multiple homes. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Industrial Equipment
- HVAC System
- Fiberglass
- Actuators
- Cartridge Filters
- Electrostatic Precipitators
- Siemens ag
- ABB India Limited
- GRUNDFOS GROUP
- SCHNEIDER ELECTRIC SE
- Emerson Electric Co.
Key Takeaways
- Italy's heat pump market will nearly double from USD 2,321.1M (2025) to USD 4,572.9M (2030), representing a 14.5% CAGR.
- Government incentives and EU Green Deal policies are primary catalysts driving heat pump adoption across Italy.
- Italy's building renovation wave and aging infrastructure create significant retrofit opportunities for heat pump installations.
- Rising energy costs and climate commitments position Italy as a high-growth market within the European heat pump sector.
Heat Pump Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | HEATING AND COOLING (Application) |
| Forecast Period | 2025-2030 |
| Growth Rate | CAGR of 14.3% from 2025 to 2030 |
| Largest Segment | HEATING (Application) |
| Market Size Base Year (Billions) | ~USD 83.33 (2025) |
| Revenue Forecast (Billions) | ~USD 162.56 (2030) |
| Segments Covered | Application, Heating, End User, Rated Capacity, Refrigerant, Technology, Type |
Italy Heat Pump Market Report Segmentation
7 segment dimensions are covered across the global market.
By Application
- District And Space Heating
- Heating
- Heating And Cooling
- Water Heating
By Heating
- District And Space Heating
- Water Heating
By End User
- Commercial
- Industrial
- Residential
By Rated Capacity
- 10-20 Kw
- 20-30 Kw
- Above 30 Kw
- Up To 10 Kw
By Refrigerant
- Other Refrigerants
- R290
- R407C
- R410A
- R717
- R744
By Technology
- Air-To-Air Heat Pumps
- Air-To-Water Heat Pumps
- Ground-Source (Geothermal) Heat Pumps
- Hybrid Heat Pumps
- Photovoltaic-Thermal (Pvt) Heat Pumps
- Water Source Heat Pumps
- Water-Source Heat Pumps
By Type
- Non-Reversible Heat Pumps
- Reversible Heat Pumps
ITALY: HEAT PUMP MARKET, BY END USER, 2025–2030
| Segment | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | CAGR (%) |
|---|---|---|---|---|---|---|---|
| COMMERCIAL | 487.2 | 531.3 | 589.6 | 668.2 | 776.1 | 927.6 | 13.7 |
| INDUSTRIAL | 166.2 | 180 | 198.3 | 223 | 256.9 | 304.4 | 12.9 |
| RESIDENTIAL | 1667.7 | 1836.9 | 2059.6 | 2358 | 2766.8 | 3340.9 | 14.9 |
| TOTAL | 2321.1 | 2548.2 | 2847.6 | 3249.3 | 3799.8 | 4572.9 | 14.5 |
Target Audience
- Heat Pump Manufacturers : Manufacturers need Italy-specific market data to assess market entry opportunities, competitive positioning, and localized demand patterns for product development and distribution strategies.
- HVAC Installation & Service Companies : Italian installers require detailed market insights to identify growth segments, understand regulatory requirements, and plan capacity expansion for residential and commercial projects.
- Energy & Utilities Companies : Utilities and energy providers need market intelligence to align heating infrastructure investments with Italy's decarbonization goals and anticipate demand shifts in their service territories.
- Government & Policy Makers : Italian policymakers and energy agencies require market data to evaluate incentive program effectiveness, forecast renewable heating adoption rates, and refine climate policy implementation.
- Investment & Financial Analysts : Investors and financial professionals need Italy-focused market forecasts to evaluate investment opportunities, assess portfolio companies, and identify emerging trends in the renewable heating sector.
Reasons to Buy this Report
- Market Size & Growth Data : Access precise valuation metrics for Italy's heat pump market with detailed CAGR analysis, enabling accurate financial forecasting and investment decision-making for market participants.
- Competitive Landscape Intelligence : Understand Italy-specific market dynamics, key players, and competitive positioning to identify growth opportunities and strategic partnerships within the Italian heat pump sector.
- Regulatory & Policy Insights : Gain comprehensive understanding of Italy's EU Green Deal obligations, government incentives, and decarbonization targets that directly influence market demand and investment priorities.
- Sector-Specific Segmentation : Analyze residential versus commercial market segments in Italy with tailored insights for targeting specific customer bases and optimizing product-market fit strategies.
- Strategic Planning Support : Leverage Italy-focused forecasts and market trends to develop informed expansion strategies, resource allocation plans, and long-term business objectives in the Italian energy market.
Frequently asked questions
What is the current size of Italy's heat pump market?
Italy's heat pump market was valued at USD 2,321.1 million in 2025 and is expected to grow to USD 4,572.9 million by 2030.
What is the projected growth rate for Italy's heat pump market?
Italy's heat pump market is projected to grow at a compound annual growth rate (CAGR) of 14.5% between 2025 and 2030.
What are the main drivers of heat pump adoption in Italy?
Key drivers include government tax credits and subsidies, EU Green Deal mandates, building renovation requirements, rising energy costs, and climate commitments.
Which sectors are driving demand for heat pumps in Italy?
Both residential and commercial sectors are driving demand, with particular growth in building retrofits and new construction applications across Italy.
How does Italy's heat pump market compare to other European countries?
Italy's 14.5% CAGR positions it as a high-growth market within Europe, driven by strong policy support and substantial renovation opportunities across the country.
RESEARCH METHODOLOGY
The research process for this technical, market-oriented, and commercial study of the heat pump market involved systematic collection, validation, and analysis of information related to heat pump technologies, heating applications, refrigerant developments, energy-efficiency requirements, and electrification initiatives. Extensive secondary research was conducted using annual reports, investor presentations, technical papers, regulatory publications, industry databases, company websites, and financial reports to identify key market participants, technology trends, market developments, and competitive strategies. The findings were further validated through primary interviews with executives from heat pump manufacturers, HVAC system providers, distributors, installers, energy companies, and industry experts to assess market estimates, technology adoption, customer requirements, and competitive positioning. Key market players and their market positions were established through a combination of secondary research and primary validation involving senior executives, business development managers, product specialists, and technical experts across the heat pump ecosystem.
Secondary Research
In the secondary research process, various secondary sources were referred to for identifying and collecting information relevant to the study. Secondary sources included annual reports, investor presentations, press releases, company websites, technical papers, industry journals, regulatory publications, and recognized market databases. Publications and datasets from organizations such as the International Energy Agency (IEA), European Heat Pump Association (EHPA), U.S. Department of Energy (DOE), National Renewable Energy Laboratory (NREL), U.S. Energy Information Administration (EIA), European Commission, and International Energy Agency Heat Pump Monitor were reviewed to understand heat pump deployment, energy-efficiency trends, policy developments, refrigerant transition, and technology adoption. Secondary research was primarily conducted to obtain information on the heat pump value chain, key market participants, technology developments, refrigerant trends, product portfolios, market drivers and restraints, regional adoption patterns, application trends, end-user demand, and recent industry developments
Primary Research
During the primary research phase, manufacturers, distributors, installers, HVAC contractors, building owners, and industry experts were interviewed to obtain qualitative and quantitative insights on the heat pump market. Interviews were conducted to validate market estimates, technology adoption, pricing, installation trends, regional demand, competitive positioning, and customer buying criteria. A combination of top-down and bottom-up approaches, supported by data triangulation, was used to estimate and forecast the market across all segments and subsegments. Primary interviews also helped assess adoption drivers and barriers, replacement demand, retrofit requirements, installer availability, refrigerant transition, and emerging technologies. The findings were further validated against company disclosures, government statistics, and industry sources such as the IEA and EHPA to refine market estimates, segment shares, regional forecasts, and competitive assessments.
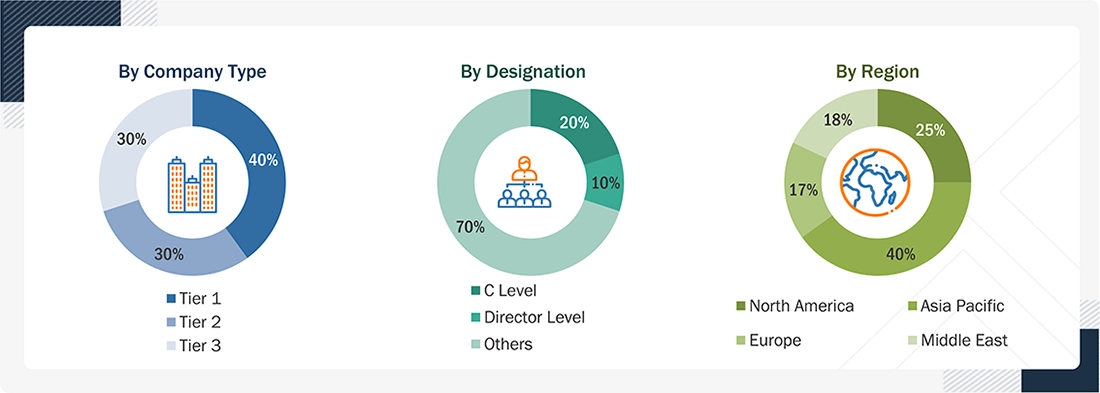
Note: Others include sales managers, engineers, and regional managers.
Tier 1 Company Revenue > USD 5 billion, Tier 2 Company Revenue between USD 1 and USD 5 billion, and Tier 3 Company Revenue < USD 1 billion.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
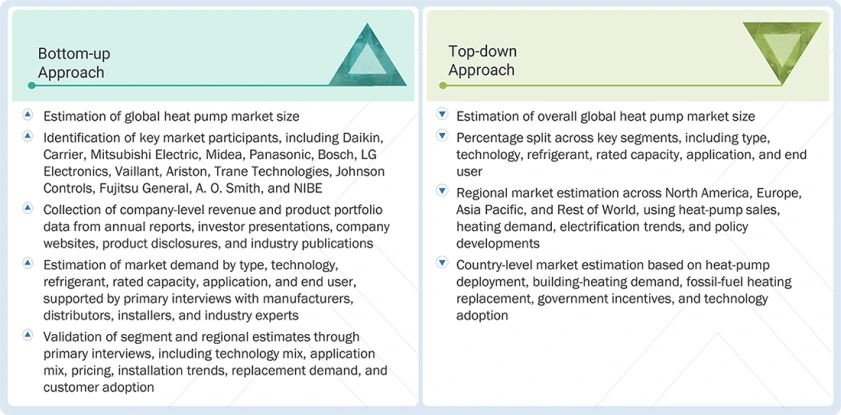
Bottom-up Approach
- Estimating the heat pump market size across type, technology, refrigerant, rated capacity, application, and end user segments by analyzing revenue generated from heat pump systems and consolidating segment-level estimates to derive the overall market size.
- Mapping leading market participants, including DAIKIN INDUSTRIES, Ltd., Carrier, Mitsubishi Electric Corporation, Midea Group, Panasonic Holdings Corporation, Bosch Thermotechnology Corp, LG Electronics Inc., Vaillant Group International GmbH, Ariston Holding N.V., Trane Technologies plc, Johnson Controls, Fujitsu, A. O. Smith Corporation, NIBE Industrier AB, and other regional and specialized manufacturers.
- Collecting segment-wise revenue and product portfolio information from annual reports, investor presentations, company websites, product catalogs, press releases, regulatory filings, and other publicly available disclosures.
- Estimating demand across major applications, including heating and heating & cooling, with further assessment of water heating and district & space heating, based on heat-pump installations, product sales, replacement demand, construction activity, and electrification trends.
- Estimating market demand across major technologies, including air-to-air, air-to-water, water-source, ground-source, hybrid, and PVT heat pumps, using manufacturer product portfolios, technology deployment data, and regional adoption trends.
Incorporating qualitative factors, including electrification policies, fossil-fuel heating restrictions, energy prices, low-GWP refrigerant regulations, energy-efficiency standards, retrofit activity, technology advancements, and installer availability, into the market forecasting model.
Top-down Approach
- Estimating the overall global heat pump market by analyzing global heating equipment demand, building sector electrification, heat pump deployment, energy-efficiency investments, and replacement of conventional fossil fuel heating systems.
- Allocating the market across type (Reversible and Non-reversible), technology (Air-to-Air, Air-to-Water, Water-Source, Ground-Source, Hybrid, and PVT), refrigerant, rated capacity, application, and end user (Residential, Commercial, and Industrial) using regional adoption patterns, technology penetration, manufacturer portfolios, and industry data.
- Distributing market estimates across North America, Europe, Asia Pacific, and Rest of the World based on regional heat-pump sales, installed base, building-heating demand, policy support, and technology adoption.
- Validating the final market estimates through primary interviews with manufacturers and channel participants to validate regional sales trends, installer activity, pricing, technology preferences, and replacement demand, followed by data triangulation to ensure consistency and accuracy.
Heat Pump Market : Top-Down and Bottom-Up Approach
Data Triangulation
The process of determining the overall market size involved the methodologies described earlier, followed by segmenting the market into multiple segments and subsegments. To finalize the comprehensive market analysis and obtain precise statistics for each market segment and subsegment, data triangulation and market breakdown procedures were applied, wherever appropriate. Data triangulation was accomplished by examining factors and trends from both the demand and supply sides of the heat pump ecosystem, including heat pump sales and installations, technology adoption, manufacturer revenues and product portfolios, heating-system replacement demand, policy developments, refrigerant regulations, energy prices, and regional market dynamics.
Market Definition
A heat pump is an electrically powered device that transfers heat from one location to another. It operates using a refrigerant that circulates through four key components - an evaporator, condenser, compressor, and expansion device - to enable heat exchange. This process allows the heat pump to provide heating in winter and cooling in summer. Rather than generating heat, a heat pump moves it, making it a highly energy-efficient alternative to traditional furnaces and air conditioning systems, suitable for use in all climate zones.
The heat pump market encompasses the total revenue generated globally from the sale of various heat pump technologies, including air-to-air, air-to-water, water-source, ground-source (geothermal), hybrid, and photovoltaic-thermal systems. These heat pumps are available in multiple rated capacities, such as up to 10 kW, 10–20 kW, 20–30 kW, and above 30 kW, to suit diverse application needs. The primary end-user segments for these systems are the residential, commercial, and industrial sectors.
Key Stakeholders
- Heat pump manufacturers and OEMs
- Heat pump component and compressor manufacturers
- HVAC equipment manufacturers and system integrators
- Installation, maintenance, and after-sales service providers
- Government agencies and regulatory authorities
- Research institutions and industry associations
- Utility companies and energy service providers (ESCOs)
- Technology standards organizations, industry forums, alliances, and trade associations
- Institutional investors and private equity firms
- Building developers, EPC contractors, and infrastructure companies
Report Objectives
- To define, describe, segment, and forecast the heat pump market by technology, type, refrigerant, rated capacity, end user, and application, in terms of value
- To forecast the market sizes for six major regions, namely North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa, along with their key countries, in terms of value
- To forecast the heat pump market by technology and region, in terms of volume
- To provide detailed information regarding key drivers, restraints, opportunities, and challenges influencing the growth of the heat pump market
- To provide the supply chain analysis, trends/disruptions impacting customer business, ecosystem analysis, regulatory landscape, patent analysis, case study analysis, technology analysis, key conferences & events, the impact of AI/Gen AI, macroeconomic outlook, pricing analysis, Porter’s five forces analysis, and regulatory analysis, the impact of 2025 US tariff on the market
- To analyze opportunities for stakeholders in the heat pump market and draw a competitive landscape of the market
- To benchmark market players using the company evaluation matrix, which analyzes market players on broad categories of business and product strategies adopted by them
- To compare key market players for the market share, product specifications, and applications
- To strategically profile key players and comprehensively analyze their market ranking and core competencies.
- To analyze competitive developments, such as contracts, agreements, partnerships, and expansions in the heat pump market
Available customizations:
With the given market data, MarketsandMarkets offers customizations based on the company’s specific needs. The following customization options are available for the report:
Product Analysis
- Product Matrix, which provides a detailed comparison of the product portfolio of each company
Company Information
-
Detailed analyses and profiling of additional market players (up to 5)
Get the Full Heat Pump Market Report
Full forecast, segment splits, and company analysis for all Heat Pump Market.
- China Heat Pump Market
- India Heat Pump Market
- Japan Heat Pump Market
- South Korea Heat Pump Market
- Australia Heat Pump Market
- France Heat Pump Market
- Germany Heat Pump Market
- UK Heat Pump Market
- Spain Heat Pump Market
- Canada Heat Pump Market
- US Heat Pump Market
- Saudi Arabia Heat Pump Market
- UAE Heat Pump Market
- South Africa Heat Pump Market
- Brazil Heat Pump Market
- Mexico Heat Pump Market
- Rest Of Europe Heat Pump Market
- Rest Of Asia Pacific Heat Pump Market
- Rest Of Latin America Heat Pump Market
- GCC Countries Heat Pump Market
- Rest Of The GCC Countries Heat Pump Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report