Australia Immunoassay Market (2025-2030)
The Australia Immunoassay Market was valued at $451.73 Million in 2025 and projected to reach to $617.49 Million by 2030, representing a compound annual growth rate of 6.5%. Australia's immunoassay market is positioned for sustained growth driven by an aging population requiring increased diagnostic testing, technological advancements in assay platforms, and rising healthcare expenditure.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Australia Immunoassay Market Trends and Insights
- This growth trajectory reflects Australia's advancing healthcare infrastructure and increasing demand for diagnostic testing across clinical laboratories and point-of-care settings.
- Australia's immunoassay sector benefits from strong regulatory frameworks, high healthcare spending, and a growing prevalence of chronic diseases requiring routine immunological testing. The Australian immunoassay market is driven by technological innovation in assay platforms, rising adoption of automated diagnostic systems, and expanding applications in infectious disease detection and immunotherapy monitoring.
- Australia's aging population and emphasis on preventive healthcare further accelerate market penetration.
- Between 2025 and 2030, Australia is expected to see increased investment in laboratory automation and enhanced diagnostic capabilities, positioning the country as a key growth market within the Asia Pacific region..
Key Market Statistics
- CAGR (2025-2030) 6.5% CAGR
- Market Size, 2025 ~USD 451.73 Million
- Forecast, 2030 ~USD 617.49 Million
- Country Australia
Australia Immunoassay Market Overview
Market Valuation Growth :
Australia's immunoassay market is valued at USD 451.73 million in 2025, with a projected CAGR of 6.5% through 2030, reaching USD 617.49 million. This outpaces the global CAGR of 6.1%, indicating Australia's accelerating adoption of immunoassay technologies.
Healthcare Infrastructure Advancement :
Australia's robust healthcare system and well-established diagnostic laboratory network drive consistent demand for immunoassay solutions. Investment in modern pathology facilities and point-of-care testing capabilities continues to expand across urban and regional centers.
Regulatory Framework Strength :
Australia's stringent regulatory environment through the TGA (Therapeutic Goods Administration) ensures high-quality immunoassay products and builds confidence among healthcare providers. This regulatory rigor supports market credibility and attracts premium diagnostic solutions.
Point-of-Care Testing Expansion :
Growing adoption of rapid immunoassay testing in primary care settings, aged care facilities, and emergency departments reflects Australia's shift toward decentralized diagnostics. This trend supports market diversification beyond traditional laboratory-based testing.
Australia Immunoassay Market Dynamics
- The market benefits from strong pathology accreditation standards and increasing integration of automation in diagnostic laboratories.
- Point-of-care immunoassay adoption is accelerating in response to demand for faster turnaround times and improved patient outcomes. Looking ahead to 2030, Australia's immunoassay sector will likely see consolidation among diagnostic providers, expansion of multiplex testing capabilities, and greater emphasis on personalized medicine applications.
- Investment in digital pathology and laboratory information systems will enhance market growth, while regulatory harmonization with international standards will facilitate access to innovative immunoassay technologies..
Market Ecosystem
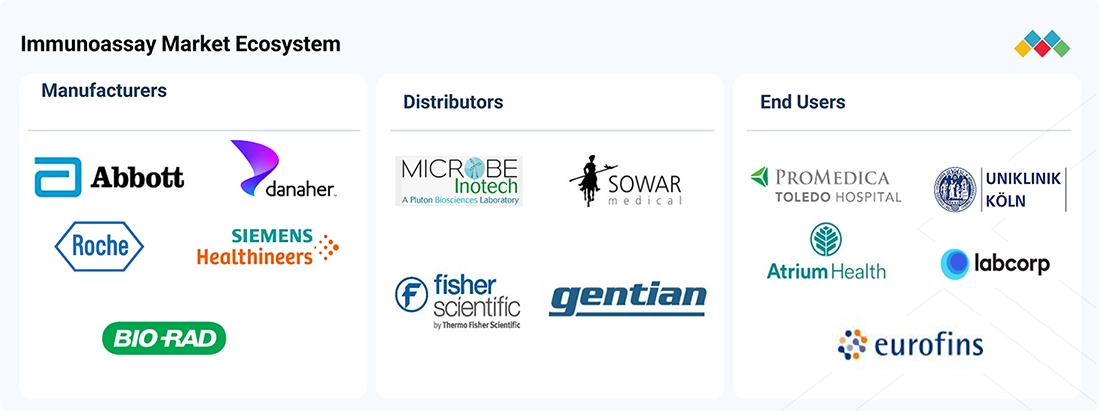
IMMUNOASSAY MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Provides automated immunoassay testing through the Alinity i and ARCHITECT systems for clinical laboratory and blood screening applications. | Improves testing throughput within a compact footprint | Supports broad testing menus | Provides greater walk-away time through automated workflows | Supports consistent and reliable results. |
 |
Provides automated immunoassay testing through cobas e analyzers using electrochemiluminescence technology across infectious disease, cardiac, endocrine, fertility, and oncology applications. | Provides high sensitivity and reproducibility through ECL technology | Supports high-throughput testing | Enables continuous reagent loading during operation | Supports carryover-free sample processing. |
 |
Provides immunoassay testing through Atellica IM, ADVIA Centaur, and IMMULITE systems across infectious disease, cardiac, endocrine, and reproductive health testing. | Supports high immunoassay testing throughput | Enables rapid turnaround for key assays | Provides automated QC and remote monitoring | Supports broad assay menus and scalable laboratory configurations. |
 |
Provides automated immunoassay testing through DxI and Access analyzers for clinical laboratories with varying testing volumes. | Provides high productivity per laboratory footprint | Reduces routine maintenance requirements | Supports remote real-time system monitoring | Enables expanded assay processing and laboratory productivity. |
 |
Provides Bio-Plex multiplex immunoassays and ELISA-based solutions for biomarker, cytokine, protein, and antibody analysis across research and clinical applications. | Enables simultaneous measurement of multiple analytes | Reduces sample volume requirements | Supports high-throughput biomarker analysis | Provides automated data analysis and reproducible assay performance. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
In Vitro Diagnostics
- Polymerase Chain Reaction (PCR)
- Enzyme-Linked Immunosorbent Assay (ELISA)
- Dna Microarrays
- Assay Kits
- Microarrays
- ROCHE HOLDINGS AG
- Thermo Fisher Scientific Inc.
- Danaher Corporation
- Abbott Laboratories
- Biomerieux s.a.
Medical Devices
- Polymerase Chain Reaction (PCR)
- Magnetic Resonance Imaging (MRI)
- Disposable Autoinjectors
- Pulse Oximeters
- Blood Pressure Monitors
- Medtronic plc
- Abbott Laboratories
- Stryker Corporation
- Becton, Dickinson and Company
- JOHNSON & JOHNSON
Key Takeaways
- Australia's immunoassay market is valued at USD 451.73 million in 2025 and is forecast to grow to USD 617.49 million by 2030, representing a 6.5% CAGR.
- Australia's advanced healthcare infrastructure and high diagnostic spending support robust demand for immunoassay technologies across clinical and point-of-care settings.
- Technological innovation in automated assay platforms and expanding applications in infectious disease and immunotherapy monitoring are key growth drivers in Australia.
- Australia's aging population and preventive healthcare focus position the country as a high-growth market within the Asia Pacific immunoassay sector.
Immunoassay Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | CLIA (Technology) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 6.1% from 2025 to 2030 |
| Largest Segment | REAGENTS & KITS (Product) |
| Market Size Base Year (Billions) | ~USD 35.48 (2025) |
| Revenue Forecast (Billions) | ~USD 47.7 (2030) |
| Segments Covered | Product, Type, Purchase Mode, Technology, Specimen, Application |
Australia Immunoassay Market Report Segmentation
6 segment dimensions are covered across the global market.
By Product
- Analyzers
- Reagents & Kits
By Type
- Clia Reagents & Kits
- Closed-Ended Systems
- Elisa Reagents & Kits
- Elispot Reagents & Kits
- Ifa Reagents & Kits
- Open-Ended Systems
- Other Reagents & Kits
- Rapid Test Reagents & Kits
- Western Blot Reagents & Kits
By Purchase Mode
- Outright Purchase
- Rental Purchase
By Technology
- Clia
- Elisa
- Elispot
- Ifa
- Other Technologies
- Rapid Tests
- Western Blotting
By Specimen
- Blood
- Other Specimens
- Saliva
- Urine
By Application
- Allergy Diagnostics
- Autoimmune Disorders
- Blood Screening
- Bone & Mineral Disorders
- Cardiology
- Drug Monitoring & Testing
- Endocrinology
- Infectious Diseases
- Newborn Screening
- Oncology
- Other Applications
AUSTRALIA: IMMUNOASSAY MARKET, BY END USER, 2023–2030
| Segment | 2023 | 2024 | 2025 | 2026 | 2028 | 2029 | 2030 | CAGR (%) |
|---|---|---|---|---|---|---|---|---|
| BLOOD BANKS | 13.34 | 13.51 | 13.82 | 14.29 | 15.69 | 16.66 | 17.83 | 5.2 |
| CLINICAL LABORATORIES | 142.11 | 145.95 | 151.36 | 158.81 | 179.36 | 193.04 | 209.53 | 6.7 |
| HOME CARE SETTINGS | 17.75 | 18.06 | 18.57 | 19.3 | 21.41 | 22.84 | 24.57 | 5.8 |
| HOSPITALS & CLINICS | 334.78 | 342.12 | 353.02 | 368.52 | 412 | 441.19 | 476.41 | 6.2 |
| TOTAL | 507.98 | 519.64 | 536.77 | 560.92 | 628.46 | 673.73 | 728.34 | 6.3 |
Target Audience
- Diagnostic Equipment Manufacturers : Manufacturers need Australia-specific market data to assess market size, growth potential, and competitive dynamics before launching or expanding immunoassay product lines in the region.
- In Vitro Diagnostics (IVD) Companies : IVD companies require detailed Australian market insights to optimize product portfolios, identify unmet diagnostic needs, and develop targeted commercialization strategies for pathology and point-of-care segments.
- Pathology Service Providers : Pathology networks and independent laboratories need market intelligence to guide capital investment decisions, technology upgrades, and service expansion planning aligned with market growth trends.
- Healthcare Investors & Private Equity : Investment firms evaluating opportunities in Australia's diagnostic sector require market sizing, growth forecasts, and competitive analysis to support due diligence and portfolio company valuations.
- Healthcare Policy & Government Bodies : Australian health authorities and policy makers need market data to inform healthcare infrastructure planning, diagnostic testing guidelines, and reimbursement policy development for immunoassay services.
Key Companies in the Australia Immunoassay Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| PATHEON INC | Netherlands | Private Company | Drug Product Services (oral, sterile, packaging, lifecycle),Pharmaceutical Development Services (preclinical to clinical),Drug Substance Services (small-molecule and biologics APIs), |
| ALERE INC | United States | Private Company | Infectious disease diagnostics (rapid and serology, including ELISA and automated systems),Cardiometabolic and critical care point-of-care (blood gas, lipids, glucose, D-dimer, troponin, diabetes),Toxicology and workplace drug testing (devices, reagents, lab services, alcohol tests), |
| FLUOR CORPORATION | United States | Public Company | Energy Solutions (oil, gas, chemicals, LNG, power, energy transition),Urban Solutions (advanced technologies, life sciences, mining and metals, infrastructure, staffing, maintenance),Mission Solutions (government, nuclear remediation, nuclear security, logistics, mission-critical O&M), |
| CEPHEID INC. | United States | Private Company | Infectious disease & healthcare-associated infection assays (Xpert on GeneXpert),Virology assays (including emergency use authorization tests),Oncology and genetics assays, |
| IMMUCOR, INC. | United States | Private Company | Transfusion (serology instruments and reagents, including NEO, Echo, Capture),Transplant & Molecular (HLA, HPA assays, Array Imaging System, BASIS, platelet-focused products),Other / Services and Ancillary Products, |
| UNILABS | Switzerland | Private Company | Routine & Specialty Laboratory Testing,Medical Imaging,Pathology & Centres of Excellence (IVF, Fertility, Pregnancy, Targeted Diagnostics), |
| EIKEN CHEMICAL CO., LTD. | Japan | Public Company | Fecal immunochemical test (FIT) reagents and analyzers,Microbiological reagents and food/environmental microbiology,Urinalysis test strips and analyzers, |
| ABBOTT | United States | Public Company | Diagnostic Products,Medical Devices,Nutritional Products, |
| SIEMENS HEALTHINEERS AG | Germany | Public Company | Imaging,Diagnostics,Varian (Oncology), |
| DANAHER | United States | Public Company | Biotechnology (bioprocessing and related solutions),Life Sciences (analytical instruments, genomics, and lab automation),Diagnostics (clinical instruments and consumables), |
| THERMO FISHER SCIENTIFIC INC. | United States | Public Company | Life Sciences Solutions,Analytical Instruments,Specialty Diagnostics, |
| REVVITY | United States | Public Company | Diagnostics instruments and systems,Diagnostics reagents, assays, and consumables,Life science reagents and genomic workflow tools, |
| DIASORIN S.P.A. | Italy | Public Company | Immunodiagnostics – Infectious and Gastrointestinal Diseases,Immunodiagnostics – Endocrinology, Metabolic Disorders, Tumor Markers, Oncology,Molecular Diagnostics – Simplexa and Congenital CMV, |
| BIO-RAD LABORATORIES, INC. | United States | Public Company | Clinical Diagnostics,Life Science Research Tools,Other / Informatics & Software, |
| QUIDELORTHO CORPORATION | United States | Public Company | Labs (clinical chemistry and immunoassay),Transfusion Medicine,Point of Care, |
| BIOMÉRIEUX | France | Public Company | Clinical microbiology & AST (VITEK, CHROMID, ETEST, culture media, BACT/ALERT),Syndromic and molecular diagnostics (BIOFIRE, SPOTFIRE, ARGENE, EMAG/NUCLISENS),Immunoassays & biomarkers (VIDAS, Hybiome CLIA), |
| QIAGEN | Netherlands | Public Company | Sample technology consumables and instruments,Molecular diagnostics assays (TB, immune response, oncology, sexual and reproductive health),Research PCR and enzymes (qPCR, digital PCR, RT-PCR, configured solutions), |
| SYSMEX CORPORATION | Japan | Public Company | Hematology analyzers & reagents,Coagulation diagnostics,Urinalysis, blood gas, electrolyte, |
| AGILENT TECHNOLOGIES, INC. | United States | Public Company | Life Sciences and Diagnostics Markets,Agilent CrossLab,Applied Markets, |
| SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD. | China | Public Company | Patient monitoring and life support (monitoring, ventilators, defibrillation, AED, anesthesia),Ultrasound and medical imaging (ultrasound, radiology, endoscope camera system),In-vitro diagnostics (CLIA, chemistry, hematology, laboratory diagnostics), |
PATHEON INC
Patheon Inc. is a Netherlands-based pharmaceutical manufacturing company with 9,100 employees. Operating as a private company, it provides contract development and manufacturing services to the pharmaceutical industry.
ALERE INC
Alere Inc. is a United States-based diagnostics company founded in 1981 with 9,700 employees. Operating as a private company, it specializes in rapid diagnostic testing solutions for healthcare markets.
FLUOR CORPORATION
Fluor Corporation is a United States-based engineering and construction company founded in 1912 with 22,995 employees. As a public company, it provides design, engineering, procurement, and construction services across multiple industries.
CEPHEID INC.
Cepheid Inc. is a United States-based molecular diagnostics company founded in 1996 with 1,700 employees. Operating as a private company, it develops and manufactures automated molecular testing systems.
IMMUCOR, INC.
Immucor, Inc. is a United States-based immunohematology company founded in 1982 with 1,125 employees. As a private company, it specializes in blood bank and transfusion medicine diagnostic solutions.
UNILABS
Unilabs is a Switzerland-based clinical laboratory services company founded in 1987 with 1,897 employees. As a private company, it operates diagnostic laboratories across multiple European countries.
EIKEN CHEMICAL CO., LTD.
Eiken Chemical Co., Ltd. is a Japan-based diagnostics and pharmaceutical company founded in 1939 with 696 employees. As a public company, it manufactures in vitro diagnostic reagents and pharmaceutical products.
ABBOTT
Abbott is a United States-based healthcare company founded in 1888 with 115,000 employees. As a public company, it develops and manufactures diagnostics, medical devices, pharmaceuticals, and nutritional products.
SIEMENS HEALTHINEERS AG
Siemens Healthineers AG is a Germany-based medical technology company founded in 1896 with 72,369 employees. As a public company, it manufactures and distributes diagnostic imaging, laboratory diagnostics, and point-of-care testing systems.
DANAHER
Danaher is a United States-based conglomerate founded in 1969 with 59,000 employees. As a public company, it operates across multiple sectors including life sciences, diagnostics, and environmental solutions.
THERMO FISHER SCIENTIFIC INC.
Thermo Fisher Scientific Inc. is a United States-based life sciences company founded in 1956 with 125,000 employees. As a public company, it provides laboratory equipment, reagents, and analytical instruments globally.
REVVITY
Revvity is a United States-based life sciences and diagnostics company founded in 1937 with 11,000 employees. As a public company, it manufactures and distributes analytical instruments and reagents for research and diagnostics.
DIASORIN S.P.A.
DiaSorin S.p.A. is an Italy-based diagnostics company founded in 1968 with 3,242 employees. As a public company, it develops and manufactures in vitro diagnostic products for clinical laboratories.
BIO-RAD LABORATORIES, INC.
Bio-Rad Laboratories, Inc. is a United States-based life sciences company founded in 1952 with 7,450 employees. As a public company, it manufactures and distributes reagents, instruments, and quality control products for clinical and research laboratories.
QUIDELORTHO CORPORATION
QuidelOrtho Corporation is a United States-based diagnostics company founded in 1979 with 6,500 employees. As a public company, it develops and manufactures rapid diagnostic tests and laboratory instruments.
BIOMÉRIEUX
bioMérieux is a France-based diagnostics company founded in 1963 with 14,894 employees. As a public company, it specializes in in vitro diagnostics for infectious diseases, industrial microbiology, and clinical diagnostics.
QIAGEN
QIAGEN is a Netherlands-based molecular diagnostics company founded in 1984 with 5,500 employees. As a public company, it develops and manufactures sample preparation and molecular testing solutions.
SYSMEX CORPORATION
Sysmex Corporation is a Japan-based diagnostics company founded in 1968 with 10,861 employees. As a public company, it manufactures and distributes hematology, hemostasis, and clinical chemistry analyzers.
AGILENT TECHNOLOGIES, INC.
Agilent Technologies, Inc. is a United States-based life sciences and diagnostics company founded in 1999 with 18,000 employees. As a public company, it provides analytical instruments, software, and services for research and diagnostics.
SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.
Shenzhen Mindray Bio-Medical Electronics Co., Ltd. is a China-based medical device company founded in 1991 with 21,288 employees. As a public company, it manufactures and distributes diagnostic imaging, patient monitoring, and laboratory instruments globally.
Reasons to Buy this Report
- Market-Specific Sizing & Forecasts : Access precise valuation data for Australia's immunoassay market with country-specific CAGR (6.5%) and detailed projections through 2030, enabling accurate business planning and investment decisions tailored to the Australian market.
- Competitive Landscape Intelligence : Understand Australia's diagnostic provider ecosystem, including major pathology networks, laboratory consolidation trends, and competitive positioning of immunoassay manufacturers operating in the region.
- Regulatory & Compliance Insights : Gain comprehensive knowledge of TGA requirements, accreditation standards, and regulatory pathways specific to Australia, ensuring compliant market entry and product registration strategies.
- Growth Opportunity Identification : Identify high-potential segments within Australia's market including point-of-care testing expansion, aged care diagnostics, and emerging applications in personalized medicine and chronic disease management.
- Strategic Market Entry Planning : Develop informed go-to-market strategies with localized insights on healthcare infrastructure, reimbursement models, key opinion leaders, and distribution channels specific to Australia's diagnostic sector.
Frequently asked questions
What is the current size of Australia's immunoassay market?
Australia's immunoassay market is valued at USD 451.73 million in 2025 and is expected to grow at a 6.5% CAGR through 2030.
What is the projected market size for Australia's immunoassay sector by 2030?
Australia's immunoassay market is projected to reach USD 617.49 million by 2030, driven by technological advancement and increased diagnostic demand.
What factors are driving growth in Australia's immunoassay market?
Key drivers include Australia's aging population, advanced healthcare infrastructure, rising chronic disease prevalence, automation adoption, and preventive healthcare emphasis.
How does Australia's immunoassay market compare to the Asia Pacific region?
Australia represents a significant high-growth market within Asia Pacific, supported by strong regulatory frameworks, high healthcare spending, and technological innovation capabilities.
What applications are expanding in Australia's immunoassay market?
Expanding applications in Australia include infectious disease detection, immunotherapy monitoring, chronic disease management, and point-of-care diagnostic testing.
RESEARCH METHODOLOGY
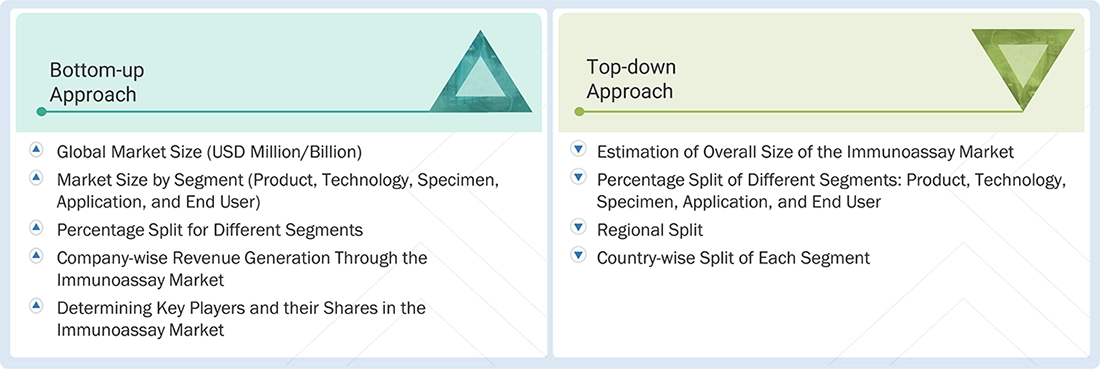
This study analyzes key market dynamics, including drivers, opportunities, restraints, and challenges, as well as major players’ strategies. It also monitors developments among leading players, including acquisitions, product launches, expansions, agreements, and partnerships. Additionally, the study examines the immunoassay market’s competitive landscape by evaluating market participants against criteria within the overarching categories of business and product strategy. To estimate market size, the study employed both top-down and bottom-up approaches. The market breakdown and data triangulation methods were used to assess segment and subsegment sizes.
The four steps involved in estimating the market size are as follows:
Secondary Research
In the secondary research process, various secondary sources such as annual reports, press releases, and investor presentations of companies; white papers; certified publications; articles by recognized authors; gold- and silver-standard websites; regulatory bodies; and databases (such as D&B Hoovers, Bloomberg Business, and Factiva) were referred to in order to identify and collect information for this study.
Primary Research
In the primary research process, we interviewed various sources from the supply and demand sides to obtain qualitative and quantitative information for this report. Primary sources were industry experts from core and related industries, as well as preferred suppliers, manufacturers, distributors, technology developers, researchers, and organizations across all segments of this industry’s value chain. We conducted in-depth interviews with various primary respondents, including key industry participants, subject-matter experts, C-level executives of key market players, and industry consultants, to obtain and verify critical qualitative and quantitative information and assess prospects.
The following is a breakdown of the primary respondents:
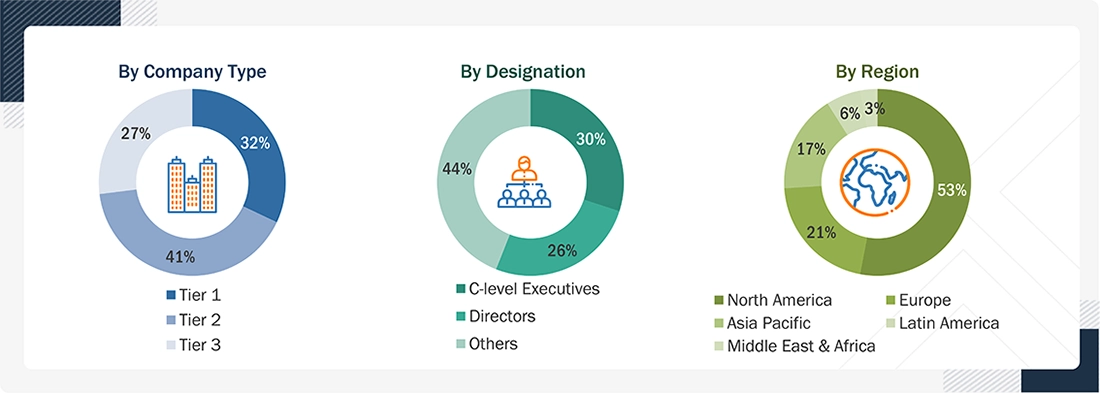
Note 1: C-level executives include Chief Executive Officers (CEOs), Chief Financial Officers (CFOs), Chief Operating Officers (COOs), and Vice Presidents (VPs).
Note 2: Other designations include sales managers, marketing managers, business development managers, product managers, distributors, and suppliers.
Note 3: Companies are classified into tiers based on their total revenue as of 2025. The tiers are as follows: Tier 1 = >USD 10 billion, Tier 2 = USD 1 billion to USD 10 billion, and Tier 3 = <USD 1 billion.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
For global market value, we calculated annual revenue figures using revenue mapping for major product manufacturers and OEMs active in the global immunoassay market. We identified all major product manufacturers at the global and/or country/regional level. We mapped revenue for the respective business segments/subsegments of the major players. Additionally, the global market was split into various segments and subsegments:
- List of major players in the immunoassay market by region or country
- Product mapping of various immunoassay manufacturers at the regional and/or country level
- Mapping of annual revenue generated by listed major players from immunoassay products (or the nearest reported business unit/product category)
- Extrapolation of the revenue mapping of the listed major players to derive the global market size of the respective business segments, in terms of value
- Summation of revenue of all companies to arrive at the global immunoassay market size
The data above was consolidated, supplemented with detailed inputs and analysis from MarketsandMarkets, and presented in this report.
Immunoassay Market: Top-Down and Bottom-Up Approach
Data Triangulation
After determining the overall market size using the market size estimation processes, we split the market into several segments and subsegments. To complete the overall market engineering process and arrive at precise statistics for each market segment and subsegment, we used data triangulation and market breakdown procedures, where applicable. We triangulated the data by examining factors and trends from both the demand and supply sides of the immunoassay industry.
Market Definition
An immunoassay is a biochemistry-based test that quantifies the presence or concentration of an analyte. An analyte can be a large protein or antibody produced due to an infection. Immunoassays have become popular and well-established procedures in laboratories. They provide quick, accurate, and precise results. This technique is mostly used in clinical diagnostics, drug monitoring, drug discovery, and food testing.
Key Stakeholders
- Manufacturers and vendors of immunoassay instruments and consumables
- Immunoassay product manufacturers
- Pharmaceutical & biopharmaceutical players
- Diagnostic associations
- Research associations involved in infectious and chronic disease research
- Various research and consulting firms
- Distributors of immunoassay instruments and consumables
- Contract manufacturers of immunoassays
- Healthcare institutions
- Research institutes
- Clinical laboratories
Report Objectives
- To describe, segment, and forecast the immunoassay market by product, technology, specimen, application, end user, and region in terms of value
- To forecast the size of the immunoassay market in five main regions (along with their respective key countries): North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, in terms of value
- To provide detailed information about the factors (drivers, restraints, opportunities, and challenges) influencing market growth
- To analyze micromarkets with respect to individual growth trends, prospects, and contributions to the overall immunoassay market
- To analyze market opportunities for stakeholders and provide details of the competitive landscape for key players
- To profile the key players in the immunoassay market and comprehensively analyze their core competencies and market shares
- To analyze competitive developments such as acquisitions, product launches, expansions, collaborations, agreements, partnerships, and R&D activities of the leading players in the market
- To benchmark players within the immunoassay market using the Company Evaluation Matrix framework, which analyzes market players on various parameters within the broad categories of business strategy, market share, and product offerings
Available customizations:
Based on the market data provided, MarketsandMarkets offers customizations tailored to your company’s specific needs. The following customization options are available for the report:
Geographict Analysis
-
Further breakdown of the Rest of Europe immunoassay market into Switzerland, Denmark, Austria, and others
-
Further breakdown of the Rest of Asia Pacific immunoassay market into Hong Kong, Taiwan, and others
-
Further breakdown of the Rest of Latin America immunoassay market into Argentina, Colombia, Chile, Ecuador, and others
-
Further breakdown of the Southeast Asian immunoassay market into Malaysia, Singapore, Australia, New Zealand, and others
Competitive Landscape Assessment
-
Market Share Analysis, by region (North America and Europe), which provides the details about the share of the top 3 to 5 key players in the immunoassay market
-
Competitive leadership mapping for established players in the US
Get the Full Immunoassay Market Report
Full forecast, segment splits, and company analysis for all Immunoassay Market.
- US Immunoassay Market
- Canada Immunoassay Market
- Germany Immunoassay Market
- France Immunoassay Market
- UK Immunoassay Market
- Spain Immunoassay Market
- Italy Immunoassay Market
- Russia Immunoassay Market
- China Immunoassay Market
- Japan Immunoassay Market
- India Immunoassay Market
- South Korea Immunoassay Market
- Indonesia Immunoassay Market
- Brazil Immunoassay Market
- Mexico Immunoassay Market
- Rest Of Europe Immunoassay Market
- Rest Of Asia Pacific Immunoassay Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report