Spain Medical Plastics Market (2026-2031)
The Spain Medical Plastics Market was valued at $854.6 Million in 2026 and projected to reach to $1137.6 Million by 2031, representing a compound annual growth rate of CAGR 5.9%. Spain's medical plastics market is positioned for sustained growth through 2031, supported by the country's commitment to healthcare modernization and EU regulatory standards.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Spain Medical Plastics Market Trends and Insights
- Valued at USD 854.6 million in 2026, Spain's market is expected to expand to USD 1,137.6 million by 2031, reflecting a compound annual growth rate of 5.9%.
- This steady expansion in Spain is driven by increasing demand for advanced medical devices, regulatory compliance requirements, and the country's growing healthcare infrastructure investments. The Spanish medical plastics sector benefits from robust pharmaceutical and medical device manufacturing capabilities.
- Spain's market growth trajectory through 2031 is supported by rising healthcare expenditures and the adoption of innovative polymer solutions in diagnostic and therapeutic applications.
- Spain continues to strengthen its position as a regional hub for medical plastics innovation, with manufacturers focusing on biocompatible and sustainable material solutions to meet evolving clinical standards..
Key Market Statistics
- CAGR (2026-2031) CAGR 5.9%
- Market Size, 2026 ~USD 854.6 Million
- Forecast, 2031 ~USD 1137.6 Million
- Country Spain
Spain Medical Plastics Market Overview
Market Valuation Growth :
Spain's medical plastics market is valued at USD 854.6 million in 2026 and is projected to reach USD 1,137.6 million by 2031, demonstrating robust expansion within the European healthcare materials sector.
Steady CAGR Performance :
With a compound annual growth rate of 5.9% through 2031, Spain's market growth outpaces many European counterparts, driven by modernization of healthcare infrastructure and increased adoption of advanced medical devices.
Regulatory Compliance Drivers :
Spain's alignment with EU medical device regulations and MDR compliance requirements is accelerating demand for high-quality medical plastics in manufacturing, creating opportunities for compliant suppliers.
Healthcare Device Innovation :
Increasing demand for advanced medical devices including diagnostic equipment, surgical instruments, and patient monitoring systems is propelling the consumption of specialized medical-grade plastics across Spanish healthcare facilities.
Spain Medical Plastics Market Dynamics
- The market benefits from Spain's established medical device manufacturing base and growing investments in healthcare infrastructure.
- Demand for innovative plastic materials in diagnostic devices, surgical applications, and patient care equipment continues to accelerate.
- The 5.9% CAGR reflects steady expansion driven by aging demographics, increased healthcare spending, and the shift toward minimally invasive procedures requiring advanced plastic components. Looking ahead, Spain's market will be shaped by continued regulatory evolution, sustainability initiatives, and technological advancements in biocompatible materials.
- Spanish manufacturers are increasingly focusing on high-performance plastics that meet stringent EU standards while reducing environmental impact.
- Strategic partnerships between local medical device companies and material suppliers are expected to strengthen the market ecosystem, creating opportunities for specialized product development and market penetration across Spain's healthcare sector..
Market Ecosystem
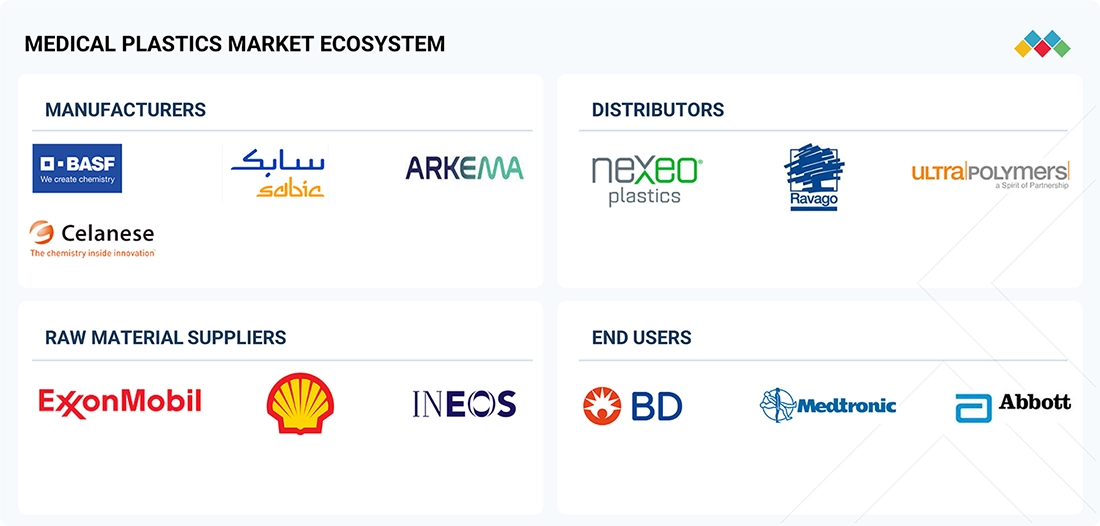
MEDICAL PLASTICS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Lubrizol develops medical-grade thermoplastic polyurethanes (TPUs), specialty polymers, and engineered materials for catheters, wearable medical devices, drug delivery systems, wound care products, prosthetics, and other high-performance medical components. | Outstanding flexibility | Biocompatibility | Abrasion resistance | Chemical resistance | Sterilization compatibility while enabling miniaturization, patient comfort, and long-term device durability in demanding healthcare applications |
 |
Celanese manufactures high-performance medical polymers including acetal (POM), thermoplastic elastomers (TPEs), engineered nylons, and specialty compounds used in surgical instruments, inhalers, insulin pens, diagnostic equipment, implant components, and reusable medical devices. | Excellent mechanical strength | Dimensional stability | Wear resistance | Low friction | Sterilization compatibility, enabling lightweight, durable, and precision-engineered medical products with long service life |
 |
SABIC supplies medical-grade polycarbonate (PC), polypropylene (PP), polyethylene (PE), and specialty copolymers for medical disposables, diagnostic equipment, pharmaceutical packaging, respiratory devices, laboratory consumables, and healthcare electronics. | High impact strength | Optical clarity | Chemical resistance | Gamma and EtO sterilization compatibility | Excellent processability | Comprehensive regulatory documentation, making them ideal for high-volume medical manufacturing |
 |
Covestro provides Makrolon® polycarbonate, thermoplastic polyurethane (TPU), and other specialty medical polymers for medical device housings, diagnostic equipment, infusion systems, surgical instruments, wearable healthcare devices, and pharmaceutical packaging. | Exceptional toughness | Transparency | Design flexibility | Repeated sterilization capability | Biocompatibility while supporting lightweight, durable, and sustainable medical product development |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Resins And Polymers
- Polycarbonate
- Acrylonitrile Butadiene Styrene (ABS)
- Epoxy Resin
- Light Commercial Vehicles (LCVs)
- Polypropylene (PP)
- Basf se
- DOW CHEMICAL COMPANY
- Solvay sa
- Saudi arabia basic industries corporation (sabic)
- DuPont de Nemours, Inc.
Medical Devices
- Polymerase Chain Reaction (PCR)
- Magnetic Resonance Imaging (MRI)
- Disposable Autoinjectors
- Pulse Oximeters
- Blood Pressure Monitors
- Medtronic plc
- Abbott Laboratories
- Stryker Corporation
- Becton, Dickinson and Company
- CONMED Corporation
Key Takeaways
- Spain's medical plastics market will grow from USD 854.6M (2026) to USD 1,137.6M (2031) at a 5.9% CAGR.
- Spain's healthcare infrastructure investments and regulatory compliance drive demand for advanced medical polymer solutions.
- Spain's manufacturers are increasingly adopting biocompatible and sustainable material innovations to meet clinical standards.
- Spain's market benefits from its position as a regional medical device and pharmaceutical manufacturing hub in Europe.
Medical Plastics Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | PP (Type) |
| Forecast Period | 2026-2031 |
| Growth Rate | CAGR of 7% from 2026 to 2031 |
| Largest Segment | OTHER MEDICAL PLASTICS (Type) |
| Market Size Base Year (Billions) | ~USD 34.77 (2026) |
| Revenue Forecast (Billions) | ~USD 48.77 (2031) |
| Segments Covered | Type, Application |
Spain Medical Plastics Market Report Segmentation
2 segment dimensions are covered across the global market.
By Type
- Engineering And High Performance Plastics
- Other Medical Plastics
- Pe
- Pmma
- Pp
- Ps
- Pvc
- -Abs
- -Others
- -Pa
- -Pc
- -Peek
- -Ppsu
- -Psu
By Application
- Drug Delivery
- Medical Disposables
- Medical Instruments & Devices
- Medical Packaging
- Other Applications
- Prosthetics & Implants
Target Audience
- Medical Device Manufacturers : Spanish and European medical device companies need detailed market data to optimize product portfolios, identify sourcing opportunities, and plan expansion strategies within Spain's growing healthcare sector.
- Plastic Material Suppliers : Raw material and specialty plastic manufacturers require Spain-specific demand forecasts and application insights to align production capacity, develop compliant products, and secure contracts with Spanish medical device makers.
- Healthcare Procurement Professionals : Hospital administrators and healthcare procurement teams use market intelligence to evaluate supplier options, negotiate pricing, and ensure access to innovative medical plastic solutions meeting EU standards.
- Investment & Private Equity Firms : Investors evaluating opportunities in Spain's healthcare materials sector need comprehensive market sizing, growth projections, and competitive analysis to assess acquisition targets and portfolio companies.
- Market Entry & Business Development Teams : Companies planning market entry into Spain require localized insights on regulatory pathways, competitive positioning, distribution networks, and customer requirements specific to Spanish medical plastics demand.
Reasons to Buy this Report
- Spain-Specific Market Sizing : Obtain precise valuation data for Spain's medical plastics market with detailed forecasts through 2031, enabling accurate budgeting and investment decisions tailored to the Spanish healthcare landscape.
- Competitive Landscape Intelligence : Understand Spain's unique competitive dynamics, local manufacturer strategies, and market consolidation trends specific to Spanish medical device and plastics sectors.
- Regulatory & Compliance Insights : Access Spain-specific regulatory requirements, EU MDR implementation status, and compliance pathways critical for market entry and product development in Spanish healthcare.
- Growth Opportunity Identification : Identify high-potential segments within Spain's medical plastics market, including emerging applications in diagnostics, surgery, and patient monitoring driving the 5.9% CAGR.
- Strategic Market Positioning : Develop targeted go-to-market strategies for Spain by understanding local demand drivers, healthcare spending patterns, and distribution channels specific to Spanish medical institutions.
Frequently asked questions
What is the current size of Spain's medical plastics market?
Spain's medical plastics market is valued at USD 854.6 million in 2026 and is projected to reach USD 1,137.6 million by 2031.
What is the expected growth rate for Spain's medical plastics market?
Spain's medical plastics market is expected to grow at a compound annual growth rate (CAGR) of 5.9% from 2026 to 2031.
What factors are driving growth in Spain's medical plastics sector?
Spain's market growth is driven by increasing healthcare expenditures, rising demand for advanced medical devices, regulatory compliance requirements, and innovation in biocompatible polymer solutions.
Which applications dominate Spain's medical plastics market?
Spain's medical plastics are primarily used in diagnostic devices, therapeutic applications, pharmaceutical packaging, and medical device components that require biocompatible materials.
How does Spain's market compare to the broader European medical plastics sector?
Spain represents a significant regional market within Europe, with its 5.9% CAGR reflecting steady growth aligned with European healthcare modernization and medical device manufacturing expansion.
RESEARCH METHODOLOGY
The study involved four major activities to estimate the current size of the global medical plastics market. Exhaustive secondary research was carried out to collect information on the market, the peer product market, and the parent product group market. The next step was to validate these findings, assumptions, and sizes with the industry experts across the value chain of medical plastics through primary research. The top-down and bottom-up approaches were employed to estimate the overall size of the market. After that, market breakdown and data triangulation procedures were used to determine the size of different segments and sub-segments of the market.
Secondary Research
The market for companies offering medical plastics was derived from secondary data available through paid and unpaid sources, by analyzing the product portfolios of the major companies in the ecosystem, and by rating the companies based on their performance and quality. Various secondary sources, such as Business Standard, Bloomberg, World Bank, and Factiva, were referred to for identifying and collecting information for this study on the medical plastics market. In the secondary research process, various secondary sources were referred to for identifying and collecting information related to the study. Secondary sources included annual reports, press releases, and investor presentations of door vendors, forums, certified publications, and whitepapers. The secondary research was used to obtain critical information on the industry’s value chain, the total pool of key players, market classification, and segmentation from the market and technology-oriented perspectives.
Primary Research
In the primary research process, various primary sources from the supply and demand sides were interviewed to obtain qualitative and quantitative information for this report. The primary sources from the supply side included industry experts, such as Chief Executive Officers (CEOs), Vice Presidents (VPs), marketing directors, technology and innovation directors, and related key executives from several key companies and organizations operating in the medical plastics market. After the complete market engineering (calculations for market statistics, market breakdown, market size estimations, market forecasting, and data triangulation), extensive primary research was conducted to gather information and verify and validate the critical numbers arrived at.
Primary research was also conducted to identify the segmentation, industry trends, competitive landscape of medical plastics offered by various market players, and key market dynamics, such as drivers, restraints, opportunities, challenges, trends, and key player strategies. In the complete market engineering process, the top-down and bottom-up approaches and several data triangulation methods were extensively used to perform the market estimation and market forecasting for the overall market segments and subsegments listed in this report. Extensive qualitative and quantitative analysis was performed on the complete market engineering process to list the key information/insights throughout the report.
The following is the breakdown of primary respondents:
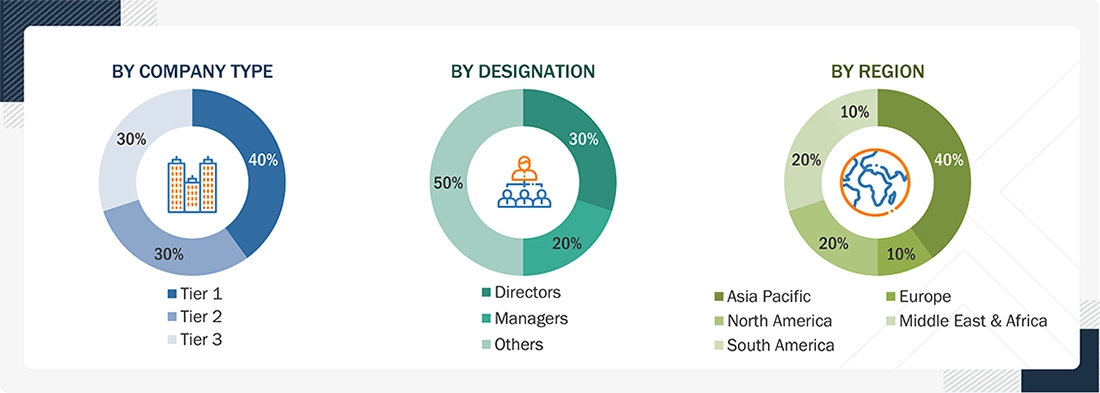
Notes: Other designations include sales, marketing, and product managers.
Tier 1: >USD 1 Billion; Tier 2: USD 500 million–1 Billion; and Tier 3: <USD 500 million.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
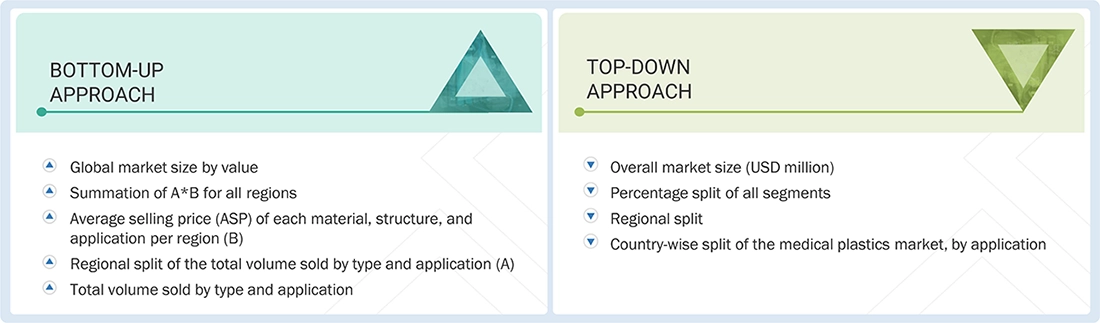
The top-down and bottom-up approaches were used to estimate and validate the size of the global medical plastics market. These approaches were also used extensively to estimate the size of various dependent market segments. The research methodology used to estimate the market size included the following:
Medical Plastics Market : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size using the market size estimation processes, the market was split into several segments and subsegments. The data triangulation and market breakup procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment. The data was triangulated by studying various factors and trends from the demand and supply sides.
Market Definition
Medical plastics refer to polymer materials that are designed specifically for use in medical and life science applications where certain performance parameters such as procedure compatibility, mechanical properties, sterilization, and compliance with regulations are of utmost importance. These materials are widely used to make medical devices such as medical disposables, medical instruments, implants, and drug delivery systems. Generally used plastics are classified as basic plastics, engineering plastics, high-performance plastics, and silicone plastics, and the appropriate plastic type is chosen on the basis of the functional performance required for a particular application. Medical plastics are manufactured with the use of sophisticated processes that include but are not limited to injection molding, extrusion, blow molding, thermoforming, compression molding, and additive manufacturing.
Key Stakeholders
- Medical plastics manufacturers
- Medical-grade polymer and resin suppliers
- Medical device manufacturers
- Pharmaceutical and biotechnology companies
- Healthcare providers (hospitals, clinics, and ambulatory surgical centers)
- Regulatory bodies and industry associations
- Research institutes and diagnostic laboratories
Report Objectives
- To describe and forecast the size of the global medical plastics market, by type and application, in terms of value and volume
- To forecast the market size of segments and subsegments for five regions: North America, Europe, Asia Pacific, South America, and the Middle East & Africa, in terms of value
- To provide detailed information on the significant drivers, restraints, opportunities, and challenges influencing the market
- To strategically analyze micro-markets concerning individual growth trends, prospects, and their contribution to the market
- To assess the growth opportunities in the market for stakeholders and provide details on the competitive landscape for market leaders
- To strategically profile key players and comprehensively analyze their market shares and core competencies
- To analyze competitive developments such as product launches, acquisitions, expansions, partnerships, and agreements in the market
- To analyze the impact of AI on the market
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to client-specific needs.
The following customization options are available for the medical plastics market report:
Product analysis
-
A product matrix that gives a detailed comparison of the product portfolio of each company
Geographic analysis
-
A further breakdown of the medical plastics market for additional countries
Company information
- Detailed analysis and profiling of additional market players (up to five)
Get the Full Medical Plastics Market Report
Full forecast, segment splits, and company analysis for all Medical Plastics Market.
- US Medical Plastics Market
- Canada Medical Plastics Market
- Mexico Medical Plastics Market
- Germany Medical Plastics Market
- France Medical Plastics Market
- UK Medical Plastics Market
- Italy Medical Plastics Market
- China Medical Plastics Market
- Japan Medical Plastics Market
- India Medical Plastics Market
- South Korea Medical Plastics Market
- South Africa Medical Plastics Market
- Brazil Medical Plastics Market
- Argentina Medical Plastics Market
- Rest Of Europe Medical Plastics Market
- Rest Of Asia Pacific Medical Plastics Market
- GCC Medical Plastics Market
- -Rest Of GCC Medical Plastics Market
- Rest Of South America Medical Plastics Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report