China Patient Registry Software Market (2025-2030)
The China Patient Registry Software Market was valued at $87 Million in 2025 and projected to reach to $157.7 Million by 2030, representing a compound annual growth rate of 12.6%. China's patient registry software market is positioned for sustained growth as the nation continues its comprehensive digital health transformation.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
China Patient Registry Software Market Trends and Insights
- This 12.6% compound annual growth rate reflects China's accelerating digital health transformation and government-mandated healthcare modernization initiatives.
- China's healthcare system is increasingly adopting integrated registry solutions to improve patient data management, clinical outcomes, and regulatory compliance across hospitals and primary care facilities. The growth trajectory in China is driven by substantial investments in health information infrastructure, rising chronic disease prevalence, and China's commitment to building a unified national health information system.
- China's aging population and expanding insurance coverage are creating urgent demand for centralized patient data platforms.
- By 2030, China is expected to consolidate its position as a leading adopter of patient registry software in the Asia Pacific region, supported by favorable government policies and increasing interoperability standards..
Key Market Statistics
- CAGR (2025-2030) 12.6% CAGR
- Market Size, 2025 ~USD 87 Million
- Forecast, 2030 ~USD 157.7 Million
- Country China
China Patient Registry Software Market Overview
Rapid Market Expansion :
China's patient registry software market is growing at 12.6% CAGR, significantly outpacing the global average of 9.9%, driven by government-mandated healthcare digitalization and increased investment in health IT infrastructure across provinces.
Government-Driven Modernization :
China's healthcare system is implementing integrated registry solutions as part of national digital health initiatives, with regulatory frameworks pushing hospitals and clinics to adopt standardized patient data management systems.
Market Valuation Growth :
The market is valued at $87.0 million in 2025 and projected to reach $157.7 million by 2030, representing an 81% increase over five years as healthcare providers prioritize patient data centralization and interoperability.
Regional Healthcare Digitalization :
Multi-tier healthcare system adoption across urban and rural China is accelerating registry software deployment, with provincial health commissions mandating electronic patient records and integrated care coordination platforms.
China Patient Registry Software Market Dynamics
- Government policies emphasizing healthcare modernization, coupled with increasing hospital IT budgets and rising demand for integrated care solutions, create favorable conditions for market expansion.
- The shift toward value-based care and population health management is driving adoption of sophisticated registry platforms across major metropolitan areas and secondary cities. Looking ahead to 2030, China's market will benefit from technological advancements in cloud computing, artificial intelligence integration, and interoperability standards.
- Healthcare providers are increasingly recognizing the strategic value of patient registries for clinical decision-making, disease surveillance, and health outcomes research.
- This convergence of regulatory mandates, technological capability, and clinical demand positions China as a high-growth market within the Asia-Pacific region..
Market Ecosystem
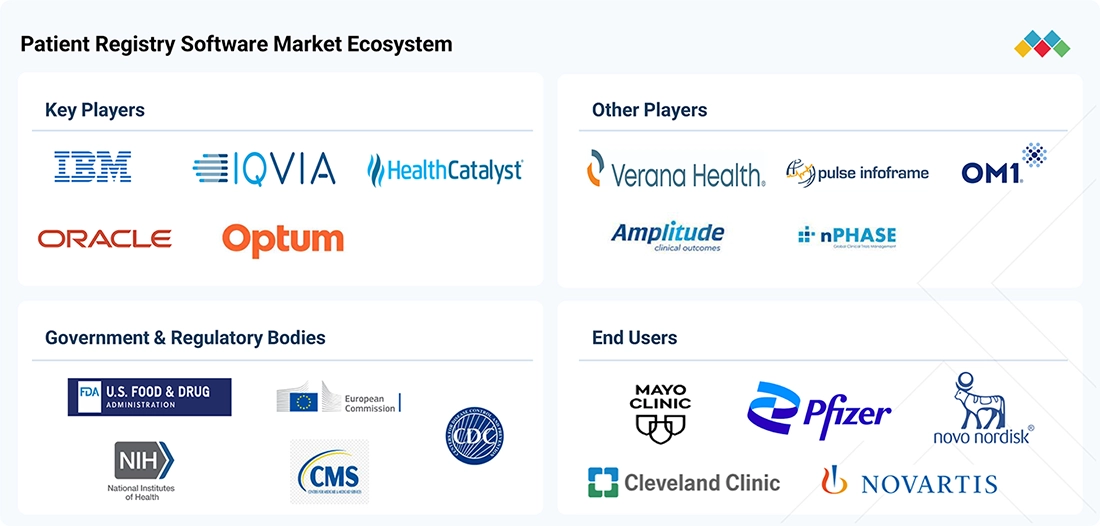
PATIENT REGISTRY SOFTWARE MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Healthcare master data management supporting patient identity resolution, deduplication, longitudinal patient records, and integration of patient data across healthcare applications | InfoSphere MDM for Patient supports patient registries and health information exchange environments. | Improves patient data accuracy and consistency, reduces duplicate records, strengthens patient identity management, and supports interoperability and reliable registry data management. |
 |
Patient registry solutions supporting disease-specific, product, safety, and quality-improvement registries | The Clinical Insight Registry Platform collects research-ready real-world data from clinicians and patients across multiple sites and geographies. | Streamlines longitudinal patient data collection, supports patient-reported and clinician-reported data, enables clinical research and real-world evidence generation, and facilitates quality improvement and patient outcome analysis. |
 |
ARMUS clinical registry software supporting registry development, data abstraction, validation, management, submission, and analytics for hospitals, healthcare systems, and medical societies. | Reduces manual data abstraction effort, improves data quality and registry submission efficiency, supports standardized reporting and benchmarking, and enables analysis of clinical outcomes across providers and facilities. |
 |
Healthcare applications supporting patient registration and data management, alongside public-health capabilities such as immunization registry reporting and immunization management. | Streamlines patient registration and healthcare workflows, supports public-health reporting and immunization data management, and facilitates access to consistent patient information across clinical and administrative processes. |
 |
Healthcare data and analytics solutions supporting patient registries, patient cohort identification, longitudinal data management, and population health analysis through integration of electronic medical records and other healthcare data sources. | Supports patient identification and stratification, enables longitudinal monitoring and outcomes analysis, improves population health management, and helps healthcare organizations use clinical and administrative data for informed care decisions. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Key Takeaways
- China's patient registry software market will grow from $87.0M (2025) to $157.7M (2030), representing a 12.6% CAGR.
- China's digital health initiatives and government mandates are primary catalysts for accelerated market adoption and investment.
- China's aging demographics and chronic disease burden are driving demand for integrated patient data management solutions.
- China is positioned to lead Asia Pacific adoption of patient registry software by 2030 through standardized interoperability frameworks.
Patient Registry Software Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | CLOUD-BASED MODELS (Deployment) |
| Forecast Period | 2025-2030 |
| Growth Rate | CAGR of 9.9% from 2025 to 2030 |
| Largest Segment | DISEASE REGISTRIES (Registry Type) |
| Market Size Base Year (Billions) | ~USD 2.25 (2025) |
| Revenue Forecast (Billions) | ~USD 3.61 (2030) |
| Segments Covered | Registry Type, Type, Product, Use Case, Deployment, End User |
China Patient Registry Software Market Report Segmentation
6 segment dimensions are covered across the global market.
By Registry Type
- Disease Registries
- Product Registries
By Type
- Asthma Registries
- Birth Defect Registries
- Cancer Registries
- Cardiovascular Registries
- Chronic Kidney Registries
- Clinics & Outpatient Settings
- Diabetes Registries
- Drug Registries
- Healthcare Payers
- Healthcare Providers
- Hospitals
- Immunization Registries
- Medical Device Registries
- Medical Specialty Societies
- Orthopedic Registries
- Other Disease Registries
- Other Healthcare Providers
- Patient Organizations
- Pharmaceutical, Biotechnology, And Medtech Companies
- Rare Disease Registries
By Product
- Direct-To-Patient (Patient-Recorded) Registries
- Site-Based/Clinical Data (Provider-Recorded) Registries
By Use Case
- Medical Research & Clinical Studies
- Other Use Cases
- Patient Care Management
- Patient Engagement
- Patient Self-Care
- Point-Of-Care Support
- Population Health
- Public Health Surveillance
- Quality Improvement
By Deployment
- Cloud-Based Models
- On-Premise Models
By End User
- For-Profit Registries
- Government & Third-Party Administrators
- Nonprofit Registries
- Other End Users
CHINA: PATIENT REGISTRY SOFTWARE MARKET, BY END USER, 2023–2030
| Segment | 2023 | 2024 | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | CAGR (%) |
|---|---|---|---|---|---|---|---|---|---|
| FOR-PROFIT REGISTRIES | 37.1 | 41.6 | 46.8 | 52.7 | 59.4 | 67.3 | 76.2 | 86.5 | 13.1 |
| GOVERNMENT & THIRD-PARTY ADMINISTRATORS | 8.6 | 9.5 | 10.5 | 11.7 | 13.1 | 14.6 | 16.4 | 18.4 | 11.7 |
| NONPROFIT REGISTRIES | 20.4 | 22.7 | 25.4 | 28.5 | 31.9 | 35.9 | 40.5 | 45.6 | 12.4 |
| OTHER END USERS | 3.5 | 3.8 | 4.3 | 4.7 | 5.2 | 5.8 | 6.5 | 7.2 | 11.1 |
| TOTAL | 69.5 | 77.7 | 87 | 97.6 | 109.7 | 123.6 | 139.5 | 157.7 | 12.6 |
Target Audience
- Healthcare IT Vendors : Software providers and system integrators need China-specific market intelligence to develop localized solutions, navigate regulatory requirements, identify partnership opportunities, and establish competitive positioning in this rapidly expanding market.
- Hospital & Healthcare Networks : Chinese healthcare administrators and IT directors require market data to evaluate vendor options, benchmark implementation costs, understand peer adoption trends, and justify digital transformation investments to stakeholders.
- Private Equity & Investors : Investment firms evaluating healthcare IT opportunities in China need validated market sizing, growth projections, and competitive dynamics to assess portfolio companies, identify acquisition targets, and evaluate market entry strategies.
- Government & Policy Makers : Healthcare ministry officials and provincial health commission leaders use market research to inform digital health policy, allocate resources, set implementation timelines, and measure progress toward national healthcare modernization goals.
- Consulting & Advisory Firms : Management consultants and healthcare strategy advisors require authoritative China market data to support client engagements, develop implementation roadmaps, benchmark performance, and provide evidence-based recommendations for digital transformation initiatives.
Reasons to Buy this Report
- Market Size & Growth Validation : Obtain precise market valuation data for China ($87.0M in 2025) and verified 5-year forecasts to support investment decisions, business planning, and competitive positioning in this high-growth healthcare IT segment.
- Regulatory & Policy Insights : Understand government-mandated healthcare modernization initiatives driving adoption, including national digital health standards, provincial implementation timelines, and compliance requirements affecting vendor strategy and market entry.
- Competitive Landscape Analysis : Identify key market players, emerging vendors, and competitive dynamics specific to China's healthcare system, including local vs. international provider positioning and differentiation opportunities in this fragmented market.
- Segment & End-User Breakdown : Access detailed segmentation by hospital tier, healthcare facility type, and geographic region to identify high-opportunity customer segments and tailor go-to-market strategies for maximum ROI in China.
- Strategic Growth Opportunities : Discover emerging use cases, integration trends, and technology adoption patterns unique to China's healthcare ecosystem to inform product development, partnership strategies, and market expansion initiatives.
Frequently asked questions
What is the current size of China's patient registry software market?
China's patient registry software market is valued at $87.0 million in 2025 and is expected to grow to $157.7 million by 2030.
What is driving growth in China's patient registry software market?
Growth in China is driven by government digital health mandates, rising chronic disease prevalence, aging population demographics, and investments in national health information infrastructure.
What is the projected CAGR for China's patient registry software market?
China's patient registry software market is projected to grow at a compound annual growth rate of 12.6% from 2025 to 2030.
How does China's market growth compare to global trends?
China's 12.6% CAGR outpaces the global average of 9.9%, reflecting accelerated digital health adoption and government-led healthcare modernization efforts.
What role does China's government play in patient registry software adoption?
China's government actively promotes patient registry software through digital health initiatives, interoperability standards, and mandates for integrated health information systems across healthcare facilities.
RESEARCH METHODOLOGY
The study involved several key activities to estimate the current size of the patient registry software market. Extensive secondary research was conducted to gather information on this market. Next, we validated the findings, assumptions, and size estimates through primary research by consulting industry experts across the value chain. We used top-down and bottom-up approaches to estimate the overall market size. Next, we used market segmentation and data triangulation to determine the size of specific segments and subsegments within the patient registry software market.
Secondary Research
This research study relied heavily on secondary sources, including directories and databases such as Dun & Bradstreet, Bloomberg Businessweek, and Factiva; white papers, annual reports, and companies’ house documents; investor presentations; and companies' SEC filings. Secondary research was used to identify and collect information useful for an extensive, technical, market-oriented, and commercial study of the patient registry software market. It was also used to obtain key information on the key players, market classification & segmentation by industry trends to the most granular level, and key developments from market and technology perspectives. The study also prepared a database of key industry leaders using secondary research.
Some of the key secondary sources referred to for this study include:
- Food and Drug Administration (FDA)
- European Medicines Agency (EMA)
- National Institutes of Health (NIH)
- Agency for Healthcare Research and Quality (AHRQ)
- Centers for Disease Control and Prevention (CDC)
- Centers for Medicare & Medicaid Services (CMS)
- World Health Organization (WHO)
- International Council for Harmonisation of Technical Requirements for Pharmaceuticals for Human Use (ICH)
- Health Level Seven International (HL7)
- European Commission (EU)
- International Organization for Standardization (ISO)
- International Society for Pharmacoeconomics and Outcomes Research (ISPOR)
- Investor Presentations, SEC Filings, and Company Annual Reports
- White Papers, Scientific Journals/Magazines, and News Articles
- Paid Databases, such as Factiva, D&B Hoovers, and Bloomberg
Primary Research
In the primary research process, various sources from both the supply and demand sides were interviewed to obtain qualitative and quantitative information for this report. Primary sources mainly included industry experts from core and related industries, as well as preferred suppliers, manufacturers, distributors, technology developers, researchers, and organizations across all segments of the industry’s value chain. We conducted in-depth interviews with primary respondents, including key industry participants, subject-matter experts (SMEs), C-level executives of key market players, and industry consultants, among others, to gather and verify critical qualitative and quantitative information and assess prospects.
Primary research was conducted to identify segmentation types, industry trends, key players, and key market dynamics such as drivers, restraints, opportunities, challenges, and strategies adopted by key players.
Breakdown of primary respondents:
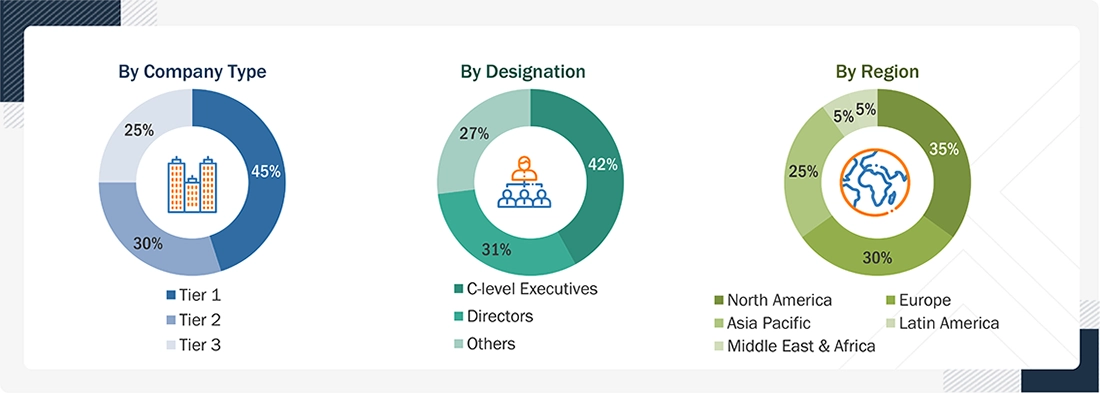
Note 1: Others include sales, marketing, and product managers.
Note 2: Tiers are defined based on a company’s total revenue. As of 2025: Tier 1 = >USD 1 billion, Tier 2 = USD 500 million to USD 1 billion, and Tier 3 = <USD 500 million.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
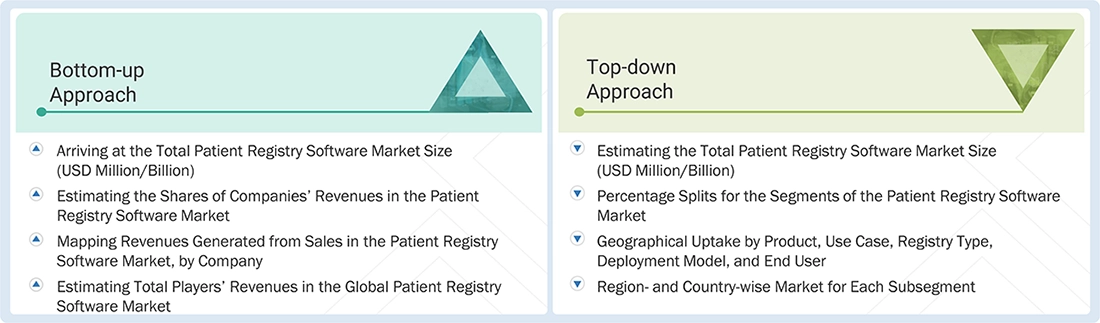
This study's market size estimates and forecasts are derived from a mix of bottom-up (revenue share analysis of leading players) and top-down approaches (assessment of utilization/adoption/penetration trends by product, use case, registry type, deployment model, end user, and region).
Patient Registry Software Market : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size, the market was split into several segments and subsegments using market size estimation processes. To complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment, the data triangulation and market breakdown procedures were employed, wherever applicable. The data was triangulated by analyzing factors and trends from both the demand and supply sides of the patient registry software market.
Market Definition
Patient registry software is a digital tool that systematically collects, stores, manages, and analyzes patient data on specific diseases, conditions, treatments, or outcomes, enabling real-world evidence generation, research support, and improved clinical decision-making. It facilitates longitudinal tracking of patient outcomes, enhances population health management, and supports regulatory compliance and quality improvement initiatives.
Key Stakeholders
- Patient Registry Software Vendors
- Government Bodies
- Healthcare Providers
- Clinical/Physician Centers
- Healthcare Professionals
- Health IT Service Providers
- Healthcare Associations/Institutes
- Venture Capitalists
- Distributors & Resellers
- Maintenance & Support Service Providers
- Integration Service Providers
- Healthcare Payers
- Advocacy Groups
- Investors & Financial Institutions
- Industry Associations & Trade Groups
Report Objectives
- To define, describe, and forecast the global patient registry software market based on product, use case, registry type, deployment model, end user, and region
- To provide detailed information regarding the major factors influencing the growth of the market (drivers, restraints, opportunities, and challenges)
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the overall market
- To analyze the opportunities in the market for stakeholders and provide details of the competitive landscape for market leaders
- To forecast the size of the market segments with respect to five main regions, namely, North America, Europe, Asia, Latin America, and the Middle East & Africa
- To profile key market players and comprehensively analyze their product portfolios, market positions, and core competencies
- To track and analyze competitive developments such as product launches & upgrades; expansions; agreements, partnerships, and acquisitions; and R&D activities in the patient registry software market
Available customizations:
Based on the market data provided, MarketsandMarkets offers customizations to meet your company’s specific needs. The following customization options are available for the report:
Company Information
- Detailed analysis and profiling of additional market players (up to 5)
Geographic Analysis
- Further breakdown of the Rest of Europe patient registry software market into Denmark, Norway, and others
- Further breakdown of the Rest of Asia Pacific patient registry software market into Vietnam, New Zealand, Australia, South Korea, and others
Get the Full Patient Registry Software Market Report
Full forecast, segment splits, and company analysis for all Patient Registry Software Market.
- Canada Patient Registry Software Market
- US Patient Registry Software Market
- UK Patient Registry Software Market
- Germany Patient Registry Software Market
- France Patient Registry Software Market
- Italy Patient Registry Software Market
- Spain Patient Registry Software Market
- Japan Patient Registry Software Market
- India Patient Registry Software Market
- Brazil Patient Registry Software Market
- Mexico Patient Registry Software Market
- Rest Of Europe Patient Registry Software Market
- Rest Of Asia Pacific Patient Registry Software Market
- Rest Of Latin America Patient Registry Software Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report