UK Train Control Systems Market (2017-2022)
The UK Train Control Systems Market was valued at $276.1 Million in 2017 and projected to reach to $401.7 Million by 2022, representing a compound annual growth rate of 7.79%. The UK train control systems market is positioned for sustained growth driven by substantial government investment in rail modernisation and the transition from legacy signalling to integrated digital systems.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
UK Train Control Systems Market Trends and Insights
- The UK's modernisation of rail infrastructure and investment in smart transportation technologies are driving demand for advanced train control solutions.
- The UK's commitment to upgrading legacy signalling systems and implementing European Train Control System (ETCS) standards is accelerating market adoption across both passenger and freight rail networks..
Key Market Statistics
- CAGR (2017-2022) 7.79% CAGR
- Market Size, 2017 ~USD 276.1 Million
- Forecast, 2022 ~USD 401.7 Million
- Country UK
UK Train Control Systems Market Overview
Market Valuation Growth :
The UK train control systems market reached £276.1 million in 2017 and is forecast to grow to £401.7 million by 2022, demonstrating robust expansion in the rail technology sector.
Rail Infrastructure Modernisation :
UK government initiatives to upgrade legacy signalling systems and replace outdated infrastructure are creating significant demand for contemporary train control solutions across the network.
Smart Transportation Investment :
The UK's strategic focus on smart transportation technologies and digital rail systems is accelerating adoption of advanced train control systems among operators and infrastructure providers.
Competitive CAGR Performance :
With a 7.79% CAGR from 2017-2022, the UK market demonstrates strong growth momentum, slightly below the global average of 8.02%, reflecting steady regional demand.
UK Train Control Systems Market Dynamics
- Network Rail's ongoing infrastructure upgrades and the expansion of automated train protection systems across major routes are key catalysts.
- The market will benefit from increased passenger demand, freight efficiency requirements, and regulatory mandates for enhanced safety standards.
- By 2022, the sector is expected to reach £401.7 million as operators prioritise interoperability and real-time monitoring capabilities.
- Future growth will be supported by smart rail initiatives, European Train Control System (ETCS) implementations, and the integration of IoT technologies into UK rail networks..
Market Ecosystem
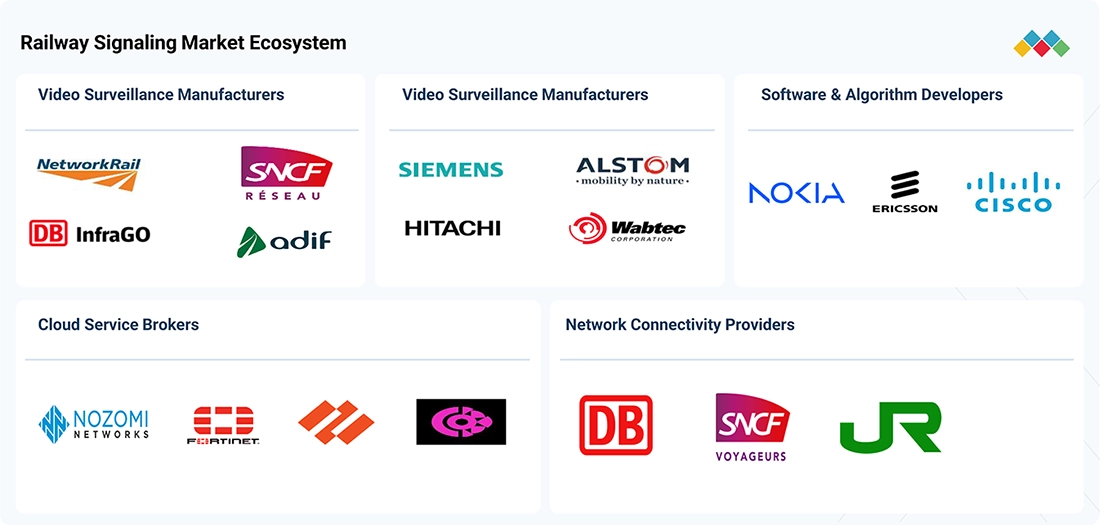
RAILWAY SIGNALING MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Deploys digital interlocking, CBTC, and ERTMS solutions to modernize train-control architectures across urban and mainline networks | Enables shorter headways, higher line capacity, and migration toward software-intensive automated signaling |
 |
Integrates ETCS, digital interlocking, and control systems for high-speed and mainline signaling modernization | Supports higher train throughput and standardized digital control while reducing legacy-system dependency |
 |
Deploys electronic interlocking, ETCS, and CBTC platforms for large-scale network and station modernization | Expands network capacity and enables centralized, real-time train movement management |
 |
Provides CBTC-based signaling and train-control solutions for metro and urban rail networks | Supports high-frequency operations through reduced headways and automation-ready train control |
 |
Combines electronic train management, virtual-block signaling, precision positioning, and communications into integrated train-control systems | Improves corridor capacity and operational visibility while enabling advanced train-control migration |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Key Takeaways
- The UK train control systems market is valued at £276.1 million in 2017 with a forecast of £401.7 million by 2022.
- The UK market is growing at a CAGR of 7.79%, driven by rail infrastructure modernisation and ETCS implementation.
- The UK's investment in smart rail technologies and digital signalling systems is creating significant growth opportunities.
- The UK's regulatory focus on safety and interoperability standards is accelerating adoption of advanced train control solutions.
Train Control Systems Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2017 |
| Fastest Growing Segment | OTHERS (SATELLITE, LTE-R) (Connectivity) |
| Forecast Period | 2017-2022 |
| Growth Rate | CAGR of 8.02% from 2017 to 2022 |
| Largest Segment | COMMUNICATION-BASED TRAIN CONTROL (Solution Type) |
| Market Size Base Year (Billions) | ~USD 2.43 (2017) |
| Revenue Forecast (Billions) | ~USD 3.58 (2022) |
| Segments Covered | Train Type, Component, Connectivity, Solution Type |
UK Train Control Systems Market Report Segmentation
4 segment dimensions are covered across the global market.
By Train Type
- Dmu
- Emu
- Metros & High Speed Trains
By Component
- Human Machine Interface
- Mobile Communication Gateway
- Vehicle Control Unit
By Connectivity
- Gsm-R
- Others (Satellite, Lte-R)
- Tetra
- Wi-Fi
By Solution Type
- Communication-Based Train Control
- Integrated Train Control
- Positive Train Control
Target Audience
- Rail Infrastructure Operators : Network Rail and regional train operating companies need market intelligence to plan signalling upgrades, budget for modernisation projects, and evaluate train control system vendors.
- Technology Solution Providers : Train control system manufacturers and software developers require UK-specific data to identify market opportunities, assess demand drivers, and develop localised product strategies.
- Investment & Finance Professionals : Private equity firms, venture capitalists, and infrastructure investors need accurate UK market forecasts to evaluate acquisition targets and funding opportunities in the rail technology sector.
- Government & Policy Makers : Department for Transport and local transport authorities require market analysis to inform rail modernisation budgets, procurement strategies, and regulatory framework development.
- Consulting & Engineering Firms : Rail consultants and engineering companies need UK market data to support client advisory services, feasibility studies, and project planning for rail infrastructure clients.
Reasons to Buy this Report
- UK-Specific Market Sizing : Access precise valuation data for the UK market (£276.1M in 2017, £401.7M in 2022) enabling accurate budget allocation and investment decisions tailored to the British rail sector.
- Government Policy Insights : Understand how UK rail modernisation programmes and Network Rail's strategic initiatives directly impact train control system demand and procurement timelines.
- Regional Growth Trajectory : Leverage the 7.79% CAGR forecast to identify expansion opportunities and competitive positioning within the UK market over the 2017-2022 period.
- Infrastructure Upgrade Opportunities : Identify specific UK rail operators and infrastructure providers investing in legacy system replacements and ETCS implementations for targeted business development.
- Competitive Benchmarking : Compare UK market performance against global trends (8.02% CAGR) to assess regional competitiveness and strategic positioning within the European rail technology landscape.
Frequently asked questions
What is the current size of the UK train control systems market?
The UK train control systems market was valued at £276.1 million in 2017 and is expected to reach £401.7 million by 2022.
What is the growth rate of the UK train control systems market?
The UK train control systems market is growing at a compound annual growth rate (CAGR) of 7.79% between 2017 and 2022.
What are the main drivers of growth in the UK train control systems market?
Key drivers include the UK's rail infrastructure modernisation, implementation of European Train Control System (ETCS) standards, investment in smart transportation technologies, and regulatory requirements for enhanced safety and interoperability.
Which segments are driving the UK train control systems market?
The UK market is driven by both passenger rail modernisation and freight rail network upgrades, with significant investment in digital signalling and automated train protection systems.
What is the forecast market size for the UK train control systems market by 2022?
The UK train control systems market is forecast to reach £401.7 million by 2022, representing a 45.6% increase from the 2017 baseline of £276.1 million.
RESEARCH METHODOLOGY
The study involved four major activities in estimating the current size of the railway signaling market. Exhaustive secondary research was done to collect information on the market, the peer market, and the child markets. The next step was to validate these findings and assumptions and size them with industry experts across value chains through primary research. The top-down approaches were employed to estimate the complete market size. Thereafter, market breakdown and data triangulation processes were used to estimate the market size of segments and subsegments.
Secondary Research
In the secondary research process, various secondary sources such as company annual report/presentations, press releases, investor presentations of companies, white papers, certified publications, and articles from recognized authors have been used to identify and collect information useful for an extensive commercial study of the global machine tools market.
Primary Research
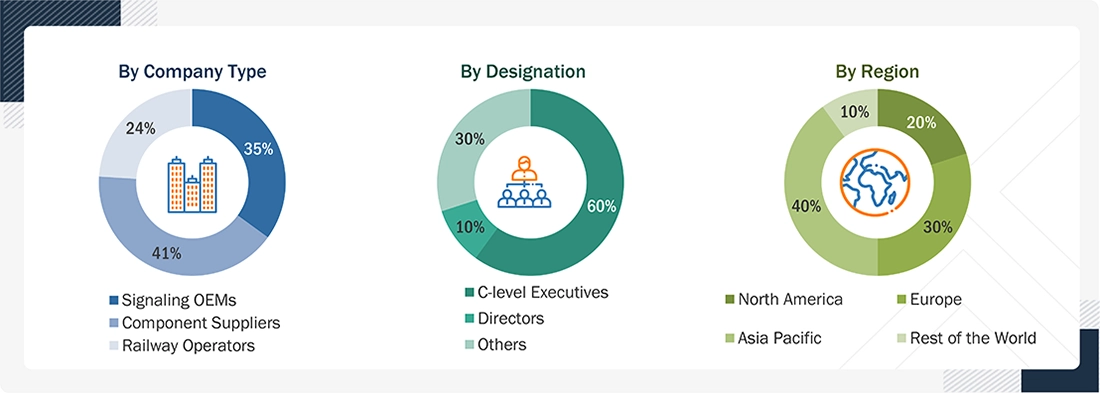
Extensive primary research was conducted after acquiring an understanding of the railway signaling market scenarios through secondary research. Several primary interviews were conducted with market experts from both the demand (railway infrastructure managers, passenger and freight operators, metro and high-speed rail authorities, government railway organizations, regulators, and signaling procurement teams) and supply (signaling OEMs, system integrators, technology and component suppliers, and signaling maintenance/service providers) sides across four major regions: North America, Europe, Asia Pacific, and the Rest of the World (RoW). Approximately 24% and 76% of primary interviews were conducted from the demand and supply sides, respectively. Primary data was collected through questionnaires, emails, and telephonic interviews.
In the canvassing of primaries, various departments within organizations, such as sales, operations, and administration, were covered to provide a holistic viewpoint in the report. After interacting with industry experts, brief sessions were conducted with highly experienced independent consultants to reinforce the findings from primaries. This, along with in-house subject-matter experts’ opinions, led to the findings described in the remainder of this report.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
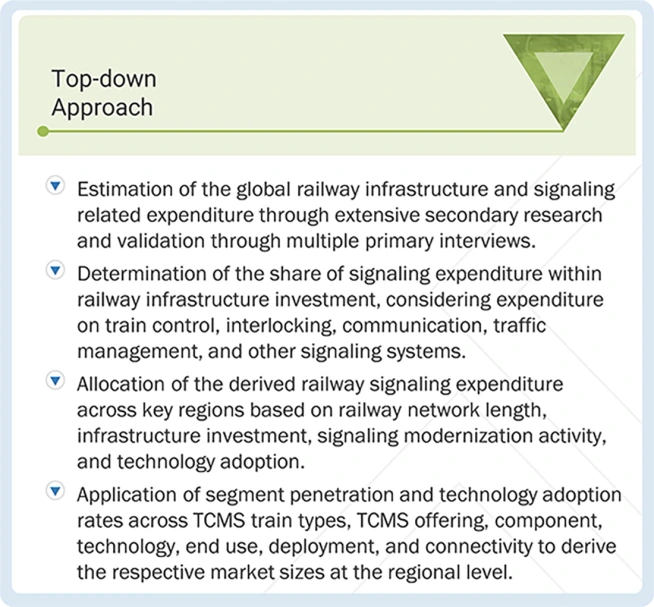
Only the top-down approach was used to estimate and validate the total size of the market. This method was also used extensively to estimate the size of various subsegments in the market. The research methodology used to estimate the market size includes the following:
Railway Signaling Market : Top-Down Approach
Data Triangulation
After arriving at the overall market size- using the market estimation processes as explained above- the market was split into several segments and subsegments. To complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment, data triangulation and market breakdown procedures were employed, wherever applicable. The data was triangulated by studying various factors and trends from both the demand and supply sides.
Market Defination
Railway signaling refers to the integrated systems used to control, supervise, and manage train movements while maintaining safe separation between trains. These systems combine train detection, interlocking, route control, train protection, onboard and wayside equipment, and signaling communications. Key technologies include ABS, CBTC, ETCS, PTC, and ATC, deployed across mainline, urban, high-speed, and freight rail networks. Modern signaling also supports continuous train localization and movement supervision, particularly in digitally controlled and automated railway operations. The market therefore covers signaling hardware, software, system integration, modernization, and associated lifecycle services used for new installations and upgrades of existing networks.
Key Stakeholders
- Railway Operators & Infrastructure Managers
- Signaling OEMs & System Integrators
- Signaling Component Suppliers
- Railway Infrastructure Contractors
- Rolling Stock OEMs
- Rail Regulators & Safety Authorities
- Standards Organizations & Industry Associations
- Testing, Certification, and Assessment Bodies
Report Objectives
-
To define, segment, and forecast the size of the railway signaling market in terms of value (USD billion) based on the following categories: TCMS train type, TCMS offering, component, technology, end-use, deployment, connectivity, and region
- TCMS Train Type [Light-Rail & Metros (DMU & EMU), High Speed Trains, Conventional Passenger Trains, Freight Trains]
- TCMS Offering (Solutions and Services)
- Component (Hardware and Software)
- Technology [Automatic Block Signaling (ABS), Communications-Based Train Control (CBTC), European Train Control System (ETCS), Positive Train Control (PTC), Automatic Train Control (ATC)]
- End-use (Mainline, Urban, Freight)
- Region [North America, Europe, Asia Pacific, and RoW]
- To cover infrastructure foundations, deployment, and connectivity segments qualitatively
- To evaluate the key market dynamics influencing the railway signaling market, including strategic drivers, restraints, opportunities, challenges, and emerging technology trends shaping future industry growth
-
To study the following with respect to the market:
- Supply Chain Analysis
- Ecosystem Analysis
- Technology Analysis
- Trade Analysis
- Case Study Analysis
- Supplier Analysis
- Investment and Funding Scenario
- Company Valuation and Financial Metrics
- Brand/Product Comparison
- Patent Analysis
- Regulatory Landscape
- Conferences and Events
- Future Revenue Models for Railway Signaling Industry
- Global Capex Pipeline Analysis
- Future Communication Technologies
- EU-India Trade Deal: Impact Analysis
- Israel-Iran Impact on Railway Signaling Market
- Railway Digitalization Roadmap
- OEM Technology Benchmarking
- To strategically analyze segments with respect to individual growth trends, prospects, and contributions to the total market
- To assess the competitive landscape by profiling leading global market participants based on their business overview, product portfolio, geographic presence, financial performance, and recent strategic developments such as product launches, partnerships, acquisitions, and capacity expansions
- To map the competitive ecosystem by categorizing market participants into Stars, Emerging Leaders, Pervasive Players, and Participants using a robust evaluation framework based on the strength of their product portfolio, business strategy, innovation capability, and market presence
Available customizations:
With the given market data, MarketsandMarkets offers customizations in line with company-specific needs.
- Further breakdown for the railway signaling market, by TCMS train type, at the country level (for countries covered in the report)
- Further breakdown for the railway signaling market, by end-use, at the country level (for countries covered in the report)
Company Profiles
- Profiles of additional market players (up to five)
Get the Full Train Control Systems Market Report
Full forecast, segment splits, and company analysis for all Train Control Systems Market.
- US Train Control Systems Market
- Canada Train Control Systems Market
- Mexico Train Control Systems Market
- Germany Train Control Systems Market
- France Train Control Systems Market
- Italy Train Control Systems Market
- Spain Train Control Systems Market
- China Train Control Systems Market
- Japan Train Control Systems Market
- India Train Control Systems Market
- South Korea Train Control Systems Market
- Brazil Train Control Systems Market
- Russia Train Control Systems Market
- UAE Train Control Systems Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report