North America Smart Greenhouse Market (2020-2025)

The North America Smart Greenhouse Market was valued at $306 Million in 2020 and projected to reach to $493 Million by 2025, representing a compound annual growth rate of 10.0%. North America's smart greenhouse market is positioned for sustained expansion through 2025, driven by technological advancement and environmental consciousness.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
North America Smart Greenhouse Market Trends and Insights
- This 10.0% compound annual growth rate reflects North America's leadership in agricultural technology adoption and digital farming solutions.
- North America's market expansion is driven by increasing demand for sustainable farming practices, labor cost pressures, and technological advancement in IoT and automation systems. In North America, the smart greenhouse sector benefits from strong regulatory support for sustainable agriculture and significant investment in agtech innovation.
- North America's established infrastructure and high technology penetration rates position the region as a key growth market.
- By 2025, North America is expected to capture substantial market share through continued integration of climate control systems, crop monitoring sensors, and data analytics platforms within greenhouse operations..
Key Market Statistics
- CAGR (2020-2025) 10.0% CAGR
- Market Size, 2020 ~USD 306 Million
- Forecast, 2025 ~USD 493 Million
- Geography North America
North America Smart Greenhouse Market Overview
Market Growth Trajectory :
North America's smart greenhouse market grew from $306.0 million in 2020 to $493.0 million in 2025, representing a robust 10.0% CAGR, outpacing the global average of 9.2%.
Technology Leadership :
North America leads in agricultural technology adoption, with advanced IoT integration, climate control systems, and data analytics driving competitive advantage in precision farming.
Sustainability Focus :
Increasing regulatory pressure and consumer demand for sustainable farming practices are accelerating smart greenhouse adoption across the United States and Canada.
Investment Momentum :
Venture capital and government agricultural subsidies in North America are fueling innovation in automated growing systems and environmental monitoring solutions.
North America Smart Greenhouse Market Dynamics
- The region's mature agricultural infrastructure and high technology adoption rates create ideal conditions for smart greenhouse deployment.
- Investment in R&D and favorable government policies supporting sustainable agriculture will continue to accelerate market penetration. The forecast period will see increased consolidation among technology providers and integration of AI-powered crop management systems.
- North American growers are prioritizing yield optimization and resource efficiency, positioning smart greenhouses as essential infrastructure.
- Continued urbanization and local food production trends will further strengthen market demand across the region..
Market Ecosystem
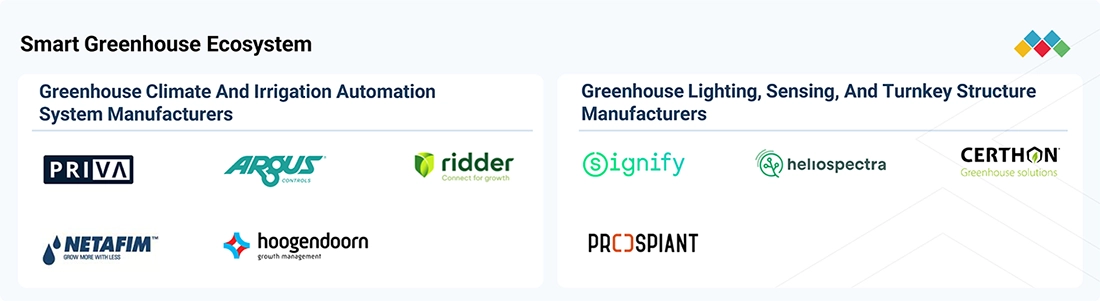
SMART GREENHOUSE MARKET SIZE, SHARE & GROWTH, 2036: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Denso deploys automated agricultural solutions, including Profarm climate controllers and harvesting robotic systems. The hardware automates indoor climate regulation, monitors greenhouse ambient parameters, and manages crop handling across commercial tomato and vegetable cultivation facilities. | Automates internal climate conditions without manual labor intervention | Delivers continuous monitoring of microclimate fluctuations | Reduces operational labor expenses across harvesting workflows | Improves overall commercial crop yield through consistent climate maintenance |
 |
Orbia provides precision drip irrigation and fertigation systems through its Netafim business group. The infrastructure automates the injection of liquid nutrients, manages water distribution pipelines, and measures real-time soil moisture levels in commercial covered crop facilities. | Lowers total water consumption compared to overhead watering | Delivers uniform distribution of fertilizers directly to plant root zones | Prevents nutrient leaching and ground contamination | Increases crop uniformity across large scale cultivation areas |
 |
Signify supplies Philips GreenPower LED horticultural lighting modules and grow control software. The luminaires provide tailored light recipes with specific spectral outputs, automated photoperiod timing, and dynamic dimming for high-wire vegetables and leafy greens. | Provides customized light spectrums suited for specific crop growth phases | Accelerates plant growth cycles while reducing overall electrical draw | Delivers lower heat emissions compared to conventional high pressure sodium fixtures | Extends operational production seasons during low sunlight winter months |
 |
Ridder delivers greenhouse drive systems, climate screens, and Synopta climate management software. The integrated equipment regulates greenhouse shading curtains, ventilation window positioning, and heating cycles to stabilize internal temperature and humidity. | Regulates solar radiation penetration and thermal heat retention | Delivers precise mechanical window positioning for uniform airflow distribution | Lowers facility heating costs through dual-layer thermal screens | Protects delicate commercial crops from excessive external heat exposure |
 |
Gibraltar supplies engineered greenhouse structures and automated growing systems through its Prospiant brand. The company fabricates heavy-duty commercial glass and polycarbonate greenhouses integrated with environmental control equipment, benching systems, and air circulation units. | Delivers structural durability against extreme wind and snow load conditions | Provides scalable modular floorplans for broad commercial expansion | Maximizes natural daylight transmission across growing areas | Integrates mechanical ventilation seamlessly with structural frameworks |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Sensors And Control
- Sensors
- Temperature Sensors
- Image Sensors
- Pressure Sensors
- Flow Sensors
- BAUMER ELECTRIC AG
- HONEYWELL INTERNATIONAL INC.
- Stmicroelectronics
- Lenovo
- Texas Instruments Incorporated
Key Takeaways
- North America's smart greenhouse market is projected to grow from $306.0M (2020) to $493.0M (2025) at a 10.0% CAGR.
- North America leads in technology adoption driven by labor shortages and sustainability mandates across the region.
- North America's market growth is supported by strong venture capital funding and government agricultural innovation initiatives.
- North America's competitive landscape features both established agricultural equipment manufacturers and emerging agtech startups.
Smart Greenhouse Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2020 |
| Fastest Growing Segment | SOUTH AMERICA (Americas) |
| Forecast Period | 2020-2030 |
| Growth Rate | CAGR of 9.2% from 2020 to 2030 |
| Largest Segment | NORTH AMERICA (Americas) |
| Market Size Base Year (Billions) | ~USD 1.35 (2020) |
| Revenue Forecast (Billions) | ~USD 3.26 (2030) |
| Segments Covered | Type, Covering Material Type, Offering, Component, End User, Americas |
North America Smart Greenhouse Market Report Segmentation
6 segment dimensions are covered across the global market.
By Type
- Hydroponics
- Non-Hydroponics
By Covering Material Type
- Polycarbonate
- Polyethylene
By Offering
- Hardware
- Services
- Software
- Software & Services
By Component
- Control Systems & Sensors
- Hvac Systems
- Led Grow Lights
By End User
- Commercial Growers
- Research & Educational Institutes
- Retail Gardens
By Americas
- South America
Target Audience
- Agricultural Technology Providers : Manufacturers and software developers need North America-specific market data to identify growth opportunities, optimize product positioning, and allocate R&D resources effectively.
- Greenhouse Operators & Farmers : Commercial growers require market insights to evaluate smart greenhouse ROI, benchmark against regional competitors, and make informed technology investment decisions.
- Investment & Private Equity Firms : Investors need comprehensive North American market analysis to assess portfolio opportunities, evaluate acquisition targets, and understand regional growth potential and exit strategies.
- Government & Policy Makers : Agricultural agencies and policymakers use market data to design effective subsidy programs, assess technology adoption rates, and develop sustainable farming initiatives.
- Distributors & Channel Partners : Resellers and distributors need North America market forecasts to optimize inventory, identify emerging demand segments, and develop effective sales strategies for regional customers.
Countries within North America - compare and drill down
| Country | 2025 size (native) |
|---|
Country market size visualization
Reasons to Buy this Report
- Regional Market Sizing : Accurate valuation of North America's smart greenhouse market with verified 2020-2025 data enables precise budget allocation and competitive benchmarking specific to your regional operations.
- Growth Opportunity Identification : Understand the 10% CAGR drivers unique to North America, including regulatory incentives, technology adoption patterns, and investment trends to identify high-potential market segments.
- Competitive Landscape Intelligence : Gain insights into North American market dynamics, key players, and technology preferences to develop targeted go-to-market strategies and differentiation approaches.
- Investment Decision Support : Leverage comprehensive North America-specific forecasts and market analysis to justify capital investments, secure stakeholder buy-in, and plan expansion strategies.
- Strategic Planning Framework : Access detailed North American market trends, sustainability drivers, and technology adoption patterns to inform product development and market entry strategies.
Frequently asked questions
What is the projected market size for smart greenhouses in North America by 2025?
North America's smart greenhouse market is forecasted to reach $493.0 million by 2025, up from $306.0 million in 2020.
What is the CAGR for North America's smart greenhouse market?
North America's smart greenhouse market is expected to grow at a compound annual growth rate of 10.0% between 2020 and 2025.
What factors are driving growth in North America's smart greenhouse market?
North America's market growth is driven by labor cost pressures, sustainability regulations, increasing adoption of IoT technologies, and demand for year-round crop production.
Which countries in North America are leading the smart greenhouse adoption?
The United States and Canada are the primary markets in North America, with the U.S. representing the largest share due to its advanced agricultural technology infrastructure.
What technologies are most prevalent in North America's smart greenhouses?
North America's smart greenhouses predominantly feature climate control systems, automated irrigation, crop monitoring sensors, and data analytics platforms for yield optimization.
RESEARCH METHODOLOGY
The research process for this study involved the systematic gathering, recording, and analysis of data on customers and companies operating in the smart greenhouse market. This process involved the extensive use of secondary sources, directories, and databases (Factiva and OANDA) to identify and collect valuable information for a comprehensive, technical, market-oriented, and commercial study of the market. In-depth interviews were conducted with primary respondents, including experts from core and related industries, as well as preferred manufacturers, to obtain and verify critical qualitative and quantitative information and assess growth prospects. Key players were identified through secondary research, and their market rankings were determined through a combination of primary and secondary research. This research involved studying the annual reports of top players and conducting interviews with key industry experts, including CEOs, directors, and marketing executives.
Secondary Research
Various sources were utilized in the secondary research process to identify and collect information relevant to this study. These include company annual reports, press releases, investor presentations, white papers, technology journals, certified publications, articles by recognized authors, directories, and databases. Secondary research was primarily used to gather key information on the industry’s value chain, the total pool of market players, market classification by industry trends at the most detailed level, regional markets, and key developments from market- and technology-oriented perspectives.
Primary Research
Primary research was also conducted to identify the segmentation types, key players, competitive landscape, and key market dynamics, including drivers, restraints, opportunities, challenges, and industry trends, as well as key strategies adopted by players operating in the smart greenhouse market. Extensive qualitative and quantitative analyses were conducted across the complete market engineering process to present key information and insights throughout the report.
Extensive primary research has been conducted following the acquisition of knowledge about the market scenarios through secondary research. Several primary interviews were conducted with experts from the demand side and the supply side across four major geographic regions: North America, Europe, Asia Pacific, and RoW. Approximately 60% and 40% of the primary interviews were conducted from the supply and demand sides, respectively. These primary data have been collected through questionnaires, emails, and telephonic interviews.
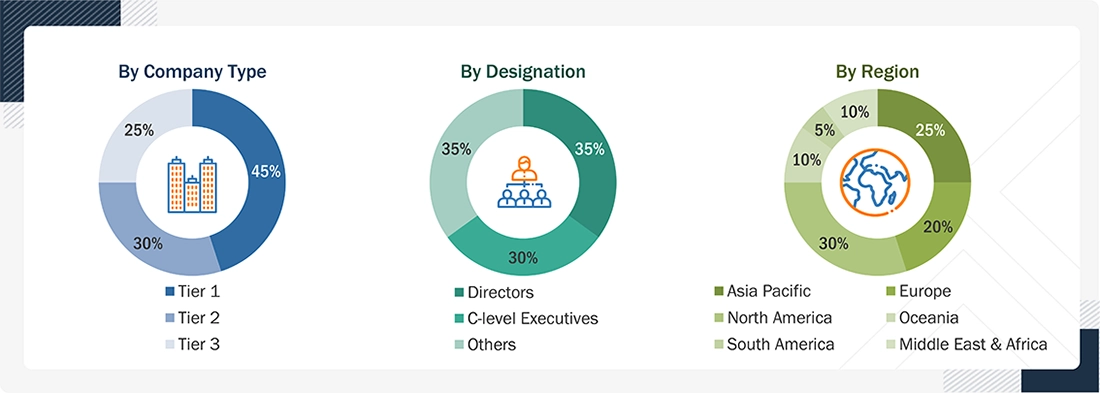
Notes: The three tiers of companies have been defined based on their total/segmental revenue as of 2025: Tier 1 = > USD 1 billion, Tier 2 = USD 1 billion–USD 500 million, and Tier 3 = < USD 500 million.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
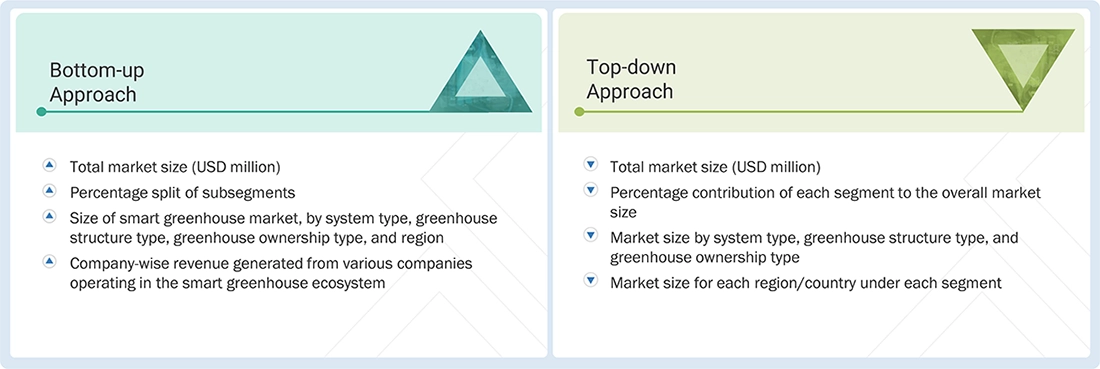
In the complete market engineering process, the top-down and bottom-up approaches, along with several data triangulation methods, were used to estimate and validate the size of the smart greenhouse market and various other dependent submarkets. Key players were identified through secondary research, and their market share in each region was determined through a combination of primary and secondary research. This research methodology involved analyzing the annual and financial reports of the top players and conducting interviews with experts (CEOs, VPs, directors, and marketing executives) to gather key insights (both quantitative and qualitative).
All percentage shares, splits, and breakdowns were determined using secondary sources and verified through primary sources. All possible parameters affecting the markets covered in this study were accounted for, examined in detail, verified through primary research, and analyzed to obtain final quantitative and qualitative data. This data was consolidated and supplemented with detailed inputs and analysis from MarketsandMarkets and presented in this report.
Data Triangulation
After determining the overall market size through the estimation process, as explained above, the total market was divided into several segments and subsegments. To complete the overall market engineering process and obtain precise statistics for all segments and subsegments, the data triangulation procedure was employed, as applicable. The data were triangulated by studying various factors and trends from the demand and supply sides. Additionally, the market has been validated using both top-down and bottom-up approaches.
Market Definition
Greenhouses that independently maintain the conducive microclimate required for crop cultivation without any human intervention are called smart greenhouses. They regulate light, air temperature, soil moisture, and humidity level to enable healthy plant growth. A number of smart greenhouses capture solar energy for electricity generation without impacting crop growth. Hydroponics and non-hydroponics are the techniques used in smart greenhouses for the cultivation of fruits, flowers, and vegetables. Increased demand for food worldwide, owing to the continuously growing population, is driving the smart greenhouse market.
Key Stakeholders
- Raw material and hardware manufacturing equipment suppliers
- Original equipment manufacturers (OEMs)
- Original design manufacturing (ODM) and original equipment manufacturing (OEM) technology solution providers
- Sensor providers
- Individual and large growers
- Research organizations
- Technology standard organizations, forums, alliances, and associations
- Technology investors
- Governments, financial institutions, and investment communities
- Analysts and strategic business planners
- End users
Report Objectives
- To describe and forecast the smart greenhouse market, based on system type, greenhouse structure type, and greenhouse ownership type, in terms of value
- To define and forecast the market size with regard to four main regions: North America, Europe, Asia Pacific, and RoW, in terms of value
- To provide detailed information regarding drivers, restraints, opportunities, and challenges influencing the market growth
- To understand the impact of artificial intelligence (AI) on the market
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the total market
- To provide a qualitative overview of different smart greenhouse technologies
- To analyze opportunities for various stakeholders by identifying high-growth segments of the market
- To strategically profile key players and comprehensively analyze their market position in terms of ranking and core competencies, along with detailing the competitive landscape of the market
- To analyze competitive developments, such as acquisitions, product launches, developments, and partnerships in the market
- To provide a detailed overview of the ecosystem analysis, case study analysis, patent analysis, trade analysis, technology analysis, average selling price (ASP) analysis, AI/Gen AI impact analysis, Porter’s five forces analysis, macroeconomic outlook, and regulatory landscape pertaining to the market
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to the company’s specific needs. The following customization options are available for the report:
Company Information
- Detailed analysis and profiling of additional market players (up to 5)
Get the Full Smart Greenhouse Market Report
Full forecast, segment splits, and company analysis for all Smart Greenhouse Market.
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
