Canada SOC as a Service (SOCaaS) Market (2024-2029)

The Canada SOC as a Service (SOCaaS) Market was valued at $577.5 Million in 2024 and projected to reach to $1128.7 Million by 2029, representing a compound annual growth rate of 11.8%. Canada's SOCaaS market is positioned for sustained expansion as organizations prioritize cybersecurity investments amid evolving threat landscapes and regulatory pressures.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Canada SOC as a Service (SOCaaS) Market Trends and Insights
- This expansion reflects Canada's increasing reliance on managed security operations to combat evolving cyber threats and regulatory compliance demands.
- Canadian enterprises across financial services, healthcare, and critical infrastructure are accelerating adoption of SOCaaS solutions to reduce operational overhead and enhance threat detection capabilities. The Canadian SOCaaS market is driven by heightened cybersecurity awareness, stringent data protection regulations, and the shift toward cloud-based security infrastructure.
- Canada's growing digital economy and cross-border data flows with the United States create urgent demand for scalable, cost-effective security monitoring.
- By 2029, Canada is expected to solidify its position as a key SOCaaS market in North America, with organizations increasingly outsourcing security operations to specialized service providers rather than maintaining in-house security centers..
Key Market Statistics
- CAGR (2024-2029) 11.8% CAGR
- Market Size, 2024 ~USD 577.5 Million
- Forecast, 2029 ~USD 1128.7 Million
- Country Canada
Canada SOC as a Service (SOCaaS) Market Overview
Market Valuation Growth :
Canada's SOCaaS market is valued at $577.5 million in 2024, with projections reaching $1,128.7 million by 2029, representing a robust 11.8% CAGR driven by heightened cybersecurity awareness.
Regulatory Compliance Drivers :
Canadian enterprises face stringent data protection regulations including PIPEDA and sector-specific requirements, compelling organizations to adopt managed SOC services for compliance and risk mitigation.
Sector-Specific Adoption :
Financial services, healthcare, and critical infrastructure sectors in Canada are accelerating SOCaaS adoption to address sophisticated cyber threats and maintain operational resilience in regulated environments.
Managed Security Demand :
Canadian organizations increasingly prefer outsourced security operations over in-house SOCs due to talent scarcity, cost efficiency, and the need for 24/7 threat monitoring and incident response capabilities.
Canada SOC as a Service (SOCaaS) Market Dynamics
- The 11.8% CAGR reflects strong demand from enterprises seeking specialized security expertise and continuous monitoring capabilities without substantial capital expenditure.
- Financial institutions and healthcare providers are leading adoption, driven by compliance mandates and high-value asset protection requirements. Looking ahead, the Canadian market will benefit from increased digital transformation initiatives, remote work infrastructure security needs, and growing awareness of managed security services' strategic value.
- As cyber incidents become more sophisticated and costly, Canadian enterprises will continue shifting toward SOCaaS solutions that offer scalability, advanced threat intelligence, and expert-led incident response, positioning the market for accelerated growth through 2029..
Market Ecosystem
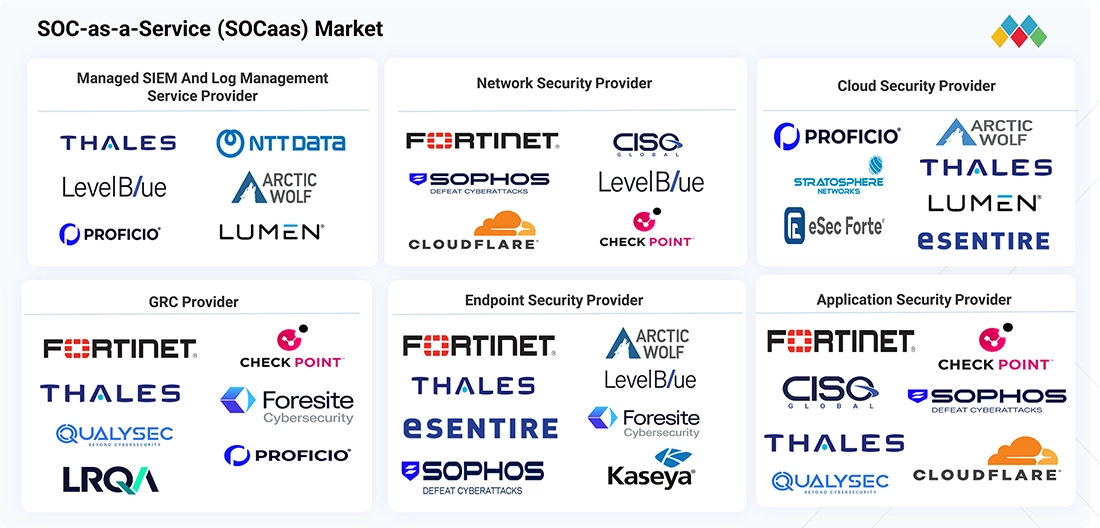
SOC AS A SERVICE (SOCAAS) MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Verizon deployed its Advanced Security Operations Center and SIEM capabilities for FUJIFILM Holdings, enabling centralized, 24/7 security monitoring and threat detection across global subsidiaries and business units. | Improved global threat visibility, earlier detection of suspicious behavior, faster incident response, centralized log monitoring, enhanced threat intelligence, and more consistent security surveillance across international operations |
 |
Fortinet provided Grand View University with FortiGuard Managed Detection and Response (MDR) and SOC-as-a-Service to enable proactive, 24/7 network monitoring, automated alerting, and centralized security reporting. | Improved threat visibility, early identification of critical security events, reduced manual log analysis, avoided in-house SIEM investment, simplified reporting, and better management of the university’s security posture |
 |
Chillisoft and its New Zealand security consortium partners extended managed cybersecurity services to Fiji, providing organizations access to SOC-as-a-Service, continuous threat monitoring, and expert-led security support. | Expanded access to specialized cybersecurity expertise, 24/7 threat detection, reduced security management complexity, faster remediation, and scalable protection for organizations with limited in-house security resources |
|
|
SecureCyber deployed Fortinet FortiSIEM, FortiEDR, and FortiSOAR to expand its managed security services, delivering customized, multitenant SOC-as-a-Service dashboards and threat monitoring to customers. | Generated a seven-figure revenue stream, accelerated time to market for managed detection services, improved response times from 45 minutes to two minutes in some cases, and automated low-level alerts |
|
|
Murata Machinery USA adopted Fortinet FortiGuard SOC-as-a-Service for 24/7 security monitoring, improving threat visibility across global operations without requiring its lean IT team to monitor continuously. | Extended security monitoring coverage without hiring two or three additional staff members, improved incident investigation, strengthened threat visibility, and enabled more effective user education following security incidents |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Driving Support Security
- Battery Electric Vehicle (BEV)
- Hybrid Electric Vehicle (HEV)
- Light Commercial Vehicles (LCVs)
- Fuel Cell Electric Vehicle (FCEV)
- Blind Spot Detection (BSD)
- BOSCH LIMITED
- Continental ag
- DENSO Corporation
- Magna International Inc.
- ZF FRIEDRICHSHAFEN AG
Cloud Computing
- Software as A Service (SaaS)
- Natural Language Processing (NLP)
- Platform as A Service (PaaS)
- Machine Learning
- Supply Chain Management
- International Business Machines Corporation
- MICROSOFT CORPORATION
- Oracle Corporation
- Amazon.com, Inc.
Cyber Security
- Cloud Security
- Biometric Systems
- Data Loss Prevention (DLP)
- Multi-Factor Authentication
- Security Analytics
- International Business Machines Corporation
- Cisco Systems, Inc.
- MITSUI BUSSAN SECURE DIRECTIONS INC
- MICROSOFT CORPORATION
- Allot Ltd.
Key Takeaways
- Canada's SOCaaS market will nearly double from $577.5M (2024) to $1,128.7M (2029), representing an 11.8% CAGR.
- Canadian regulatory frameworks and data sovereignty requirements are accelerating SOCaaS adoption among enterprises.
- Canada's proximity to the U.S. market and integrated supply chains drive demand for advanced threat intelligence and monitoring.
- Canadian mid-market and large enterprises are increasingly outsourcing security operations to reduce capital expenditure and access specialized expertise.
SOC as a Service (SOCaaS) Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | HEALTHCARE (Vertical) |
| Forecast Period | 2024–2029 |
| Growth Rate | CAGR of 12.2% from 2024 to 2029 |
| Largest Segment | LARGE ENTERPRISES (Organization Size) |
| Market Size Base Year (Billions) | ~USD 7.35 (2024) |
| Revenue Forecast (Billions) | ~USD 14.66 (2029) |
| Segments Covered | Service Type, Offering, Organization Size, Security Type, Sector, Vertical |
Canada SOC as a Service (SOCaaS) Market Report Segmentation
6 segment dimensions are covered across the global market.
By Service Type
- Grc
- Incident Response
- Managed Siem & Log Management
- Threat Detection & Remediation
- Vulnerability Scanning & Assessment
By Offering
- Co-Managed
- Fully Managed
By Organization Size
- Large Enterprises
- Smes
By Security Type
- Application Security
- Cloud Security
- Endpoint Security
- Network Security
By Sector
- Private Sector
- Public Sector
By Vertical
- Bfsi
- Energy & Utilities
- Government
- Healthcare
- It & Ites
- Manufacturing
- Telecommunications
- Transportation & Logistics
Target Audience
- Canadian Enterprise Security Leaders : CISOs and security directors in Canada need market intelligence to justify SOCaaS investments, benchmark against peers, and align security strategies with market trends and regulatory requirements.
- SOCaaS Vendors & Service Providers : Solution providers targeting Canada require detailed market sizing, growth forecasts, and sector-specific adoption data to develop localized strategies, identify customer segments, and optimize resource allocation.
- Financial Services & Healthcare Institutions : Regulated organizations in Canada's financial and healthcare sectors need SOCaaS market analysis to evaluate managed security options, assess vendor capabilities, and make informed procurement decisions.
- Investment & Strategy Consultants : Consultants advising Canadian enterprises on digital transformation and cybersecurity require market data to support recommendations, validate business cases, and guide clients through SOCaaS adoption decisions.
- Technology Investors & Analysts : Investors and equity analysts covering Canadian ICT markets need comprehensive SOCaaS data to evaluate market opportunities, assess portfolio companies, and identify emerging trends in managed security services.
Key Companies in the Canada SOC as a Service (SOCaaS) Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| LUMEN TECHNOLOGIES | United States | Public Company | Enterprise network services (IP, ethernet, VPN, optical, SD-WAN),Mass-market broadband and voice (residential and small business),Legacy services (TDM voice, SONET, legacy hosting, conferencing), |
| CHECK POINT | Israel | Public Company | Mesh Network Security (firewalls, gateways, security management),Workspace Security Platform (email, endpoint, mobile, browser, XDR),Threat Exposure & AI Security Platforms, |
| TRUSTWAVE | United States | Private Company | Managed Detection and Response (MDR),Managed Security Services (incl. co-managed SOC/SIEM),Consulting & Professional Services, |
| INSPIRISYS | India | Public Company | Infrastructure & Managed IT Services,Cybersecurity & SOC Services,Cloud & IoT Solutions, |
LUMEN TECHNOLOGIES
Lumen Technologies is a United States-based public company founded in 1968 with 21,000 employees that provides communications and technology infrastructure services.
CHECK POINT
Check Point is an Israeli public company founded in 1993 with 6,825 employees that develops cybersecurity software and services for network and cloud protection.
TRUSTWAVE
Trustwave is a United States-based private company founded in 1995 with 590 employees that offers managed security services and threat intelligence solutions.
INSPIRISYS
Inspirisys is an India-based public company founded in 1991 with 1,635 employees that provides IT services, consulting, and software development solutions.
Reasons to Buy this Report
- Market Size & Growth Validation : Quantified data confirming Canada's SOCaaS market at $577.5M (2024) and $1,128.7M (2029) provides credible benchmarks for investment decisions, competitive positioning, and revenue forecasting specific to the Canadian market.
- Sector-Specific Insights : Detailed analysis of adoption patterns across Canadian financial services, healthcare, and critical infrastructure sectors enables targeted go-to-market strategies and customer segmentation tailored to high-growth verticals.
- Regulatory Compliance Context : Understanding Canada-specific compliance drivers (PIPEDA, sector regulations) helps vendors and enterprises align SOCaaS solutions with local requirements, reducing implementation risks and accelerating market penetration.
- Competitive Landscape Intelligence : Comprehensive Canadian market data supports competitive analysis, pricing strategy development, and identification of market gaps, enabling informed decisions on product positioning and partnership opportunities.
- Strategic Planning & Forecasting : 11.8% CAGR projections through 2029 provide reliable forecasting data for budget allocation, expansion planning, and long-term strategic initiatives within the Canadian SOCaaS ecosystem.
Frequently asked questions
What is the current size of Canada's SOCaaS market?
Canada's SOC as a Service market was valued at $577.5 million in 2024 and is expected to grow to $1,128.7 million by 2029.
What is the projected growth rate for SOCaaS in Canada?
Canada's SOCaaS market is projected to grow at a compound annual growth rate (CAGR) of 11.8% from 2024 to 2029.
Which industries in Canada are driving SOCaaS adoption?
Financial services, healthcare, critical infrastructure, and technology sectors in Canada are primary drivers of SOCaaS adoption due to regulatory requirements and heightened security needs.
Why is Canada's SOCaaS market growing faster than global averages?
Canada's market growth is fueled by stringent data protection regulations, cross-border integration with U.S. markets, and increasing cyber threat sophistication targeting Canadian organizations.
What factors are influencing SOCaaS investment decisions in Canada?
Cost reduction, access to specialized security expertise, regulatory compliance, and the shift to cloud-based infrastructure are key factors driving Canadian enterprises to adopt SOCaaS solutions.
RESEARCH METHODOLOGY
Secondary research was conducted to gather information for this technical, market-oriented, and commercial study of the SOC-as-a-Service (SOCaaS) market. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Multiple approaches, including top-down and bottom-up methods, were used to estimate the total market size. After that, market breakup and data triangulation were used to estimate the market size of the segments and subsegments of the SOCaaS market.
Secondary Research
During the secondary research process, various secondary sources were consulted to identify and collect information relevant to the study. The secondary sources included annual reports, press releases, investor presentations from SOCaaS vendors, forums, certified publications, and whitepapers. The secondary research was primarily used to obtain key information about the industry’s supply chain, the total pool of key players, market classification and segmentation by industry trends down to the most granular level, regional markets, and key developments from both market- and technology-oriented perspectives. All of this information was further validated by primary sources.
Primary Research
In the primary research process, various primary sources from both the supply and demand sides were interviewed to obtain qualitative and quantitative information for this report. The primary sources from the supply side included industry experts such as chief executive officers (CEOs), vice presidents (VPs), marketing directors, technology and innovation directors, and other key executives from various companies and organizations operating in the SOCaaS market.
In the market engineering process, top-down and bottom-up approaches were extensively used, along with several data triangulation methods, to estimate and forecast the overall market segments and subsegments listed in this report. Extensive qualitative and quantitative analysis was conducted throughout the market engineering process to present key information and insights throughout the report.
After the complete market engineering process (including calculations for market statistics, market breakups, market size estimates, market forecasts, and data triangulation), extensive primary research was conducted to gather information and verify and validate the critical numbers arrived at. The primary research was also conducted to identify segmentation types, industry trends, the competitive landscape of SOCaaS market players, and key market dynamics, such as drivers, restraints, opportunities, challenges, and key strategies.
Following is the breakup of the primary study:
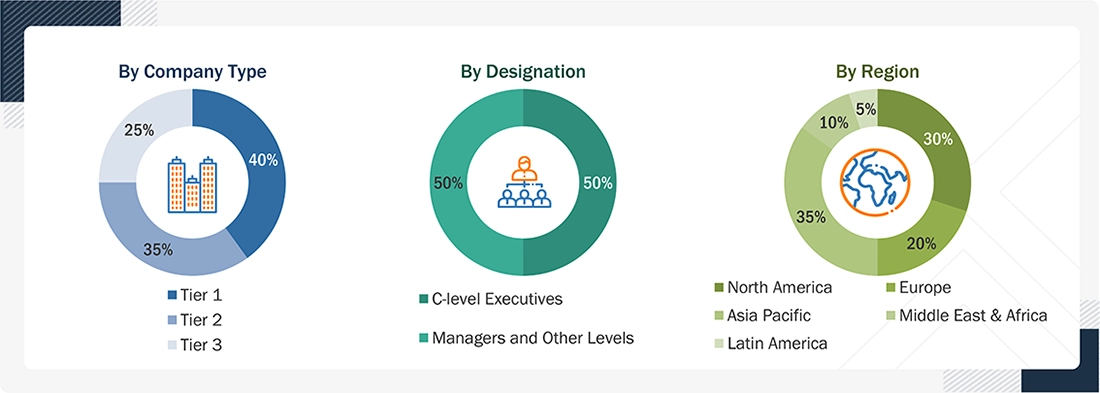
Note: Tier 1 companies have revenues above USD 10 billion; Tier 2 companies have revenues between USD 1 and 10 billion; and Tier 3 companies have revenues between USD 500 million and USD 1 billion. Other designations include sales, marketing, and product managers.
Source: Industry Experts
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
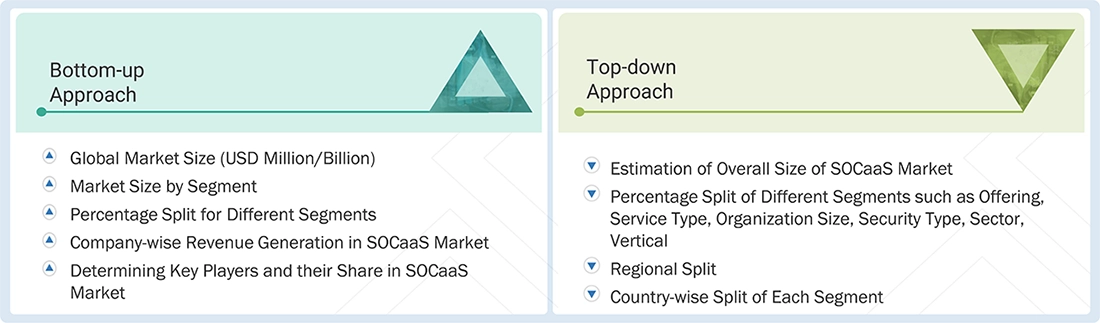
Top-down and bottom-up approaches were used to estimate and validate the size of the SOCaaS market and the sizes of various dependent sub-segments within the overall SOCaaS market. The research methodology used to estimate the market size includes the following details: critical players in the market were identified through secondary research, and their market shares in the respective regions were determined through primary and secondary research. This entire procedure involved studying the annual and financial reports of the top market players, and extensive interviews were conducted with key industry leaders, including CEOs, VPs, directors, and marketing executives, to gather valuable insights.
All percentage splits and breakdowns were determined using secondary sources and verified through primary sources. All possible parameters that affect the market covered in this research study were accounted for, examined in extensive detail, verified through primary research, and analyzed to produce the final quantitative and qualitative data. This data was consolidated and combined with detailed inputs and analysis from MarketsandMarkets.
SOC as a Service (SOCaaS) Market : Top-Down and Bottom-Up Approach
Source: MarketsandMarkets Analysis
Data Triangulation
The market was split into several segments and subsegments after arriving at the overall market size using the market size estimation processes explained above. The data triangulation and market breakup procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment. The data was triangulated by studying various factors and trends from both the demand and supply sides.
Market Definition
SOC-as-a-Service (SOCaaS) is a cloud-based, subscription-driven service that provides organizations with end-to-end cybersecurity capabilities. It delivers real-time threat detection, analysis, response, and monitoring without the need for an organization to build and manage an in-house security operations center (SOC).
Key Stakeholders
- Chief Technology and Data Officers
- Cybersecurity Software Vendors
- SOCaaS Providers
- SOC Providers
- Cybersecurity Service Providers
- Government Agencies
- Independent Software Vendors (ISVs)
- Consulting Firms
- System Integrators
- Value-added Resellers (VARs)
- IT Security Agencies
- Managed Security Service Providers (MSSPs)
Report Objectives
- To define, describe, and forecast the SOC-as-a-Service (SOCaaS) market based on offering, service type, organization size, security type, sector, vertical, and region
- To provide detailed information about the major factors, such as drivers, opportunities, restraints, and challenges, influencing the growth of the market
- To forecast the size of the market segments with respect to five main regions: North America, Europe, Asia Pacific, Middle East & Africa, and Latin America
- To analyze subsegments of the market with respect to individual growth trends, prospects, and contributions to the overall market
- To profile key players of the market and comprehensively analyze their market share and core competencies
- To analyze opportunities in the market for stakeholders and provide the competitive landscape details of major players
- To map competitive intelligence based on company profiles, key player strategies, and game-changing developments, such as product enhancements/launches, collaborations, and acquisitions
- To analyze competitive developments, such as product enhancements/launches, acquisitions, partnerships, and collaborations, in the SOCaaS market globally.
Customization Options
With the given market data, MarketsandMarkets offers customizations based on company-specific needs. The following customization options are available for the report:
Geographic Analysis
- Further breakdown of the Asia Pacific market by country, showing contributions to the regional market size.
- Further breakdown of the North American market into countries contributing to the rest of the regional market size.
- Further breakup of the Latin American market into countries contributing to the rest of the regional market size.
- Further breakup of the Middle East & African market into countries contributing to the rest of the regional market size.
- Further breakup of the European market into countries contributes to the rest of the regional market size.
Company information
- Detailed analysis and profiling of additional market players (up to 5)
Get the Full SOC as a Service (SOCaaS) Market Report
Full forecast, segment splits, and company analysis for all SOC as a Service (SOCaaS) Market.
- US SOC as a Service (SOCaaS) Market
- UK SOC as a Service (SOCaaS) Market
- Germany SOC as a Service (SOCaaS) Market
- France SOC as a Service (SOCaaS) Market
- Italy SOC as a Service (SOCaaS) Market
- Spain SOC as a Service (SOCaaS) Market
- Netherlands SOC as a Service (SOCaaS) Market
- China SOC as a Service (SOCaaS) Market
- Japan SOC as a Service (SOCaaS) Market
- India SOC as a Service (SOCaaS) Market
- Singapore SOC as a Service (SOCaaS) Market
- Brazil SOC as a Service (SOCaaS) Market
- Mexico SOC as a Service (SOCaaS) Market
- Rest Of Europe SOC as a Service (SOCaaS) Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
