North America Terminal Tractor Market (2026-2031)
The North America Terminal Tractor Market was valued at $833.1 Million in 2026 and projected to reach to $1136.9 Million by 2031, representing a compound annual growth rate of 4.5%. The North America terminal tractor market is positioned for steady growth through 2031, with the region's established port infrastructure and containerized cargo handling capabilities serving as key growth catalysts.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
North America Terminal Tractor Market Trends and Insights
- North America's terminal tractor sector is driven by robust port infrastructure expansion, increased containerized cargo volumes, and modernization of intermodal logistics networks across the region.
- In 2026, North America accounts for a significant share of global terminal tractor demand, supported by major shipping hubs in the United States, Canada, and Mexico. Growth in North America's terminal tractor market through 2031 is underpinned by rising e-commerce activity, supply chain optimization investments, and regulatory pressure for cleaner, more efficient yard equipment.
- North America's adoption of electric and autonomous terminal tractors is accelerating, with major ports investing in sustainable fleet upgrades.
- The region's competitive logistics environment and labor cost pressures are incentivizing terminal operators in North America to deploy advanced equipment that improves operational efficiency and reduces dwell times..
Key Market Statistics
- CAGR (2026-2031) 4.5% CAGR
- Market Size, 2026 ~USD 833.1 Million
- Forecast, 2031 ~USD 1136.9 Million
- Geography North America
North America Terminal Tractor Market Overview
Port Infrastructure Expansion :
North America's major ports including Los Angeles, Long Beach, and Vancouver are undergoing significant modernization and capacity expansion projects, driving increased demand for terminal tractors to handle growing containerized cargo volumes.
Intermodal Logistics Growth :
The region's robust intermodal network connecting ports, rail yards, and distribution centers is accelerating terminal tractor adoption as logistics operators optimize last-mile connectivity and reduce dwell times.
US Market Dominance :
The United States represents the largest market segment within North America at $5,343 million, driven by extensive port operations, e-commerce fulfillment demands, and containerized trade volumes with Asia-Pacific partners.
Regional Trade Dynamics :
USMCA trade agreements and cross-border logistics between the US, Canada, and Mexico are fueling terminal tractor demand across the region's integrated supply chain networks.
North America Terminal Tractor Market Dynamics
- The market's 4.5% CAGR reflects strong demand from major logistics hubs and intermodal operators modernizing their fleets to improve operational efficiency and reduce emissions.
- Investments in port automation and supply chain digitalization are expected to drive terminal tractor adoption across the region. Key growth drivers include increased containerized trade volumes, expansion of inland port facilities, and the shift toward more efficient intermodal logistics networks.
- North America's mature transportation infrastructure and high capital investment capacity position the region favorably for terminal tractor market expansion, though growth rates remain moderate compared to emerging markets.
- Strategic focus on fleet modernization and sustainability initiatives will continue to support market development through 2031..
Market Ecosystem
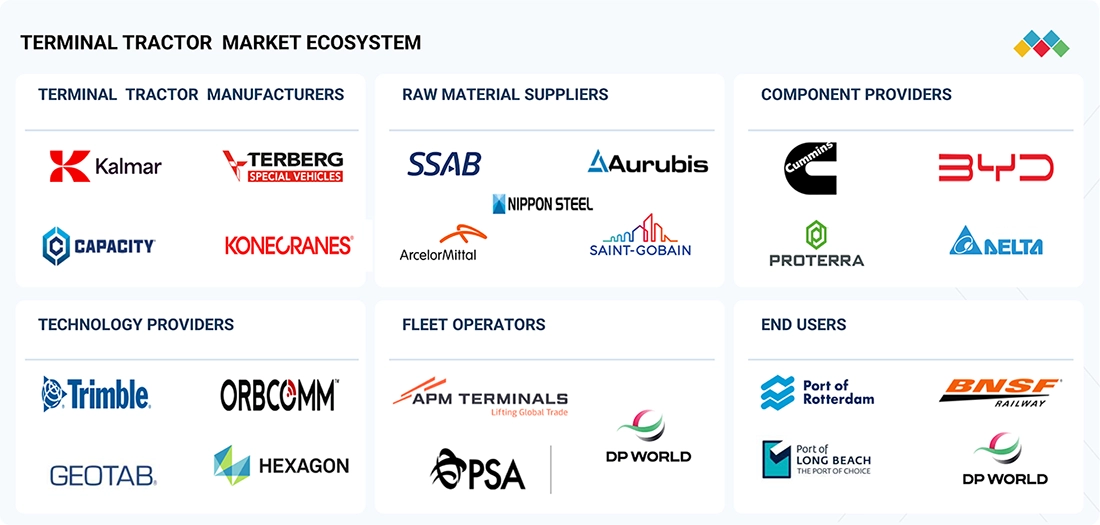
TERMINAL TRACTOR MARKET SIZE, SHARE & ANALYSIS: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Provides diesel, electric, and automation ready terminal tractors for container ports, intermodal terminals, distribution centers, warehouses, and RoRo operations. The TT and Ottawa product portfolio supports trailer shunting, container movement, and high frequency yard operations, while Kalmar Insight enables fleet monitoring and predictive maintenance.. | Improves trailer turnaround time | Increases fleet utilization, supports zero-emission yard operations | Reduces maintenance downtime through connected fleet management | Enhances terminal productivity and operational efficiency |
 |
Offers electric and automation compatible terminal tractors integrated with the company's Port Solutions portfolio for container terminals, intermodal facilities, and logistics operations. The solutions are designed to operate alongside automated cranes, digital terminal systems, and connected yard equipment. | Supports integrated port automation | Improves cargo handling efficiency | Enhances fleet connectivity | Reduces emissions | Increases operational reliability through lifecycle service and digital maintenance solutions |
 |
Supplies diesel, electric, and semi autonomous terminal tractors for ports, logistics hubs, industrial facilities, airports, and RoRo terminals. The YT Series supports intensive trailer movement, heavy duty yard operations, and multi shift logistics applications, with Terberg Connect providing remote diagnostics and fleet management capabilities. | Enables continuous heavy-duty operations | Reduces operating costs | Improves equipment availability through predictive maintenance | Supports fleet electrification | Enhances operator productivity and safety |
 |
Provides highly customizable tow tractors, platform trucks, and terminal transport solutions for warehouses, manufacturing facilities, airports, automotive plants, and logistics centers. The product portfolio includes electric and fuel cell powered industrial vehicles tailored to demanding internal transport operations. | Improves internal material flow | Increases operator safety and comfort | Reduces emissions through electric and hydrogen technologies | Enhances productivity | Lowers total operating costs across industrial logistics applications |
 |
Specializes in terminal tractors for ports, intermodal rail yards, warehouses, distribution centers, and industrial logistics operations. The product portfolio includes diesel, LPG, battery electric, and hydrogen ready terminal tractors designed for intensive trailer spotting and yard management, with enhanced operator ergonomics and advanced safety systems. | Delivers reliable trailer handling in demanding yard operations | Reduces fuel and maintenance costs through alternative fuel technologies | Improves driver comfort and safety | Increases fleet uptime | Supports fleet modernization and sustainability initiatives |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Electric Hybrid Vehicles
- Battery Electric Vehicle (BEV)
- Fuel Cell Electric Vehicle (FCEV)
- Light Commercial Vehicles (LCVs)
- Hybrid Electric Vehicle (HEV)
- Agricultural Tractors
- Visteon Corporation
- BOSCH LIMITED
- Byd company ltd.
- Tesla, Inc.
- FORD MOTOR COMPANY
Logistics And Transportation
- Internal Combustion Engine (ICE)
- Crawler Excavator
- Fuel Cell
- Light Commercial Vehicles (LCVs)
- Sensors
- Siemens ag
- Alstom s.a.
- Hitachi, Ltd.
- Godrej Industries Limited
- Toshiba Corporation
On Highway Off Highway Vehicles
- Internal Combustion Engine (ICE)
- Agricultural Tractors
- Crawler Excavator
- Battery Electric Vehicle (BEV)
- Excavators
- Visteon Corporation
- Deere & Company
- AB VOLVO PENTA
- Honda Motor Co., Ltd.
- LIEBHERR-INTERNATIONAL AG
Key Takeaways
- North America's terminal tractor market will expand from $833.1M (2026) to $1,136.9M (2031) at a 4.5% CAGR.
- North America's major ports are investing heavily in electric and autonomous terminal tractor fleets to meet environmental regulations.
- E-commerce growth and supply chain digitalization are driving increased demand for efficient terminal tractors across North America.
- North America's terminal tractor market is characterized by consolidation among equipment manufacturers and rising adoption of telematics and IoT solutions.
Terminal Tractor Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | LITHIUM IRON PHOSPHATE (LFP) (Battery Chemistry) |
| Forecast Period | 2026-2031 |
| Growth Rate | CAGR of 5.4% from 2026 to 2031 |
| Largest Segment | 4X2 (Drive) |
| Market Size Base Year (Billions) | ~USD 1.65 (2026) |
| Revenue Forecast (Billions) | ~USD 2.15 (2031) |
| Segments Covered | Type, Application, Drive, Propulsion, Tonnage, Logistics Industry, Motor Power Output, Battery Chemistry |
North America Terminal Tractor Market Report Segmentation
8 segment dimensions are covered across the global market.
By Type
- Automated
- Manual
By Application
- Airport
- Airports
- Marine Ports
- Oil & Gas
- Warehouse & Logistics
By Drive
- 4X2
- 4X4
- 6X4
By Propulsion
- Cng/Lng
- Diesel
- Electric
By Tonnage
- 50-100 Tons
- <50 Tons
- >100 Tons
By Logistics Industry
- Food & Beverages
- Inland Waterways & Marine Service
- Inland Waterways & Marine Services
- Rail Logistics
- Retail
- Roro
By Motor Power Output
- 150-250 Kw
- <150 Kw
- >250 Kw
By Battery Chemistry
- Lithium Iron Phosphate (Lfp)
- Nickel Manganese Cobalt (Nmc)
Target Audience
- Port Operators & Terminal Managers : Need market data to justify capital expenditures on terminal tractor fleets, optimize equipment utilization across North American ports, and plan modernization initiatives aligned with cargo volume growth.
- Logistics & Intermodal Companies : Require regional market insights to make informed fleet acquisition decisions, assess competitive positioning within North America's intermodal networks, and identify growth opportunities in containerized cargo handling.
- Equipment Manufacturers & Suppliers : Need North America-specific demand forecasts and market segmentation to guide product development, sales strategies, and distribution planning across the US, Canada, and Mexico markets.
- Investment & Private Equity Firms : Seek detailed market valuations and growth projections for North America to evaluate acquisition targets, assess portfolio company performance, and identify emerging opportunities in the terminal equipment sector.
- Transportation & Supply Chain Consultants : Require authoritative regional market data to support client advisory services, benchmark operational performance, and develop strategic recommendations for logistics optimization across North America.
Countries within North America - compare and drill down
| Country | 2025 size (native) |
|---|---|
| US | USD 5343 Million |
| Canada | USD 453 Million |
| Mexico | USD 557 Million |
Country market size visualization
Reasons to Buy this Report
- Market Size & Growth Trajectory : Access precise valuation data for North America's terminal tractor market ($833.1M in 2026 growing to $1,136.9M by 2031), enabling accurate financial forecasting and investment planning specific to the region.
- Country-Level Breakdown : Detailed market segmentation across US, Canada, and Mexico allows buyers to identify high-opportunity markets and tailor regional strategies based on localized demand patterns and port infrastructure development.
- Port & Logistics Insights : Comprehensive analysis of North America's port expansion initiatives, intermodal network growth, and containerized cargo trends provides actionable intelligence for fleet operators and equipment manufacturers.
- Competitive Positioning : Benchmark your North America operations against regional market dynamics and understand how the 4.5% CAGR compares to global growth rates, informing strategic expansion and product development decisions.
- Trade & Supply Chain Context : Understand how USMCA trade agreements, cross-border logistics, and integrated supply chains impact terminal tractor demand across North America's interconnected transportation networks.
Frequently asked questions
What is the current size of the North America terminal tractor market?
In 2026, the North America terminal tractor market is valued at $833.1 million and is expected to reach $1,136.9 million by 2031.
What is the projected growth rate for North America's terminal tractor market?
North America's terminal tractor market is projected to grow at a compound annual growth rate (CAGR) of 4.5% from 2026 to 2031.
Which factors are driving growth in North America's terminal tractor market?
Key drivers include port infrastructure expansion, increased containerized cargo volumes, e-commerce growth, supply chain modernization, and regulatory mandates for sustainable equipment in North America.
What role do electric and autonomous terminal tractors play in North America's market?
North America's major ports are increasingly adopting electric and autonomous terminal tractors to comply with environmental regulations, reduce operational costs, and improve efficiency through 2031.
How does North America's terminal tractor market compare to global trends?
North America's 4.5% CAGR is slightly below the global average of 5.4%, reflecting the region's mature market dynamics and higher baseline adoption rates compared to emerging markets.
RESEARCH METHODOLOGY
The research study involved extensive use of secondary sources, such as company annual reports/presentations, industry association publications, automotive magazine articles, directories, technical handbooks, the World Economic Outlook, trade websites, technical articles, and databases, to identify and collect information on the terminal tractor market. Primary interviews were conducted to obtain and verify critical qualitative and quantitative information, as well as assess the prospects of the industry. Primary sources include experts from core and related industries, suppliers, manufacturers, distributors, service providers, technology developers, and organizations related to various segments of the market value chain. Detailed interviews were conducted with various primary respondents that include key industry participants, subject-matter experts, C-level executives of key market players, and industry consultants.
Secondary Research
Secondary sources referred to in this research study include the Port Equipment Manufacturers Association (PEMA), Industrial Truck Association, Container Dealers Association (CDA), and Container Owners Association (COA); corporate filings (such as annual reports, investor presentations, and financial statements); and trade, business, and terminal tractor associations. The secondary data was collected and analyzed to arrive at the overall market size, which was further validated by primary research.
Primary Research
Extensive primary research was conducted after acquiring an understanding of the terminal tractor market scenario through secondary research. Several primary interviews were conducted with market experts from terminal tractor providers, component/system providers, and end user organizations across three major regions, namely, North America, Europe, and Asia Pacific. Approximately 90% of the primary interviews were conducted with the terminal tractor manufacturers and component/system providers, and 10% with the end user organizations. Primary data was collected through questionnaires, emails, and telephonic interviews. Various departments within organizations, including sales, operations, and administration, were contacted to provide a holistic viewpoint in the report while canvassing primary sources.
Primary interviews were conducted to gather insights, including market sizing estimation and forecast, future trends, and upcoming technologies in the market. Data triangulation of all these points was done using the information gathered from secondary research and model mapping. Stakeholders from the demand and supply sides were interviewed to understand their views on the aforementioned points.
Breakdown of Primaries
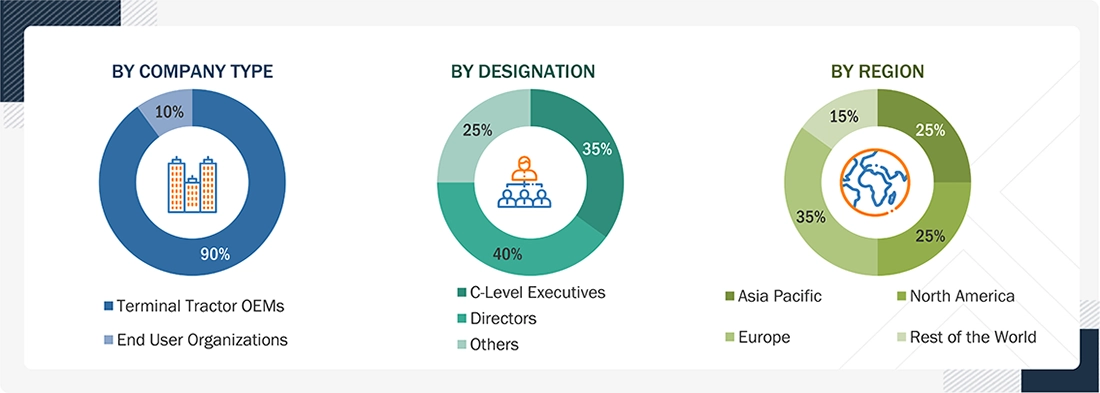
Note: Tiers of companies are based on the supply chain of the terminal tractor market; companies’ revenues have not been considered.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
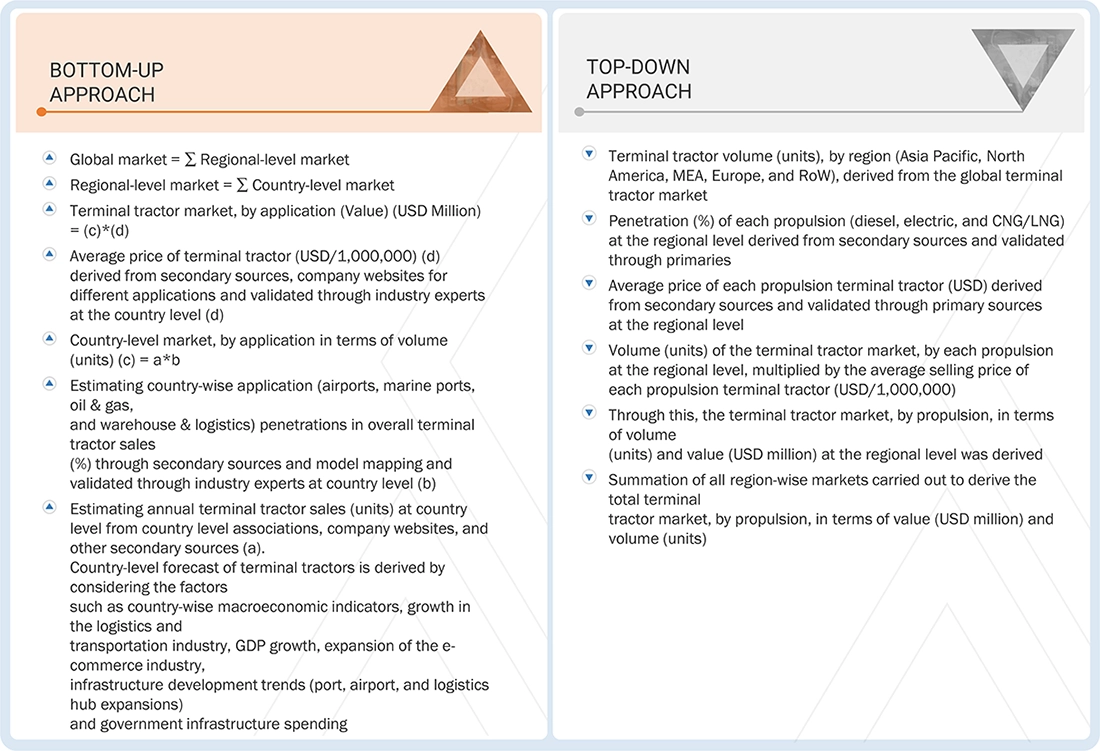
Both top-down and bottom-up approaches were used to estimate and validate the total size of the terminal tractor market. These methods were also used extensively to estimate the size of various subsegments in the market.
Bottom-up Approach: Estimating annual terminal tractor sales (units) at country level from various secondary sources, such as terminal tractor manufacturing associations, company annual reports, and investor presentations. Country-level forecast of terminal tractors is derived by considering factors such as country-wise macroeconomic indicators, growth in the logistics and transportation industry, GDP growth, expansion of the e-commerce industry, infrastructure development trends (port, airport, and logistics hub expansions), and government infrastructure spending.
Estimating country-wise application (airports, marine ports, oil & gas, and warehouse & logistics) penetrations in overall terminal tractor sales (%) through secondary sources and validated through industry experts at the country level. To get the terminal tractor market in terms of volume (units) by application, country-level sales of terminal tractors are multiplied by penetration of various applications (airports, marine ports, oil & gas, and warehouse & logistics).
Country-level ASP of terminal tractors used in various applications (airports, marine ports, oil & gas, and warehouse & logistics) was derived through various secondary sources and validated from industry experts. The country-level market based on application by volume was multiplied by the country-level average selling price (ASP) for each application to get the market for each application by value.
The summation of the country-level market would give the regional level, with further addition providing the global market by application (warehouse & logistics, marine port, airport, and oil & gas). The total value of each country has then been summed up to derive the total value of the market by application. All key macro indicators affecting the revenue growth of the market segments and subsegments were accounted for, viewed in extensive detail, verified through primary research, and analyzed to get the validated and verified quantitative and qualitative data.
Top-down Approach: The top-down approach was used to estimate and validate the market by propulsion in terms of volume and value. The terminal tractor market volume (units) and value (USD million) by region
(Asia Pacific, North America, the Middle East & Africa, Europe, and the Rest of the World) were derived from the global market.
The penetration of each propulsion (diesel, electric, and CNG/LNG) at the regional level and forecast was derived from secondary sources and validated through primaries.
The penetration of each propulsion (diesel, electric, and CNG/LNG) was multiplied by the regional market to get the market volume (units) and value (USD million) by propulsion for each region.
A summation of all region-wise markets was carried out to derive the total terminal tractor market volume (units) and value (USD million) by propulsion. The top-down approach was followed by drive, type, tonnage, and logistics by industry segments.
- Key players in the global market were identified through secondary research, and their global market shares were determined through primary and secondary research.
- The research methodology included the study of the annual and quarterly financial reports & regulatory filings of major market players as well as interviews with industry experts for detailed market insights.
- All major penetration rates, percentage shares, splits, and breakdowns for the global market were determined by using secondary sources and verified through primary sources.
- All key macroindicators affecting the revenue growth of the market segments and subsegments were accounted for, viewed in extensive detail, verified through primary research, and analyzed to get the validated and verified quantitative & qualitative data.
- The market data gathered was consolidated and added with detailed inputs, analyzed, and presented in this report.
Terminal Tractor Market : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall size of the terminal tractor market through the above-mentioned methodology, the market was split into several segments and subsegments. The data triangulation and market breakdown procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact data of the market by volume and value for the key segments and subsegments. The extrapolated market data was triangulated by studying various macro indicators and regional trends from both the supply and demand sides.
Market Definition
A terminal tractor is a specialized vehicle designed for the short-distance movement and positioning of semitrailers, container chassis, and other trailers within confined operating facilities. For this study, the terminal tractor market includes vehicles used across warehouse and logistics facilities, marine ports, airports, and oil and gas facilities. The equipment considered includes manual and automated terminal tractors with 4x2, 4x4, and 6x4 drive configurations, powered by diesel, electric, CNG/LNG, and hydrogen propulsion systems.
Key Stakeholders
- Terminal Tractor & Port Equipment Manufacturers
- Battery and Other Component Suppliers for Electric Terminal Tractors
- Tier I/II Component Suppliers
- Port Operators
- Container Handling Equipment Traders and Distributors
- Manufacturing Associations (North American Council for Freight Efficiency, American Trucking Associations, and Others)
Report Objectives
-
To define, describe, and forecast the size of the terminal tractor market, in terms of volume and value, for the following categories:
- By Type (Manual, Automated)
- By Application (Warehouse & Logistics, Marine Port, Airport, Oil & Gas)
- By Drive (4x2, 4x4, 6x4)
- By Propulsion (Diesel, Electric, CNG/LNG)
- By tonnage (< 50 Tons, 50–100 Tons, > 100 Tons)
- By End Use (Retail, Food & Beverages, Inland Waterways & Marine Service, Rail Logistics, RoRo)
- Electric Terminal Tractor Market, By Motor Power Output (<150 kW, 150–250 kW, >250 kW)
- Electric Terminal Tractor Market, By Battery Chemistry (LFP, NMC, Others)
- By Region (Asia Pacific, North America, Middle East & Africa [MEA], Europe, Rest of the World [RoW])
- To understand the dynamics (Drivers, Restraints, Opportunities, and Challenges) of the market
- To analyze the market share analysis/ranking of key players operating in the terminal tractor market.
- To study the market with supply chain analysis, ecosystem analysis, trade analysis, case study analysis, pricing analysis, patent analysis, trends/disruptions impacting buyers, technology analysis and regulatory analysis
- To analyze the competitive landscape, prepare a company evaluation matrix for the players operating in the global market, evaluate the share/ranking based on product footprints of leading market players, and position them on the quadrant.
- To analyze the recent developments, including product launches, deals, expansions, and other developments, carried out by the key participants in the market.
- To analyze recent developments, including supply contracts, product launches, expansion, and other activities undertaken by key industry participants in the market
-
To study the following with respect to the market
- Trends/Disruptions Impacting Customer Business
- Ecosystem Analysis
- Technology Analysis
- Supply Chain Analysis
- Patent Analysis
- Regulatory Landscape
- Case Study Analysis
- Key Stakeholders and Buying Criteria
- Key Conferences and Events
- Trade Analysis
- Pricing Analysis
- Impact of AI/Gen AI
- Impact of EU-FTA Trade Deal
- Impact of the Israel-Iran War
Available customizations:
Along with the given market data, MarketsandMarkets offers customizations in accordance with a company’s specific needs. The following customization options are available:
- Terminal tractor market, by propulsion country
- Terminal tractor vs. body carriers market, by country
Get the Full Terminal Tractor Market Report
Full forecast, segment splits, and company analysis for all Terminal Tractor Market.
- China Terminal Tractor Market
- Japan Terminal Tractor Market
- South Korea Terminal Tractor Market
- India Terminal Tractor Market
- Germany Terminal Tractor Market
- France Terminal Tractor Market
- UK Terminal Tractor Market
- Spain Terminal Tractor Market
- Russia Terminal Tractor Market
- Mexico Terminal Tractor Market
- Canada Terminal Tractor Market
- UAE Terminal Tractor Market
- Saudi Arabia Terminal Tractor Market
- South Africa Terminal Tractor Market
- Brazil Terminal Tractor Market
- Chile Terminal Tractor Market
- Argentina Terminal Tractor Market
- US Terminal Tractor Market
- Rest Of Europe Terminal Tractor Market
- Rest Of Asia Pacific Terminal Tractor Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report