Europe Top 10 Medical Device Technologies Market (2022-2027)
The Europe Top 10 Medical Device Technologies Market was valued at $122318 Million in 2022 and projected to reach to $158123.7 Million by 2027, representing a compound annual growth rate of 5.3%. Europe's medical device technologies market is poised for sustained expansion through 2027, supported by robust healthcare infrastructure, favorable reimbursement policies, and significant R&D investments across the region.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Europe Top 10 Medical Device Technologies Market Trends and Insights
- In 2022, Europe's market was valued at $122.3 billion USD, reflecting the region's strong healthcare infrastructure and regulatory framework.
- Europe is expected to expand to $158.1 billion USD by 2027, driven by aging demographics, increased healthcare spending, and technological innovation across the continent. The European market benefits from advanced manufacturing capabilities and stringent quality standards that position Europe as a leader in medical device innovation.
- Europe's growth trajectory at 5.3% CAGR through 2027 reflects steady demand for cutting-edge diagnostic, therapeutic, and monitoring technologies.
- Key drivers in Europe include rising chronic disease prevalence, digital health adoption, and investment in precision medicine across member states..
Key Market Statistics
- CAGR (2022-2027) 5.3% CAGR
- Market Size, 2022 ~USD 122318 Million
- Forecast, 2027 ~USD 158123.7 Million
- Geography Europe
Europe Top 10 Medical Device Technologies Market Overview
Market Valuation :
Europe's top 10 medical device technologies market reached $122.3 billion USD in 2022, representing one of the world's most mature and well-established healthcare device markets with strong purchasing power.
Projected Growth :
The European market is forecasted to grow to $158.1 billion USD by 2027, representing a compound annual growth rate of 5.3%, driven by aging populations and increased healthcare expenditure across the region.
Regulatory Leadership :
Europe maintains stringent regulatory frameworks through the CE marking and MDR compliance, ensuring high-quality medical device standards that drive innovation and market confidence among healthcare providers.
Demographic Drivers :
An aging European population combined with rising chronic disease prevalence is accelerating demand for advanced medical technologies, positioning the region as a key growth engine for device manufacturers.
Europe Top 10 Medical Device Technologies Market Dynamics
- The aging demographic profile of European nations is creating heightened demand for diagnostic, therapeutic, and monitoring devices.
- Germany, France, Italy, and Spain represent the largest markets, while emerging healthcare needs in Central and Eastern Europe present additional growth opportunities.
- Regulatory harmonization and digital health integration are expected to accelerate market penetration and innovation cycles..
Market Ecosystem
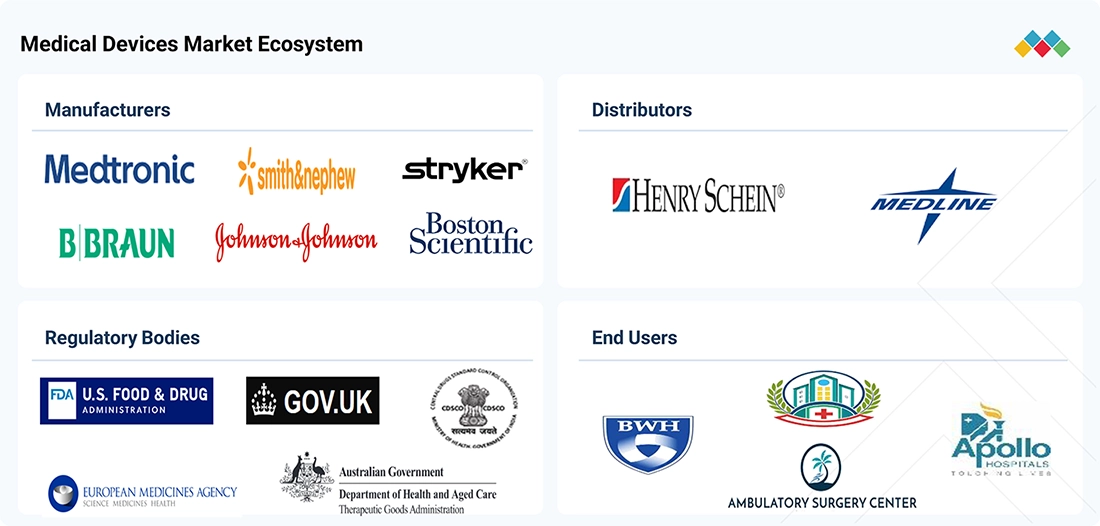
MEDICAL DEVICES MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Provides a broad portfolio of cardiovascular, neuroscience, medical surgical, diabetes, and patient monitoring devices used across hospitals, ambulatory surgery centers, specialty clinics, and home healthcare | Integrates AI-enabled technologies, digital health platforms, and minimally invasive solutions to support complex clinical workflows globally. | Improves clinical outcomes through advanced therapeutic technologies, enhances procedural efficiency, supports remote patient management, reduces hospital stay durations, and enables standardized care delivery across diverse healthcare settings worldwide. |
 |
Delivers orthopedic, cardiovascular, surgical, wound management, and vision care devices used in acute care hospitals, specialty centers, ambulatory surgery centers, and ophthalmology clinics | Combines advanced instrumentation, digital surgery technologies, and minimally invasive solutions to optimize surgical care globally. | Enhances surgical precision, improves patient safety, supports faster recovery, streamlines operating room workflows, and enables consistent clinical performance across multiple healthcare specialties and care environments. |
 |
Offers infusion therapy systems, surgical instruments, dialysis equipment, vascular access devices, anesthesia products, and infection prevention solutions for hospitals, dialysis centers, intensive care units, and outpatient facilities worldwide | Designed for seamless integration into modern healthcare infrastructure. | Improves patient safety through standardized therapy delivery, enhances treatment reliability, supports infection prevention initiatives, optimizes clinical workflows, and increases operational efficiency across healthcare institutions. |
 |
Provides orthopedic implants, surgical equipment, neurotechnology systems, medical beds, emergency care products, and robotic-assisted surgical platforms used across hospitals, trauma centers, orthopedic clinics, and ambulatory surgery centers globally | Integrates robotics, navigation, and smart operating room technologies. | Improves procedural accuracy, enhances surgical planning and workflow efficiency, supports minimally invasive procedures, shortens recovery times, and strengthens hospital productivity through advanced digital and robotic technologies. |
 |
Supplies orthopedic reconstruction systems, sports medicine devices, advanced wound management products, ENT technologies, and robotic-assisted surgical platforms for hospitals, wound care centers, orthopedic clinics, and ambulatory surgery centers worldwide | Focuses on minimally invasive and digital surgical solutions. | Accelerates wound healing, improves joint restoration outcomes, enhances surgical precision, supports faster patient rehabilitation, and increases procedural consistency through innovative technologies and integrated care solutions across healthcare networks. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Medical Devices
- Polymerase Chain Reaction (PCR)
- Magnetic Resonance Imaging (MRI)
- Disposable Autoinjectors
- Pulse Oximeters
- Blood Pressure Monitors
- Medtronic plc
- Abbott Laboratories
- Stryker Corporation
- Becton, Dickinson and Company
- CONMED Corporation
Key Takeaways
- Europe's medical device technologies market reached $122.3 billion in 2022 and is forecast to grow to $158.1 billion by 2027.
- Europe maintains a 5.3% compound annual growth rate, reflecting robust healthcare investment and regulatory excellence across the region.
- Europe's aging population and chronic disease burden are primary catalysts for sustained demand in medical device technologies through 2027.
- Europe's advanced manufacturing ecosystem and stringent quality standards position the region as a global leader in medical device innovation.
Top 10 Medical Device Technologies Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2022 |
| Fastest Growing Segment | PROSTHETIC DEVICES (Type) |
| Forecast Period | 2022-2027 |
| Growth Rate | CAGR of 5.7% from 2022 to 2027 |
| Largest Segment | IMMUNOASSAY/IMMUNOCHEMISTRY (Technology) |
| Market Size Base Year (Billions) | ~USD 437.7 (2022) |
| Revenue Forecast (Billions) | ~USD 577.5 (2027) |
| Segments Covered | Technology, Type |
Europe Top 10 Medical Device Technologies Market Report Segmentation
2 segment dimensions are covered across the global market.
By Technology
- Clinical Chemistry
- Coagulation And Hemostasis
- Hematology
- Immunoassay/Immunochemistry
- Microbiology
- Molecular Diagnostics
- Other Ivd Technologies
- Urinalysis
By Type
- Advanced Wound Care Devices
- Anesthesia Devices
- Anesthesia Disposables
- Anesthesia Machines
- Arthroscopic Devices
- Blood Glucose Monitoring Systems
- Camera Heads
- Capnographs
- Capsule Endoscopes
- Cardiac Rhythm Management Devices
- Cardiology Devices
- Cardiovascular Monitoring Devices
- Carts
- Cataract Surgery Devices
- Clinical Chemistry
- Coagulation And Hemostasis
- Computed Tomography Scanners
- Diabetes Care Devices
- Diabetes Management Mobile Applications
- Diagnostic Imaging Devices
- Disposable Endoscopes
- Disposable Oxygen Masks
- Electronic Endoscopy Equipment
- Electrophysiology Devices
- Endoscopes
- Endoscopic Accessories
- Endoscopic Light Sources
- Endoscopy Accessories
- Endoscopy Devices
- Flexible Endoscopes
- Glaucoma Surgery Devices
- Hematology
- Hemodialysis Consumables/Supplies
- Hemodialysis Machines
- Hemodialysis Products
- Humidifiers
- Immunoassay /Immunochemistry
- Immunoassay/ Immunochemistry
- Immunoassay/Immunochemistry
- In Vitro Diagnostics (Ivd)
- Insulin Delivery Devices
- Interventional Cardiology Devices
- Joint Reconstruction Devices
- Kidney/Dialysis Devices
- Mammography Systems
- Mechanical Endoscopy Equipment
- Microbiology
- Molecular Diagnostics
- Mri Systems
- Nebulizers
- Nuclear Imaging Equipment
- Ophthalmic Diagnostic And Monitoring Devices
- Ophthalmology Devices
- Orthobiologics
- Orthopedic Accessories
- Orthopedic Braces And Supports
- Orthopedic Devices
- Other Endoscopy Devices
- Other Ivd Technologies
- Other Peritoneal Dialysis Products
- Other Technologies
- Other Visualization Equipment
- Oxygen Cannulas
- Oxygen Concentrators
- Peak Flow Meters
- Peripheral Vascular Devices
- Peritoneal Dialysis Catheters
- Peritoneal Dialysis Concentrates/Dialysates
- Peritoneal Dialysis Machines
- Peritoneal Dialysis Products
- Peritoneal Dialysis Transfer Sets
- Positive Airway Pressure Devices
- Prosthetic Devices
- Pulse Oximetry Systems
- Refractive Surgery Devices
- Respiratory Care And Anesthesia Devices
- Respiratory Care Devices
- Respiratory Devices
- Respiratory Disposables
- Respiratory Inhalers
- Respiratory Measurement Devices
- Resuscitators
- Reusable Resuscitators
- Rigid Endoscopes
- Robot-Assisted Endoscopes
- Spinal Surgery Devices
- Spirometers
- Surgical Wound Care Devices
- Tracheostomy Tubes
- Traditional Wound Care Devices
- Transmitters And Receivers
- Trauma Fixation Products
- Ultrasound Systems
- Urinalysis
- Ventilators
- Video Converters
- Video Processors
- Video Recorders
- Vision Care Devices
- Visualization Equipment
- Vitreoretinal Surgery Devices
- Wireless Displays And Monitors
- Wound Care Devices
- X-Ray Systems
Target Audience
- Medical Device Manufacturers : Strategic planning and market entry decisions require comprehensive understanding of Europe's $122.3B market size, growth trajectory, and country-specific opportunities to optimize product launches and distribution.
- Healthcare Investors & PE Firms : Investment thesis development and portfolio company valuations depend on accurate European market sizing, 5.3% CAGR projections, and regional growth drivers to assess return potential.
- Hospital & Healthcare Systems : Procurement and technology adoption strategies benefit from market intelligence on emerging device technologies, competitive offerings, and cost-effectiveness data across European healthcare networks.
- Regulatory & Compliance Officers : Understanding regional regulatory requirements, CE marking standards, and MDR compliance across European markets is essential for product certification and market authorization strategies.
- Market Research & Consulting Firms : Client deliverables and competitive intelligence reports require validated European market data, country-level analysis, and technology trend forecasts to support strategic consulting engagements.
Countries within Europe - compare and drill down
| Country | 2025 size (native) |
|---|---|
| Germany | USD 7508.1 Million |
| France | USD 5626.8 Million |
| UK | USD 3211.8 Million |
| Italy | USD 4639.6 Million |
| Spain | USD 3877.3 Million |
| Rest Of Europe | USD 35748.6 Million |
Country market size visualization
Reasons to Buy this Report
- Regional Market Segmentation : Gain detailed insights into Europe's $122.3 billion market with country-level breakdowns for Germany, France, UK, Italy, Spain, and Rest of Europe to identify high-potential markets for device deployment.
- Competitive Positioning : Understand Europe's regulatory landscape, reimbursement structures, and competitive dynamics to develop effective market entry and expansion strategies tailored to regional healthcare systems.
- Growth Forecasting : Access 5-year projections through 2027 with 5.3% CAGR analysis to support strategic planning, investment decisions, and resource allocation for European market operations.
- Demographic Insights : Leverage data on aging populations and chronic disease prevalence across European nations to identify emerging device categories and unmet clinical needs driving market expansion.
- Technology Trends : Discover the top 10 medical device technologies gaining traction in Europe, including adoption rates, clinical applications, and innovation pipelines shaping the region's healthcare future.
Frequently asked questions
What was Europe's medical device technologies market size in 2022?
Europe's market was valued at $122.3 billion USD in 2022, representing a significant portion of global medical device technology demand.
What is the projected market size for Europe by 2027?
Europe's medical device technologies market is forecast to reach $158.1 billion USD by 2027, reflecting continued regional growth.
What is Europe's CAGR for medical device technologies?
Europe's market is growing at a compound annual growth rate of 5.3% from 2022 to 2027.
What factors are driving growth in Europe's medical device market?
Europe's growth is driven by aging demographics, increased healthcare expenditure, digital health adoption, and investment in precision medicine technologies.
How does Europe's growth compare to global trends?
Europe's 5.3% CAGR is slightly below the global average of 5.7%, reflecting mature market dynamics and regulatory maturity across the region.
RESEARCH METHODOLOGY
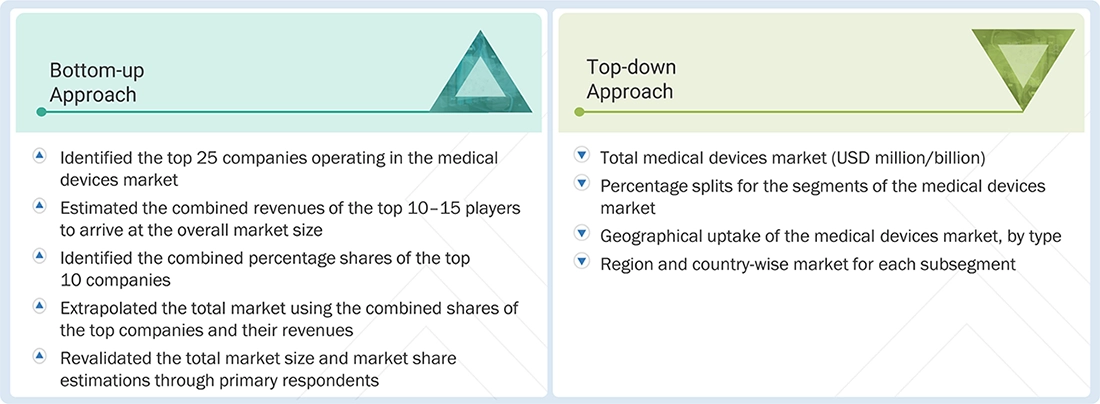
The research study aimed to estimate the current size of the medical devices market through several key activities. Comprehensive secondary research was conducted to gather information on the industry. The next step involved validating these findings, assumptions, and size estimates with industry experts across the value chain through primary research. To estimate the total market size, both top-down and bottom-up approaches were utilized. Following this, market segmentation and data triangulation procedures were employed to determine the sizes of different segments and subsegments within the medical devices market.
Secondary Research
The secondary research process involved the widespread use of secondary sources, directories, databases (such as Bloomberg Businessweek, Factiva, and D&B Hoovers), white papers, annual reports, investor presentations, SEC filings of companies and publications from government sources, such as National Institutes of Health (NIH), US FDA, US Census Bureau, World Health Organization (WHO), International Trade Administration (ITA), Global Burden of Disease Study, and Centers for Medicare and Medicaid Services (CMS) were referred to in order to identify and collect information for the global medical devices market study. It was also used to obtain important information on key players, market classification & segmentation aligned with industry trends, and key developments from market and technology perspectives, down to the bottom-most level. A database of the key industry leaders was also prepared using secondary research.
Primary Research
In the primary research process, various sources from both the supply and demand sides were interviewed to obtain qualitative and quantitative information for this report. The primary sources on the supply side include industry experts, such as CEOs, vice presidents, marketing and sales directors, technology & innovation directors, and other key executives from leading companies and organizations in the medical devices market. The primary demand-side sources include ambulatory surgical centers, hospitals, clinics, and other end users. Primary research was conducted to validate the market segmentation, identify key players and gather insights into key industry trends & key market dynamics.
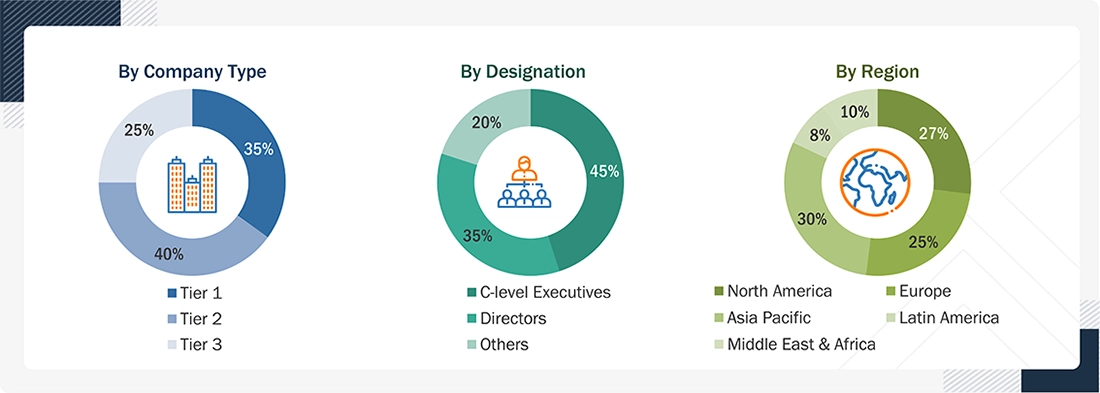
Note 1: C-level executives include CEOs, CFOs, COOs, and VPs.
Note 2: Others include sales managers, marketing managers, business development managers, product managers, distributors, and suppliers.
Note 3: Companies are classified into tiers based on their total revenue. The tiers are as follows:
Tier 1 = > USD 10 billion, Tier 2 = USD 1 billion to USD 10 billion, and Tier 3 = <USD 1 billion
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
For the global market value, annual revenue figures were calculated using revenue mappings of major product manufacturers and OEMs active in the medical devices market. All major product manufacturers were identified at the global/or country or regional level. Revenue mapping for respective business segments/subsegments was done for the major players. Also, the medical devices market was split into various segments and subsegments:
- List of major players operating in the products market at the regional and/or country level
- Product mapping of various medical device manufacturers at the regional and/or country level
- Mapping of annual revenue generated by listed major players from the medical devices market (or the nearest reported business unit/product category)
- Extrapolation of the revenue mapping of the listed major players to derive the global market value of the respective segments/subsegments
- Summation of the market value of all segments/subsegments to arrive at the global medical devices market
The data mentioned above was consolidated and added with detailed inputs and analysis from MarketsandMarkets and presented in this report.
Market Size Estimation (Bottom-up & Top-down Approaches)
Data Triangulation
After determining the overall size of the global medical devices market using the methodology described above, the market was segmented into several segments and subsegments. The data triangulation and market breakdown procedures were employed, as applicable, to complete the overall market engineering process and obtain exact market value data for the key segments and subsegments. The extrapolated market data was triangulated by studying various macroindicators and regional trends from both demand- and supply-side participants.
Market Definition
The Medical Devices Market comprises regulated capital medical equipment, instruments, implants, diagnostic systems, therapeutic devices, monitoring systems, surgical technologies, and associated capital healthcare equipment used for the prevention, diagnosis, monitoring, treatment, and management of medical conditions across hospitals, ambulatory surgical centers, specialty clinics, diagnostic laboratories, and home healthcare settings. The market encompasses durable medical devices across clinical specialties, including diagnostic imaging, in-vitro diagnostics, cardiovascular, orthopedic, ophthalmology, endoscopy, diabetes care, wound care, kidney care, respiratory care, patient monitoring, surgical technologies, robotic-assisted systems, urology, ENT, sterilization, infusion therapy, dermatology, and other specialty medical devices.
Key Stakeholders
- Application design and software developers
- Big data vendors
- Business analysts
- Cloud service providers
- Consulting service providers
- Data scientists
- Distributors and Value-added Resellers (VARs)
- Government agencies
- Independent Software Vendors (ISV)
- Managed service providers
- Market research and consulting firms
- Support and maintenance service providers
- System Integrators (SIs)/migration service providers
- Technology providers
- Value-added resellers (VARs)
Report Objectives
- Medical device manufacturing companies
- Component suppliers, raw material providers, and contract manufacturers
- Distributors, dealers, and commercial service providers
- Healthcare service providers
- Hospitals, clinics, and integrated healthcare systems
- Ambulatory surgery centers (ASCs) and specialty care centers
- Diagnostic laboratories and imaging centers
- Academic medical centers and universities
- Contract research organizations (CROs) and clinical research organizations
- Medical research laboratories and research institutes
- Government agencies and regulatory authorities
- Reimbursement agencies and insurance providers
- Group purchasing organizations (GPOs) and healthcare procurement organizations
- Digital health, AI, and medical software solution providers
- Home healthcare providers and remote patient monitoring service providers
- Dialysis centers, cardiac care centers, ophthalmology centers, and diabetes care centers
- Market research and consulting firms
- Investors, venture capital firms, and healthcare funding organizations
- Professional medical associations and surgical training centers
Available customizations:
Based on the market data provided, MarketsandMarkets offers customizations tailored to your company’s specific needs. The following customization options are available for the report:
GEOGRAPHIC ANALYSIS
- Further breakdown of the Rest of Europe medical devices market into Russia, Switzerland, Denmark, Austria, and others
- Further breakdown of the Rest of Asia Pacific medical devices market into South Korea, Taiwan, and others
- Further breakdown of the Rest of Latin America medical devices market into Argentina, Colombia, Chile, Ecuador, and others
- Further breakdown of the Southeast Asia medical devices market into Malaysia, Singapore, Australia, New Zealand, and others
COMPETITIVE LANDSCAPE ASSESSMENT
- Market share analysis, by region (North America and Europe), which provides the market share of the top 3 to 5 key players in the medical devices market
- Competitive leadership mapping for established players in the US
Get the Full Top 10 Medical Device Technologies Market Report
Full forecast, segment splits, and company analysis for all Top 10 Medical Device Technologies Market.
- Canada Top 10 Medical Device Technologies Market
- US Top 10 Medical Device Technologies Market
- Germany Top 10 Medical Device Technologies Market
- France Top 10 Medical Device Technologies Market
- UK Top 10 Medical Device Technologies Market
- Italy Top 10 Medical Device Technologies Market
- Spain Top 10 Medical Device Technologies Market
- China Top 10 Medical Device Technologies Market
- Japan Top 10 Medical Device Technologies Market
- India Top 10 Medical Device Technologies Market
- Brazil Top 10 Medical Device Technologies Market
- Mexico Top 10 Medical Device Technologies Market
- Rest Of Europe Top 10 Medical Device Technologies Market
- Rest Of Asia Pacific Top 10 Medical Device Technologies Market
- Rest Of Latin America Top 10 Medical Device Technologies Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report