Spain Agricultural Adjuvants Market (2026-2031)
The Spain Agricultural Adjuvants Market was valued at $199.4 Million in 2026 and projected to reach to $217.2 Million by 2031, representing a compound annual growth rate of 4.2%. Spain's agricultural adjuvants market is poised for steady growth through 2031, driven by the country's commitment to sustainable farming practices and EU regulatory compliance.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Spain Agricultural Adjuvants Market Trends and Insights
- Spain's agricultural sector relies increasingly on adjuvants to enhance pesticide and fertilizer efficacy, driven by the country's significant crop production and sustainability initiatives.
- The market in Spain reflects broader European trends toward precision agriculture and regulatory compliance with EU pesticide directives. During the forecast period from 2026 to 2031, Spain's adjuvants market will benefit from rising demand for crop protection solutions and improved farming practices.
- Spain's diverse agricultural landscape—encompassing cereals, olives, citrus, and wine production—creates varied adjuvant requirements across regions.
- Growth in Spain is supported by farmer adoption of advanced formulations and increasing awareness of adjuvant benefits in reducing chemical inputs while maintaining yield..
Key Market Statistics
- CAGR (2026-2031) 4.2% CAGR
- Market Size, 2026 ~USD 199.4 Million
- Forecast, 2031 ~USD 217.2 Million
- Country Spain
Spain Agricultural Adjuvants Market Overview
Market Size & Growth :
Spain's agricultural adjuvants market is valued at USD 199.4 million in 2026, with projected growth to USD 217.2 million by 2031, representing a steady CAGR of 4.2% over the forecast period.
Sustainability-Driven Adoption :
Spanish agricultural producers are increasingly adopting adjuvants to optimize pesticide and fertilizer efficiency, aligning with the country's stringent EU sustainability regulations and precision farming initiatives.
Crop Production Significance :
Spain's diverse crop portfolio, including cereals, olives, grapes, and vegetables, creates substantial demand for adjuvants that enhance product performance and reduce chemical usage across multiple agricultural segments.
Regional Market Dynamics :
Spain's adjuvants market benefits from advanced agricultural infrastructure, strong farmer adoption of modern farming techniques, and government support for sustainable agricultural practices across the Iberian Peninsula.
Spain Agricultural Adjuvants Market Dynamics
- The market will benefit from increasing farmer awareness of adjuvant benefits in optimizing crop yields while reducing chemical inputs.
- Spain's diverse agricultural landscape, spanning from Mediterranean crops to northern cereals, creates varied demand across multiple adjuvant categories.
- Investment in precision agriculture technologies and digital farming solutions will further accelerate market expansion.
- The 4.2% CAGR reflects moderate but consistent growth as Spanish farmers balance productivity with environmental stewardship and cost efficiency..
Market Ecosystem


OVERVIEW
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
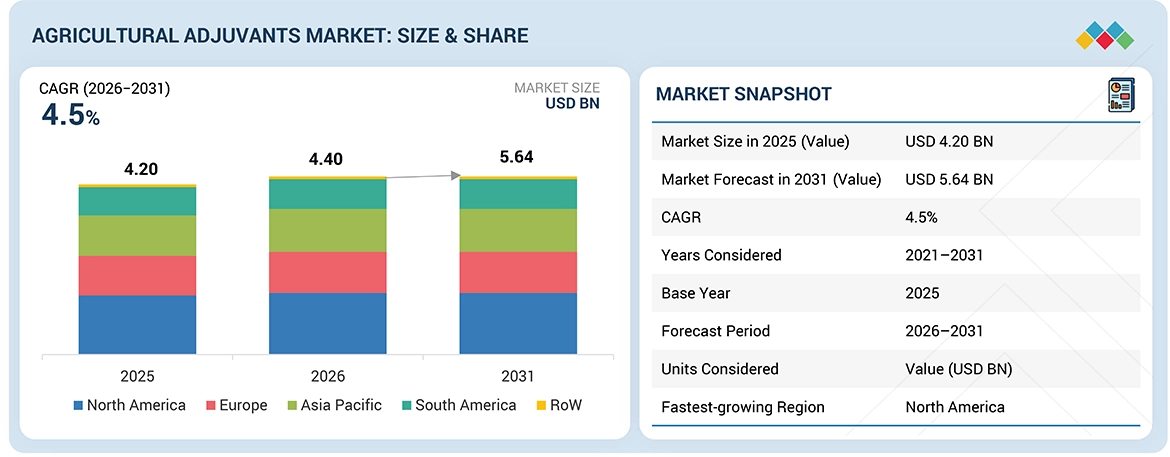
The agricultural adjuvants market is projected to reach USD 5.64 billion by 2031 from USD 4.40 billion in 2026, at a CAGR of 4.5% from 2026 to 2031. The market is growing steadily as farmers are looking for ways to enhance the effectiveness of pesticides. The market is also driven by the changing regulations that focus on spray drift reduction and input management. Agricultural adjuvants have become an essential part of modern crop protection as the use of adjuvants has increased in cereals and grains, fruits and vegetables, and row crops. The agricultural adjuvants market is also driven by the increasing demand for adjuvants in developing countries.
Market Size and Forecast:
- Market Size Value in 2025: USD 4.20 Billion
- Market Size Value in 2026: USD 4.40 Billion
- Revenue Forecast in 2031: USD 5.64 Billion
- Growth Rate: CAGR of 4.5% from 2026 to 2031
- Data available from 2021 to 2031
- Base year: 2025
- Forecast period: 2026–2031
- North America is estimated to account for the largest market share of 34.6% in 2026.
- The tank-mix segment is expected to register a higher CAGR of 4.7% from 2026 to 2031.
Key Market Trends and Insights
- By Crop Type: Rising cultivation of cereals & grains, oilseeds & pulses, fruits & vegetables, and other high-value crops is boosting the adoption of agriculture adjuvants to enhance crop protection efficiency and productivity.
-
Key Advantages: Agriculture adjuvants improve pesticide performance, enhance spray coverage and absorption, reduce drift, and support higher crop yields.
-
Growing Trends: Adoption of precision agriculture, advanced spraying technologies, and sustainable farming practices is increasing the use of agriculture adjuvants.
- Growth Opportunities: Growing food demand, expansion of high-value crop cultivation, increased focus on efficient pesticide use, and supportive government initiatives are creating significant opportunities in the agriculture adjuvants market.
KEY TAKEAWAYS
-
BY REGIONNorth America is estimated to account for the largest market share of 34.6% in 2026.
-
BY ADOPTION STAGEBy adoption stage, the tank-mix segment is expected to register a higher CAGR of 4.7% from 2026 to 2031.
-
BY APPLICATIONBy application, the herbicides segment is expected to register the highest CAGR of 4.8% during the forecast period.
-
BY CROP TYPEBy crop type, the cereals and grains segment is projected to grow at the highest rate from 2026 to 2031.
-
BY FUNCTIONBy function, the activator adjuvants segment is estimated to dominate the market.
-
BY FORMULATIONBy formulation, the emulsifiable concentrates segment is estimated to account for a significant market share.
-
COMPETITIVE LANDSCAPECorteva Agriscience, Wilbur-Ellis Company LLC, WinField United, and Precision Laboratories LLC were identified as some of the star players in the agricultural adjuvants market, given their strong market share and product footprint.
The agricultural adjuvants market is expected to experience steady growth owing to the demand from farmers for environmentally friendly methods of crop protection. The market growth is also attributed to new microbial and biochemical products entering the market and existing integrated pest management (IPM) systems gaining wider acceptance from farmers. The agricultural industry identifies biopesticides as a highly promising growth sector because farmers now use biological products in their crop protection programs across all major crop categories, including fruits, vegetables, and row crops.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
The global market for agricultural adjuvants is moving in the direction of sustainable and efficiency-driven crop protection strategies. Increasing regulatory pressure related to the use and application of pesticides and the increasing awareness level related to the quality of the spray water are the major factors driving the demand for water conditioners, buffering agents, and anti-foaming agents. Increasing awareness levels related to the quality of pesticides and the impact of hard water and pH imbalance on the efficacy and efficiency of the pesticides are driving the market for spray solution management technologies. Increasing innovation in formulation and spray solution diagnostic tools is helping the development of multi-functional and eco-friendly utility adjuvants.

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Growing adoption of precision agriculture

-
Stringent environmental regulations


Level
-
Strict regulatory approval processes for formulation components

-
Performance variability under diverse climatic and crop conditions


Level
-
Rising demand for sustainable agricultural inputs

-
Herbicide resistance concerns driving demand for advanced surfactant technologies


Level
-
Raw material price volatility

-
Ongoing compatibility requirements with new pesticide formulations

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Growing adoption of precision agriculture
The growing use of precision agriculture methods and advanced spraying technology is a major driving force behind the demand for high-performance adjuvants, as farmers are increasingly turning to the use of GPS-guided systems, drone spraying, sensor-based field mapping, and variable rate application equipment that require optimized droplet spectrum control, superior canopy penetration, enhanced surface wetting, and reduced off-target drift to maximize pesticide performance, reduce total chemical use, improve efficiency, and optimize return on investment in large-scale and high-value crop production systems.
Restraint: Strict regulatory approval processes for formulation components
The stringent regulatory approval procedures for surfactants, oils, polymers, and specialty formulation ingredients may result in longer development times for products, increased expenses for regulatory compliance, and decreased flexibility of formulations in key agricultural areas.
Opportunity: Rising demand for sustainable agricultural inputs
The increasing global focus on sustainable agriculture and responsible management of agricultural inputs creates a substantial opportunity for growth for bio-based, low-toxicity, and biodegradable adjuvants, especially those produced from renewable resources, as farmers look for solutions that meet the requirements of residue compliance, sustainability, carbon reduction, and integrated crop management.
Challenge: Raw material price volatility
Raw material price volatility, particularly petroleum-based surfactants, specialty emulsifiers, and performance additives, poses a significant cost challenge to the manufacturing sector, and supply chain disruptions, energy price volatility, transportation challenges, and geopolitical tensions also affect the agricultural adjuvants market in terms of procurement stability and pricing strategies.
AGRICULTURE ADJUVANTS MARKET TRENDS, GROWTH, AND FORECAST [LATEST]: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Application of microbial bioinsecticides in corn and soybean farming | Enhances targeted pest control, minimizes residues, and supports sustainable row-crop systems |
 |
Use of Bacillus-based biofungicides in fruits and vegetables | Strengthens disease management, improves crop quality, and meets residue-free requirements |
 |
Integration of botanical and microbial biopesticides in specialty crops | Provides broad-spectrum protection and supports IPM while reducing synthetic pesticide use |
 |
Use of biofungicides and seed-applied biologicals in cereals and grains | Improves early-stage protection, enhances plant vigor, and promotes sustainable crop production |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
Some of the prominent companies in this market include well-established and financially sound manufacturers of biopesticide products. These companies have been operational in the market for over a decade and have diversified portfolios, latest technologies, and excellent global sales and marketing networks. The market ecosystem comprises manufacturers, regulatory bodies, and end users. Key manufacturers like Corteva Agriscience, Valent BioSciences, Certis Biologicals, and BASF develop microbial, botanical, and biochemical solutions.

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Agricultural Adjuvants Market, By Function
The activator adjuvants segment is estimated to lead the agricultural adjuvants market. The capacity to reduce surface tension, improve spray coverage, and increase plant tissue penetration makes surfactants an integral part of tank-mix adjuvants. Non-ionic surfactants, organosilicone surfactants, and oil-based surfactants are commonly used to improve the efficacy of pesticides in different environmental conditions. The increased need for spray efficiency, canopy coverage, and rainfastness has further consolidated the market leadership of surfactants in the tank-mix adjuvants market.
Agricultural Adjuvants Market, By Application
By application, the herbicides segment is estimated to account for the largest share of the agricultural adjuvants market. The widespread challenge of weed resistance and the need for improved herbicide performance have increased reliance on adjuvants that enhance spreading, absorption, and droplet retention. Tank-mix adjuvants play a critical role in improving herbicide efficacy, reducing drift, and minimizing reapplication frequency. Given the high volume of herbicide usage globally, particularly in row crops and cereals, this segment continues to dominate the market.
Agricultural Adjuvants Market, By Crop Type
By crop type, the cereals and grains segment is estimated to hold the largest share of the agricultural adjuvants market. The cultivation of crops like wheat, rice, corn, and barley in prominent agricultural countries of the world has fueled the demand for herbicides and pesticides, hence boosting the demand for tank mix adjuvants. The large-scale cultivation of these crops, along with the focus on maximizing crop production efficiency, has fueled the demand for tank mix adjuvants. The continuous need for the application of these chemicals for efficient crop growth has ensured the demand for performance-enhancing adjuvants.
Agricultural Adjuvants Market, By Adoption Stage
In-formulation adjuvants currently account for the largest market share, by adoption stage. In-formulation adjuvants are directly introduced into crop protection formulations by manufacturers, which ensures that compatibility is optimized. In-formulation adjuvants are preferred because of the increasing demand for ready-to-use formulations that ensure improved efficiency during application. There is also pressure from authorities regarding spray drift control and environmental safety, which makes agrochemical companies introduce adjuvants directly into formulations, hence their dominance.
Agricultural Adjuvants Market, By Formulation
The largest market share is occupied by suspension-type formulations. This is primarily because of their high level of stability, dispersion, and compatibility. These formulations are highly effective in maintaining the consistency of the droplet size and also in minimizing the problems of sedimentation. These are highly useful in the context of large-scale agricultural spray activities. In addition, the need for reliability in terms of conditions has increased the use of suspension-type tank mix adjuvants in key agricultural regions.
REGION
North America to be fastest-growing region in global agricultural adjuvants market during forecast period
The agricultural adjuvants market in North America is expected to witness rapid growth, owing to stringent regulations regarding spraying, increasing incidents of herbicide resistance, and the need to improve pesticide efficiency. Adjuvants are being increasingly adopted by farmers as they help in reducing drift, improving spraying, and managing costs. Increased investments in new and precision-compatible adjuvants are contributing to the growth of the North American market.

AGRICULTURE ADJUVANTS MARKET TRENDS, GROWTH, AND FORECAST [LATEST]: COMPANY EVALUATION MATRIX
Star companies such as Corteva Agriscience, along with other major agrochemical players worldwide, have broad and diversified tank mix adjuvant portfolios, strong brand names, and significant influence in the market. Emerging leaders like Certis continue to increase their footprint by developing innovative performance-enhancing adjuvant products and strategic partnerships, especially in sustainable and specialty crop segments. Players continue to operate steadily with regional offers, while pervasive players have a moderate and expanding footprint in the market.

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- BASF SE (Germany)
- Corteva Agriscience (US)
- Croda International plc (UK)
- Evonik Industries AG (Germany)
- Solvay SA (Belgium)
- Nufarm Ltd. (Australia)
- Clariant AG (Switzerland)
- Huntsman Corporation (US)
- Helena Agri-Enterprises LLC (US)
- Wilbur-Ellis Company LLC (US)
- Brandt Consolidated Inc. (US)
- Akzo Nobel N.V. (Netherlands)
- Loveland Products Inc. (US)
- Precision Laboratories LLC (US)
- Miller Chemical & Fertilizer LLC (US)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 4.20 Billion |
| Market Forecast in 2030 (value) | USD 5.64 Billion |
| Growth Rate | CAGR of 4.5% from 2026 to 2031 |
| Years Considered | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends. |
| Segments Covered |
|
| Countries Covered | North America, South America, Europe, Asia Pacific, Rest of the World |
WHAT IS IN IT FOR YOU: AGRICULTURE ADJUVANTS MARKET TRENDS, GROWTH, AND FORECAST [LATEST] REPORT CONTENT GUIDE

DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Crop Protection Chemical Manufacturer |
|
|
| Agricultural Input Distributor |
|
|
| Adjuvant Formulation Company |
|
|
| Investor / Private Equity Firm |
|
|
RECENT DEVELOPMENTS
- January 2025 : Syngenta Group advanced its biologicals platform with the rollout of new nature-inspired microbial and biochemical solutions supported by expanded manufacturing capacity.
- February 2025 : UPL launched Thiopron, a sulfur-based biofungicide aimed at sustainable powdery mildew control in specialty crops
- January 2025 : Valent BioSciences entered into a strategic partnership to commercialize Sweetsei and other Seipasa biostimulants in the US market.
- December 2024 : AgBiome transferred its biological fungicides Howler and Theia to Certis Biologicals, enabling expanded commercialization of these microbial solutions globally.
Related Ecosystem
Agrochemicals
- Phosphatic Fertilizers
- Potassic Fertilizers
- Fungicides
- Ammonium Nitrate
- Anticoagulant Rodenticides
- AZELIS HOLDINGS SA
- Basf se
- Origin Enterprises plc
- MITSUI AGRO BUSINESS SACO
- Mitsui & Co., Ltd.
Key Takeaways
- Spain's agricultural adjuvants market is valued at USD 199.4 million in 2026 and will reach USD 217.2 million by 2031.
- Spain experiences a steady 4.2% CAGR, reflecting moderate but consistent growth in adjuvant adoption across the country.
- Spain's diverse crop portfolio—including olives, citrus, cereals, and wine—drives demand for specialized adjuvant formulations.
- EU regulatory frameworks and sustainability pressures in Spain are accelerating the shift toward efficient, environmentally responsible adjuvant solutions.
Agricultural Adjuvants Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | EMULSIFIABLE CONCENTRATES (Formulation) |
| Forecast Period | 2026–2031 |
| Growth Rate | CAGR of 4.5% from 2026 to 2031 |
| Largest Segment | SUSPENSION CONCENTRATES (Formulation) |
| Market Size Base Year (Billions) | ~USD 4.53 (2026) |
| Revenue Forecast (Billions) | ~USD 5.64 (2031) |
| Segments Covered | Adoption Stage, Application, Crop Type, Function, Formulation |
Spain Agricultural Adjuvants Market Report Segmentation
5 segment dimensions are covered across the global market.
By Adoption Stage
- In-Formulation
- Tank-Mix
By Application
- Fungicides
- Herbicides
- Insecticides
- Other Applications
By Crop Type
- Cereals & Grains
- Corn
- Fruits & Vegetables
- Oilseeds & Pulses
- Other Cereals & Grains
- Other Crop Types
- Other Oilseeds & Pulses
- Rice
- Soybean
- Sunflower
- Wheat
By Function
- Activator Adjuvants
- Antifoam Agents
- Buffers/Acidifiers
- Compatibility Agents
- Drift Control Agents
- Oil-Based Adjuvants
- Other Utility Adjuvants
- Surfactants
- Utility Adjuvants
- Water Conditioners
By Formulation
- Emulsifiable Concentrates
- Suspension Concentrates
SPAIN: AGRICULTURAL ADJUVANTS MARKET, BY APPLICATION, 2023–2028
| Segment | 2023 | 2024 | 2025 | 2026 | 2027 | 2028 | CAGR (%) |
|---|---|---|---|---|---|---|---|
| FUNGICIDES | 113.5 | 118.2 | 123.3 | 128.8 | 134.6 | 140.8 | 4.4 |
| HERBICIDES | 33.5 | 34.9 | 36.3 | 37.9 | 39.5 | 41.3 | 4.3 |
| INSECTICIDES | 22.7 | 23.6 | 24.4 | 25.4 | 26.4 | 27.4 | 3.8 |
| OTHER APPLICATIONS | 7 | 7.1 | 7.3 | 7.4 | 7.5 | 7.7 | 1.8 |
| TOTAL | 176.8 | 183.8 | 191.3 | 199.4 | 208 | 217.2 | 4.2 |
Target Audience
- Agricultural Chemical Manufacturers : Need Spain-specific market data to develop localized product portfolios, assess market entry feasibility, and optimize distribution strategies for adjuvants in the Spanish agricultural sector.
- Agrochemical Distributors & Retailers : Require detailed market insights to forecast demand, manage inventory for Spanish farmers, and identify growth opportunities across different crop segments and regional markets within Spain.
- Crop Protection Companies : Seek Spain market intelligence to understand adjuvant adoption trends, farmer preferences, and regulatory compliance requirements for enhancing their pesticide and fertilizer product effectiveness.
- Agricultural Investment Firms : Need comprehensive Spain market analysis to evaluate investment opportunities in adjuvant manufacturers, distributors, and agtech companies operating in the Spanish agricultural ecosystem.
- Government & Agricultural Policy Bodies : Require market data to inform agricultural sustainability policies, assess adjuvant market trends, and develop strategies supporting Spain's transition to more efficient and environmentally responsible farming practices.
Key Companies in the Spain Agricultural Adjuvants Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| FMC CORPORATION | United States | Public Company | Insecticides,Herbicides,Fungicides, |
| RIZOBACTER | Argentina | Private Company | |
| AGRIUM INC. | Canada | Private Company | Nitrogen-based crop nutrients,Potash crop nutrients,Phosphate-based crop nutrients, |
| BUNGE LIMITED | United States | Public Company | Soybean Processing and Refining,Softseed Processing and Refining,Other Oilseeds Processing and Refining, |
| COMPASS MINERALS | United States | Public Company | Salt (deicing, consumer, industrial, water treatment, nutrition),Plant Nutrition (SOP fertilizers, turf, organic), |
| DOW CHEMICAL COMPANY | United States | Private Company | Packaging and Specialty Plastics (ethylene, polyethylene, elastomers, EVA, EPDM),Industrial Intermediates and Infrastructure (ethylene derivatives, cellulose ethers, acrylic emulsions),Performance Materials and Coatings (acrylics, additives, ingredients), |
| OCI COMPANY LTD. | Netherlands | Public Company | Ammonia and renewable/lower-carbon ammonia,Granular urea, UAN, CAN, ammonium nitrate and sulphate,Methanol and related transportation/industrial products, |
| SYNTHOS S.A | Poland | Private Company | Styrene-butadiene and butadiene rubbers (KER, KRALEX, SYNTECA, NBR),EPS/XPS and polystyrene (InSphere, Inpacto, Silver, Synthos XPS PRIME, SYNTHOS PS),Dispersions, latexes, adhesives, photoinitiators, and specialty chemicals, |
| ORIGIN ENTERPRISES PLC | Ireland | Public Company | Agronomy advice and on-farm services,Seed, crop nutrition, biologicals, and crop protection inputs,Fertilizer blending, animal feed ingredients, and grain/feed trading, |
FMC CORPORATION
FMC Corporation is a U.S.-based public company founded in 1883 with 5,500 employees. The company operates as an established industrial enterprise with over a century of operational history.
RIZOBACTER
Rizobacter is an Argentine private company founded in 1977 with 460 employees. The company operates as a mid-sized enterprise in South America.
AGRIUM INC.
Agrium Inc. is a Canadian private company founded in 1992 with 15,300 employees. The company operates as a large-scale enterprise in Canada.
BUNGE LIMITED
Bunge Limited is a U.S.-based public company founded in 1818 with 34,000 employees. The company is one of the oldest and largest enterprises in its sector.
COMPASS MINERALS
Compass Minerals is a U.S.-based public company founded in 1844 with 1,849 employees. The company operates as a mid-sized publicly traded enterprise with nearly two centuries of history.
DOW CHEMICAL COMPANY
Dow Chemical Company is a U.S.-based private company founded in 1897 with 34,600 employees. The company operates as a large-scale chemical enterprise.
OCI COMPANY LTD.
OCI Company Ltd. is a Netherlands-based public company founded in 2013 with 761 employees. The company operates as a publicly traded enterprise.
SYNTHOS S.A
Synthos S.A. is a Polish private company founded in 1945 with 2,975 employees. The company operates as a mid-sized private enterprise in Poland.
ORIGIN ENTERPRISES PLC
Origin Enterprises PLC is an Ireland-based public company founded in 2006 with 2,997 employees. The company operates as a publicly traded enterprise.
Reasons to Buy this Report
- Spain-Specific Market Sizing : Obtain precise market valuation data for Spain's adjuvants sector with detailed 2026-2031 forecasts, enabling accurate business planning and investment decisions tailored to the Spanish agricultural landscape.
- Regulatory & Sustainability Insights : Understand how EU sustainability directives and Spanish agricultural policies are shaping adjuvant adoption, helping you align product development and marketing strategies with local regulatory requirements.
- Crop-Specific Demand Analysis : Gain insights into adjuvant demand across Spain's key crops—olives, grapes, cereals, and vegetables—to identify high-potential segments and tailor solutions for regional agricultural priorities.
- Competitive Positioning Strategy : Leverage Spain-focused market intelligence to benchmark against local competitors, identify market gaps, and develop targeted go-to-market strategies for the Spanish agricultural sector.
- Growth Opportunity Identification : Discover emerging trends in Spanish precision farming adoption and sustainability initiatives that present expansion opportunities for adjuvant manufacturers and distributors in the region.
Frequently asked questions
What is the current size of Spain's agricultural adjuvants market?
Spain's agricultural adjuvants market is estimated at USD 199.4 million in 2026.
What is the projected market size for Spain by 2031?
Spain's agricultural adjuvants market is forecast to reach USD 217.2 million by 2031.
What is the CAGR for Spain's agricultural adjuvants market?
Spain's agricultural adjuvants market is expected to grow at a CAGR of 4.2% from 2026 to 2031.
Which crops drive adjuvant demand in Spain?
Spain's major crops—olives, citrus, cereals, and wine grapes—are primary drivers of adjuvant demand due to their extensive cultivation and pest management requirements.
How do EU regulations impact Spain's adjuvants market?
EU pesticide directives and sustainability regulations compel Spanish farmers to adopt more efficient adjuvants that reduce chemical inputs while maintaining crop protection effectiveness.
RESEARCH METHODOLOGY
Get the Full Agricultural Adjuvants Market Report
Full forecast, segment splits, and company analysis for all Agricultural Adjuvants Market.
- Rest Of Europe Agricultural Adjuvants Market
- United Kingdom Agricultural Adjuvants Market
- US Agricultural Adjuvants Market
- Canada Agricultural Adjuvants Market
- Mexico Agricultural Adjuvants Market
- Germany Agricultural Adjuvants Market
- UK Agricultural Adjuvants Market
- France Agricultural Adjuvants Market
- Italy Agricultural Adjuvants Market
- China Agricultural Adjuvants Market
- India Agricultural Adjuvants Market
- Japan Agricultural Adjuvants Market
- Brazil Agricultural Adjuvants Market
- Argentina Agricultural Adjuvants Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report