Europe Artificial Intelligence in Cybersecurity Market (2023-2028)

The Europe Artificial Intelligence in Cybersecurity Market was valued at $1947.2 Million in 2023 and projected to reach to $5692.6 Million by 2028, representing a compound annual growth rate of CAGR 23.9%. Europe's AI in cybersecurity market is positioned for sustained high-growth expansion through 2028, driven by regulatory mandates, increasing cyber threat sophistication, and substantial digital infrastructure investments.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Europe Artificial Intelligence in Cybersecurity Market Trends and Insights
- This represents a compound annual growth rate of 23.9%, significantly outpacing global trends and reflecting Europe's heightened focus on digital security infrastructure.
- Europe is increasingly adopting AI-driven threat detection, anomaly identification, and automated response systems to combat evolving cyber threats across financial services, healthcare, and critical infrastructure sectors. The European market's accelerated growth is driven by stringent regulatory frameworks including GDPR and NIS2 Directive, which mandate advanced cybersecurity measures across member states.
- Europe's investment in AI cybersecurity solutions reflects the region's commitment to protecting sensitive data and maintaining competitive advantage in the digital economy.
- Organizations across Europe are prioritizing AI-powered security platforms to address sophisticated ransomware attacks, data breaches, and emerging threat vectors that traditional security tools cannot adequately counter..
Key Market Statistics
- CAGR (2023-2028) CAGR 23.9%
- Market Size, 2023 ~USD 1947.2 Million
- Forecast, 2028 ~USD 5692.6 Million
- Geography Europe
Europe Artificial Intelligence in Cybersecurity Market Overview
Market Valuation Growth :
Europe's AI in cybersecurity market reached $1,947.2 million in 2023 and is projected to grow to $5,692.6 million by 2028, representing a 23.9% CAGR that outpaces the global average of 21.9%.
Regional Leadership Position :
Europe demonstrates the strongest commitment to AI-driven cybersecurity adoption among developed regions, driven by stringent GDPR compliance requirements and heightened regulatory frameworks across member states.
Digital Security Infrastructure Investment :
European organizations are prioritizing AI-powered threat detection and response systems to combat sophisticated cyber threats, reflecting increased cybersecurity budgets and digital transformation initiatives across the continent.
Regulatory Compliance Catalyst :
The European Union's digital security directives and NIS2 Directive implementation are accelerating enterprise adoption of AI cybersecurity solutions to meet mandatory compliance standards and protect critical infrastructure.
Europe Artificial Intelligence in Cybersecurity Market Dynamics
- The region's mature technology ecosystem and strong emphasis on data protection create favorable conditions for AI-powered security solutions adoption across financial services, healthcare, government, and manufacturing sectors. Key growth drivers include the NIS2 Directive implementation, rising ransomware incidents targeting European enterprises, and accelerated cloud migration initiatives.
- European organizations are increasingly deploying machine learning-based threat detection, behavioral analytics, and automated incident response platforms.
- Strategic partnerships between cybersecurity vendors and European enterprises, combined with government-backed digital security initiatives, will further propel market expansion and innovation in AI-driven threat prevention technologies..
Market Ecosystem


OVERVIEW
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
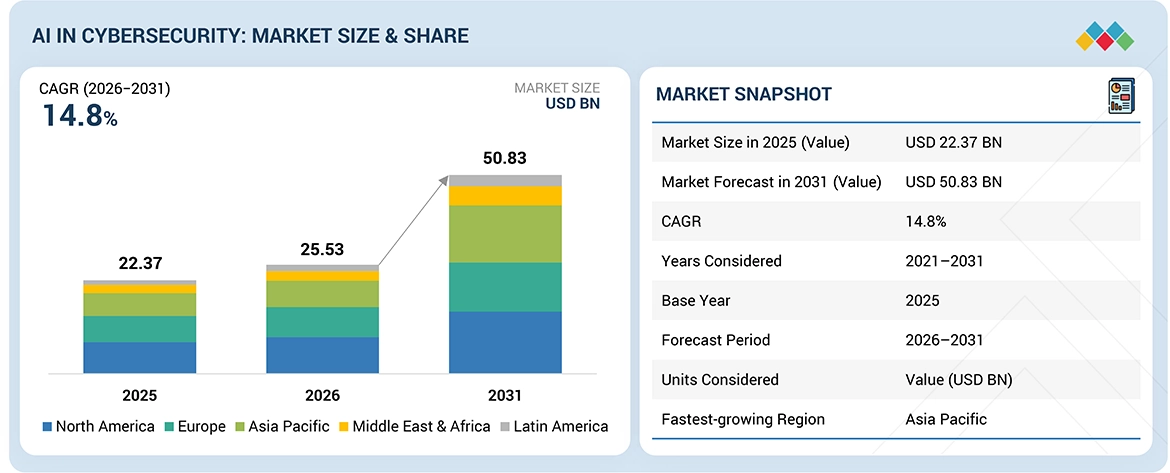
The AI in cybersecurity market was a valuation of USD 25.53 billion in 2026. By 2031, it's expected to reach USD 50.83 billion, reflecting a compound annual growth rate (CAGR) of 14.8%. The increasing market growth has been driven by high enterprise adoption of AI in sectors such as financial, retail, healthcare, and technology, where AI-enabled cybersecurity has been used to monitor attacks and analyze large security data to help make faster decisions for various cybersecurity operations. Organizations are deploying artificial intelligence across security operations to automatically incorporate detections of anomalous activity, accelerate responses to incidents, and bolster security at cloud, network, and endpoint. The rising adoption of threat intelligence, security analytics platforms, and identity protection through AI adoption is a growing enterprise use case in the cybersecurity landscape.
Market Size and Forecast:
- Market Size Value in 2025: USD 22.37 Billion
- Market Size Value in 2026: USD 25.53 Billion
- Revenue Forecast in 2031: USD 50.83 Billion
- Growth Rate: CAGR of 14.8% from 2026 to 2031
- Base year: 2025
- Forecast period: 2026–2031
- North America is estimated to account for the largest market share of 35.50% in 2026.
- The endpoint security & management segment is positioned to hold the largest market share of 18.75% in 2026.
Key Market Trends and Insights
- By Solution: The AI-enhanced Security Products segment accounts for a significant share of the AI in Cybersecurity market, driven by increasing demand for AI-powered threat detection, automated incident response, real-time monitoring, and enhanced protection against sophisticated cyber threats.
- Industry Dynamics: Organizations are increasingly adopting AI-driven cybersecurity solutions to strengthen security operations, improve threat intelligence, accelerate incident response, and enhance visibility across cloud, network, endpoint, and enterprise IT environments.
- Market Drivers: The increasing complexity and frequency of cyberattacks, expanding cloud adoption, growing digital transformation initiatives, rising attack surfaces across connected devices, and the need for real-time threat detection and automated security operations are driving market growth.
- Future Opportunities: Significant opportunities are emerging in AI-native security platforms, autonomous threat detection and response, predictive threat intelligence, cloud security, identity and access management (IAM), and AI-powered cybersecurity operations designed to improve organizational resilience and reduce security response times.
KEY TAKEAWAYS
-
By RegionNorth America is estimated to account for the largest market share of 35.50% in 2026.
-
By OfferingThe software segment is projected to hold the largest market share in 2026.
-
By Security TypeThe endpoint security & management segment is positioned to hold the largest market share of 18.75% in 2026.
-
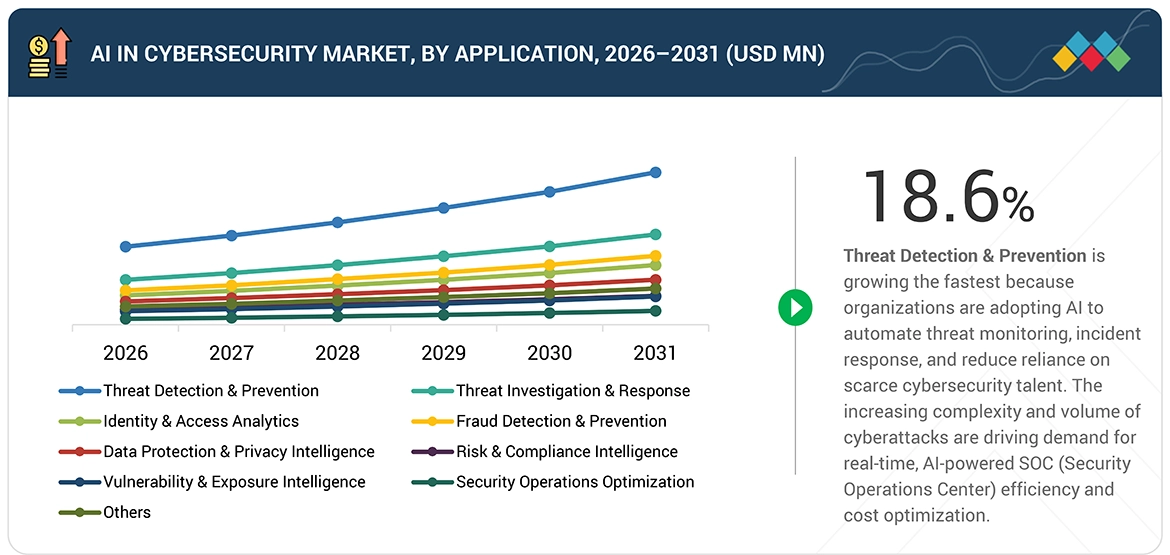
By ApplicationThe security operations optimization segment is projected to showcase the highest CAGR of 18.6% during the forecast period.
-
By VerticalThe retail & e-commerce segment is projected to grow at the highest CAGR during the forecast period.
-
Competitive Landscape - Key PlayersMicrosoft, Palo Alto Networks, and AWS are among the leading players in the AI in cybersecurity market, given their strong market share and product portfolios.
-
Competitive Landscape - Startups/SMEsDeep Instinct, Nozomi Networks, and Acalvio Technologies have distinguished themselves among other players by securing strong footholds in specialized niche areas, underscoring their potential as emerging leaders.
Many global initiatives are accelerating the adoption of AI in cybersecurity as organizations focus on improving threat detection and response across ever more complex environments. Adoption is being further driven by the increasing need for automated SOC workflows and faster incident response via platforms including SOAR and XDR, as well as rising adoption of AI for securing cloud workloads and APIs. Technology vendors, meanwhile, are expanding infrastructure to enable these use cases, including AI-enabled security platforms and high-performance computing infrastructures.
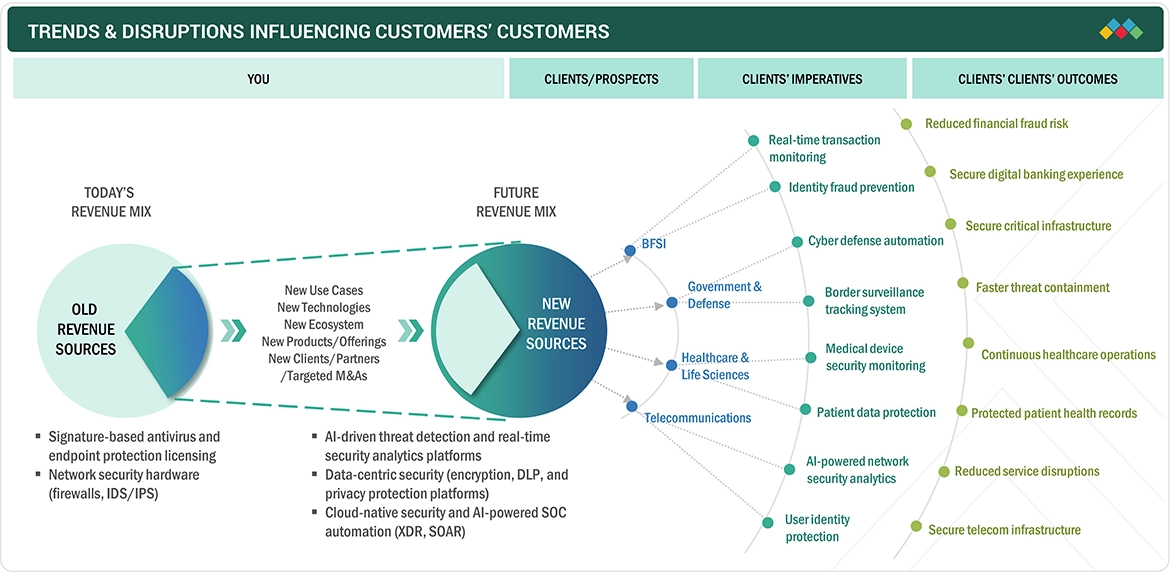
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
The cybersecurity landscape is evolving. There is a shift away from the old, reactive security measures and toward smart, data-powered platforms that can respond automatically and in real time. Companies are now weaving AI into various security tools, such as identity management, data protection, and network security, all in an effort to make better decisions. This change is causing a significant shake-up, allowing vendors to build unified, scalable security systems that adapt to the changing needs of both businesses and their partners.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Increasing complexity and frequency of cyberattacks driving AI adoption

-
AI-powered cloud workload & API security


Level
-
Limited availability of quality data and privacy concerns restricting AI effectiveness

-
Growth of AI-driven cloud security posture management (CSPM) & workload protection platforms


Level
-
Rising need for automated security operations creating growth opportunities

-
The growing use of artificial intelligence in identity threat detection and response (ITDR)


Level
-
Evolving adversarial threats posing challenges to AI-based cybersecurity systems

-
The use of shadow AI is creating unmonitored vulnerabilities in enterprise applications

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver – Increasing complexity and frequency of cyberattacks driving AI adoption
The rising frequency and complexity of cyberattacks, including zero-day exploits and AI-powered threats, are driving the adoption of AI in cybersecurity. Organizations are leveraging AI for real-time threat detection, anomaly identification, and faster response. The growing attack surface across cloud, endpoints, and networks further accelerates demand for advanced AI-driven cybersecurity solutions and services.
Restraint – Limited availability of quality data and privacy concerns restricting AI effectiveness
The efficacy of AI models also relies on the availability of large amounts of quality security information, which may not be feasible owing to privacy concerns and organizational barriers. Furthermore, the fear of sharing information may also be a challenge in the development of AI-based cybersecurity tools.
Opportunity – Rising need for automated security operations creating growth opportunities
The increasing need to manage alert volumes and reduce response times is creating strong demand for AI-driven security operations platforms. Technologies such as XDR, SOAR, and AI copilots are enabling automation of threat detection and response. This shift toward autonomous and intelligent security operations presents significant growth opportunities for vendors offering AI-powered security platforms, automation solutions, and managed security services.
Challenge – Evolving adversarial threats posing challenges to AI-based cybersecurity systems
Cybercriminals are increasingly using AI to develop more sophisticated attacks, which are difficult to evade. They are also using adversarial attacks, which are difficult to detect by AI models. Therefore, it is a continuous process for both attackers and defenders. Robustness, explainability, and robustness are challenges in this context.
ARTIFICIAL INTELLIGENCE IN CYBERSECURITY MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
A financial investment organization implemented zero-trust security, including SASE, endpoint security, and network security at Infosys. | The deployment improved threat detection, enabled centralized management, sped up incident response, and strengthened security policy compliance. |
 |
Used AWS-based cybersecurity platform (SageMaker, Glue, Lambda, S3) to detect and analyze large-scale cyber threats in real-time. | Exceeded cybersecurity benchmarks, processes 60,000 threats/sec, enables fast forensic analysis without performance impact, and operates efficiently with a small team. |
 |
Using model from Snorkel Flow, US national security teams can develop AI/ML applications that utilize text, voice, and satellite data to accelerate intelligence work. | Platform minimizes manual labeling effort, increases scalability, gives more transparent models and higher performance with easier troubleshooting. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
The AI in cybersecurity ecosystem comprises software and service providers that develop advanced threat detection systems, analytics tools, and comprehensive security platforms. Together, these components work seamlessly to safeguard digital environments. This integrated approach delivers a holistic suite of cybersecurity solutions, effectively protecting both enterprise and cloud infrastructures.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
AI in Cybersecurity Market, By Offering
Software will take the biggest share by 2026 because more businesses are using AI-based security tools. Companies want solutions that can quickly detect threats and handle them automatically. The growing use of cloud platforms is also pushing the demand for software even higher.
AI in Cybersecurity Market, By Security Type
Cloud security is expected to grow the fastest. This is because more companies are moving to the cloud and using multiple cloud services. AI helps them spot threats, fix issues, and manage security problems in real time. The shift toward cloud-native systems and zero-trust security is also increasing the need for these solutions.
AI in Cybersecurity Market, By Application
Threat detection and prevention is expected to grow the fastest as companies focus more on finding and stopping cyber threats early. Tools powered by AI, like anomaly detection and behavior analysis, are becoming important for real-time protection. As cyberattacks become more complex, the need for these tools is increasing.
AI in Cybersecurity Market, By Vertical
The BFSI sector has the largest market share, given that this sector is more prone to cyber attacks and has strict regulations. There is a rise in the adoption of AI in banks and financial institutions for fraud prevention. There is also a rise in digital transactions.
REGION
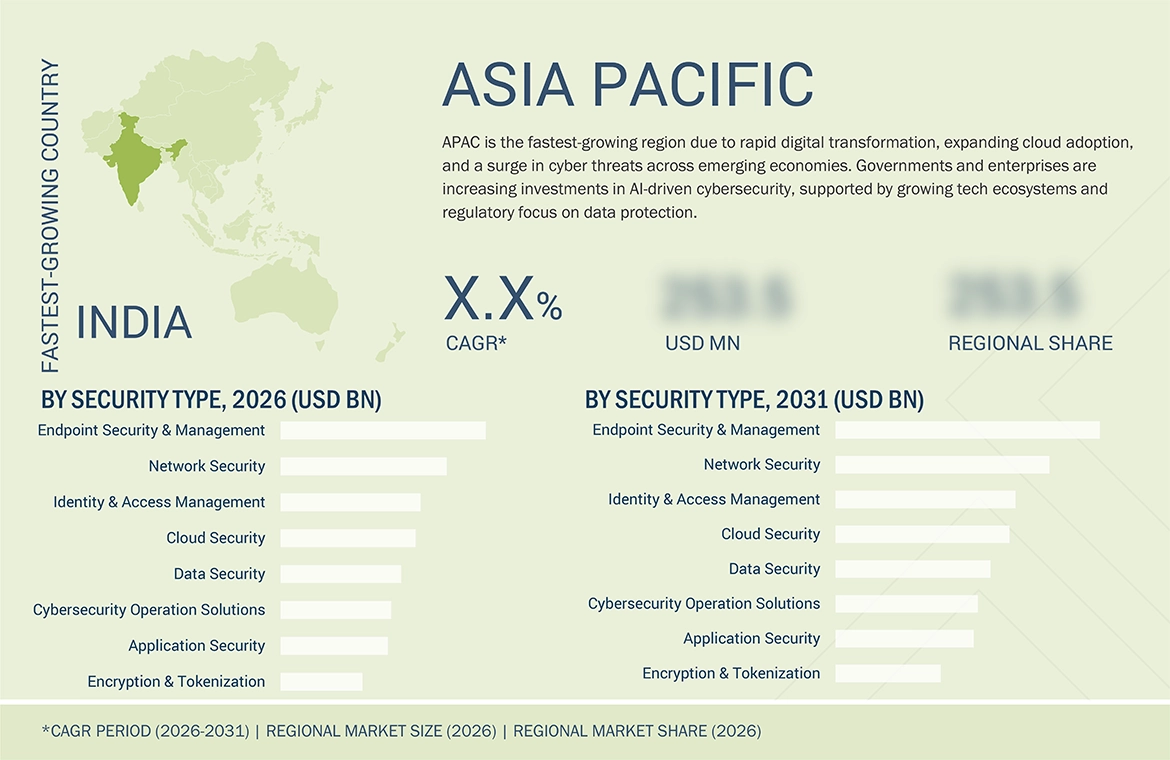
Asia Pacific is expected to be the fastest-growing region in the AI in cybersecurity market during the forecast period.
Asia Pacific is poised to outpace all others in the AI in cybersecurity market, according to projections. This surge is fueled by the region's swift digital transformation and the widespread embrace of AI by businesses. The growth is further bolstered by the escalating number and complexity of cyber threats. Asia Pacific is a major victim of cyber incidents worldwide, and the frequency of attacks shows no sign of abating. Organizations are investing in AI-driven security solutions to improve threat detection, protect critical infrastructure, and strengthen resilience across digital environments.
ARTIFICIAL INTELLIGENCE IN CYBERSECURITY MARKET: COMPANY EVALUATION MATRIX
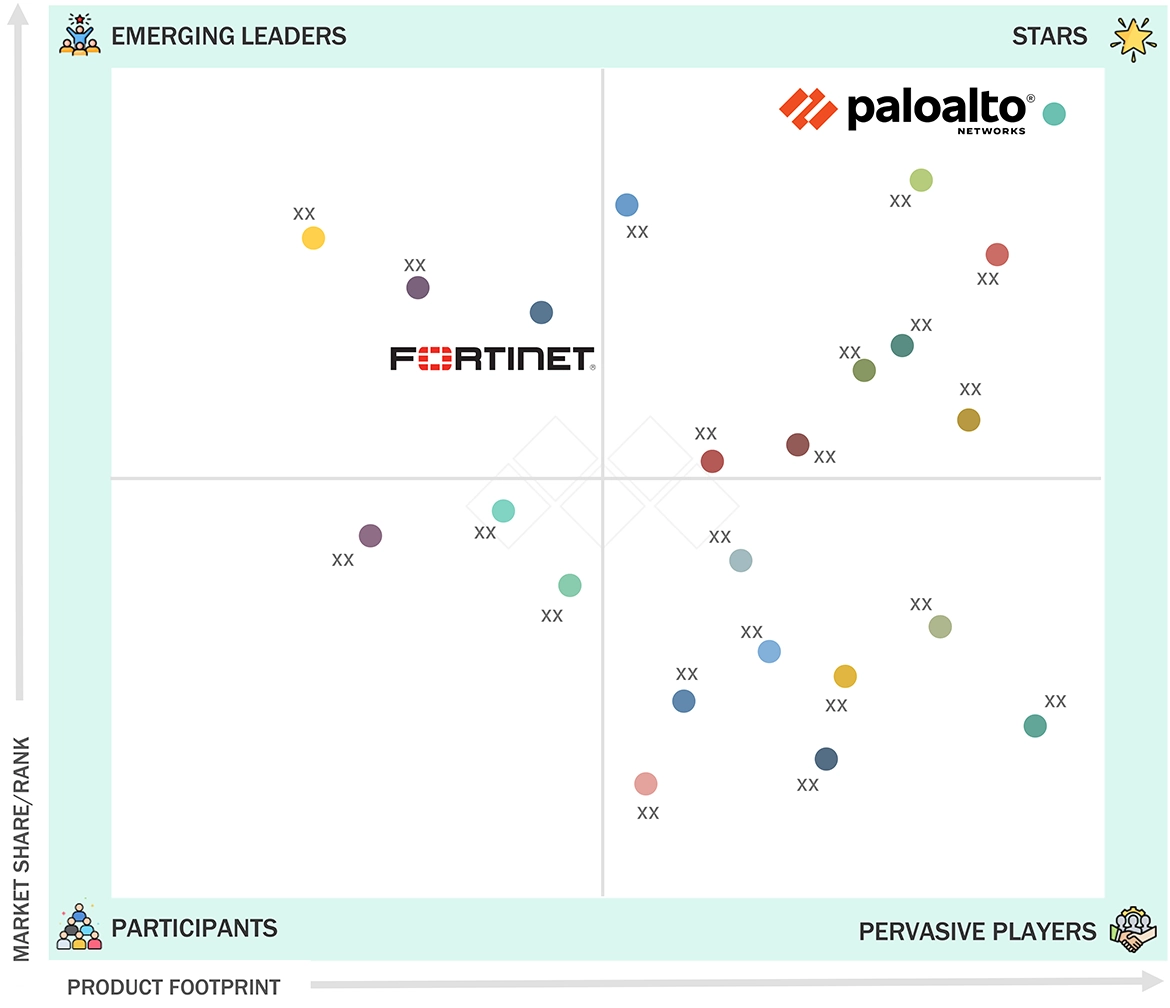
The Company Evaluation Matrix places Palo Alto Networks in the stars quadrant, driven by its strong AI-driven cybersecurity portfolio, integrated platform approach, and broad enterprise adoption. IBM is positioned in the emerging leaders quadrant as it continues to expand its AI-enabled security offerings, particularly in security operations and threat intelligence, supported by its focus on hybrid cloud and enterprise security solutions.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- NVIDIA (US)
- Intel (US)
- AMD (US)
- Samsung Electronics (South Korea)
- Micron Technology (US)
- IBM (US)
- AWS (US)
- Microsoft Corporation (US)
- Palo Alto Networks Inc. (US)
- Trellix (US)
- CrowdStrike (US)
- Gen Digital (US)
- BlackBerry (Canada)
- LexisNexis (US)
- Securonix Inc. (US)
- Sift Science (US)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 22.37 Billion |
| Market Size in 2026 (Value) | USD 25.53 Billion |
| Market Forecast in 2031 (Value) | USD 50.83 Billion |
| CAGR | GAGR of14.8% from 2026-2031 |
| Years Considered | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | USD Billion/Million |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Regions Covered | North America, Asia Pacific, Europe, Middle East & Africa, Latin America |
WHAT IS IN IT FOR YOU: ARTIFICIAL INTELLIGENCE IN CYBERSECURITY MARKET REPORT CONTENT GUIDE
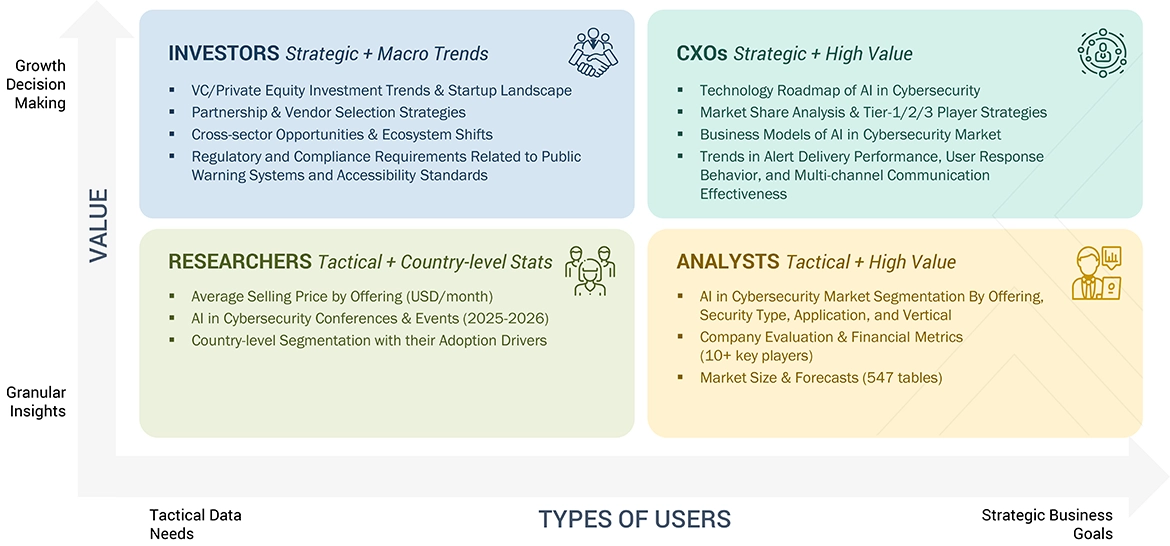
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Leading BFSI Firm |
|
|
| Leading Telecommunication Vendor |
|
|
RECENT DEVELOPMENTS
- March 2026 : Palo Alto Networks launched a secure browser designed for modern digital environments, increasing protection against emerging risks from advanced workflows. The move strengthens its platform strategy and focus on securing the evolving enterprise workspace.
- March 2026 : Microsoft introduced enhanced security features in 2026 through its Security Copilot, significantly increasing the ability of teams to detect threats in real-time and respond faster. The system increases efficiency by analyzing large volumes of security data and delivering actionable insights.
- February 2026 : Google Cloud introduced advanced security features for threat management, increasing the speed of threat detection, strengthening identity protection, and enhancing automated response capabilities.
Related Ecosystem
Cyber Security
- Cloud Security
- Biometric Systems
- Data Loss Prevention (DLP)
- Multi-Factor Authentication
- Security Analytics
- International Business Machines Corporation
- Cisco Systems, Inc.
- MITSUI BUSSAN SECURE DIRECTIONS INC
- MICROSOFT CORPORATION
- Allot Ltd.
Information System And Analytics
- Machine Learning
- Natural Language Processing (NLP)
- Sensors
- Software as A Service (SaaS)
- Data Loss Prevention (DLP)
- International Business Machines Corporation
- MICROSOFT CORPORATION
- Amazon.com, Inc.
- Oracle Corporation
Security And Surveillance
- Face Recognition
- Video Surveillance as A Service (VSaaS)
- Voice Recognition
- Fingerprint Recognition
- IRIS Recognition
- HONEYWELL INTERNATIONAL INC.
- Thales group
- HID-GLOBAL
- Lenovo
- AXIS COMMUNICATIONS
Key Takeaways
- Europe's AI cybersecurity market will nearly triple from $1,947.2M (2023) to $5,692.6M (2028), driven by regulatory mandates and rising threat sophistication.
- Europe's 23.9% CAGR outpaces the global average of 21.9%, positioning the region as a leading adopter of AI-powered security solutions.
- Regulatory frameworks such as GDPR and NIS2 Directive are primary catalysts for Europe's accelerated investment in AI cybersecurity technologies.
- Europe's financial services, healthcare, and critical infrastructure sectors are driving demand for advanced AI threat detection and automated response capabilities.
Artificial Intelligence in Cybersecurity Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2023 |
| Fastest Growing Segment | COMPUTER VISION (Technology) |
| Forecast Period | 2023–2028 |
| Growth Rate | CAGR of 21.9% from 2023 to 2028 |
| Largest Segment | SOLUTION (Offering) |
| Market Size Base Year (Billions) | ~USD 22.51 (2023) |
| Revenue Forecast (Billions) | ~USD 60.6 (2028) |
| Segments Covered | Offering, Type, Deployment Mode, Security Type, Infrastructure Security, Technology, Application, Subapplication |
Europe Artificial Intelligence in Cybersecurity Market Report Segmentation
8 segment dimensions are covered across the global market.
By Offering
- Hardware
- Services
- Solution
By Type
- Accelerators
- Application Program Interface
- Asic
- Consulting Services
- Deep Learning
- Deployment & Integration
- Fpga
- Gpu
- Machine Learning Framework
- Managed Services
- Mpu
- Network
- Neural Networks
- Other Processors
- Platforms
- Processors
- Professional Services
- Reinforcement Learning
- Software
- Storage
- Supervised Learning
- Support & Maintenance
- Tpu
- Unsupervised Learning
By Deployment Mode
- Cloud
- On-Premises
By Security Type
- Application Security
- Data Security
- Infrastructure Security
- Other Security Types
By Infrastructure Security
- Cloud Security
- Endpoint Security
- Network Security
- Other Infrastructure Security
By Technology
- Computer Vision
- Context-Aware Computing
- Machine Learning
- Natural Language Processing
By Application
- Anomaly Detection
- Automated Threat Intelligence
- Automation & Orchestration
- Chatbot Security
- Data Loss Prevention
- Facial Recognition
- Fraud Detection
- Identity & Access Management
- Image Recognition
- Intrusion Detection/Prevention System
- Named Entity Recognition (Ner)
- Natural Language Generation
- Natural Language Understanding
- Object Detection
- Other Applications
- Risk & Compliance Management
- Security & Vulnerability Management
- Security Surveillance Optimization
- Sentiment Analysis
- Text Analysis
- Threat Hunting
- Unified Threat Management
- Video Analysis
By Subapplication
- Access Policy Enforcement
- Audit Trail Generation
- Automated Compliance Auditing
- Bandwidth Management
- Bot Identification
- Breach Risk Prediction
- Configuration Management
- Content Discovery & Classification
- Data Encryption & Tokenization
- Data Leak Detection
- Endpoint Detection & Response (Edr)
- Gateway Antivirus
- Geolocation Analysis
- Identity Governance & Administration (Iga)
- Incident Response Planning
- Insider Threat Detection
- Multi-Factor Authentication (Mfa)
- Network Monitoring & Reporting
- Other Data Loss Prevention Applications
- Other Fraud Detection Applications
- Other Identity & Access Management Applications
- Other Risk & Compliance Management Applications
- Other Security & Vulnerability Management Applications
- Patch Management
- Pattern Recognition
- Phishing Detection
- Regulatory Compliance Reporting
- Security Information & Event Management (Siem)
- Single Sign-On (Sso)
- Spam Filtering
- Threat Modeling
- Transaction Monitoring
- User Activity Monitoring
- User Provisioning & Deprovisioning
- Vulnerability Scanning & Assessment
EUROPE: AI IN CYBERSECURITY MARKET, BY APPLICATION, 2023–2028
| Segment | 2023 | 2024 | 2025 | 2026 | 2027 | 2028 | CAGR (%) |
|---|---|---|---|---|---|---|---|
| DATA LOSS PREVENTION | 197.8 | 254.4 | 321.7 | 398.3 | 484.1 | 578.4 | 23.9 |
| FRAUD DETECTION | 845.6 | 1068.3 | 1326.8 | 1614.9 | 1929.8 | 2267.7 | 21.8 |
| IDENTITY & ACCESS MANAGEMENT | 1780.3 | 2280.7 | 2871.7 | 3542.7 | 4289.8 | 5106.7 | 23.5 |
| INTRUSION DETECTION/PREVENTION SYSTEM | 560.6 | 697.6 | 853.3 | 1022.8 | 1203.4 | 1392.3 | 20 |
| OTHER APPLICATIONS | 528.2 | 622.2 | 717 | 805.2 | 882 | 942.6 | 12.3 |
| RISK & COMPLIANCE MANAGEMENT | 937.4 | 1187.6 | 1479.2 | 1805.7 | 2164.1 | 2550.6 | 22.2 |
| SECURITY & VULNERABILITY MANAGEMENT | 593.4 | 747.1 | 924.8 | 1121.8 | 1336.1 | 1564.8 | 21.4 |
| UNIFIED THREAT MANAGEMENT | 259.8 | 319 | 384.8 | 454.6 | 526.9 | 600.1 | 18.2 |
| TOTAL | 5703.1 | 7176.8 | 8879.3 | 10766.2 | 12816.2 | 15003.3 | 21.3 |
Target Audience
- Cybersecurity Solution Vendors : Vendors need Europe-specific market data to develop localized product strategies, understand regulatory requirements, identify partnership opportunities, and prioritize European market expansion investments.
- Enterprise IT & Security Leaders : CISOs and IT directors require regional market insights to benchmark cybersecurity spending, evaluate AI solution adoption trends, and make informed technology investment decisions aligned with European compliance mandates.
- Investment & Private Equity Firms : Investors need detailed European market forecasts and growth drivers to identify high-potential cybersecurity AI companies, assess market attractiveness, and evaluate acquisition and funding opportunities.
- Government & Regulatory Bodies : European policymakers and regulatory agencies require market intelligence to understand AI cybersecurity adoption rates, assess digital security infrastructure readiness, and inform digital security policy development.
- Management Consulting Firms : Consultants need Europe-focused market data to support client digital transformation strategies, cybersecurity roadmap development, and technology vendor selection engagements across European enterprises.
Key Companies in the Europe Artificial Intelligence in Cybersecurity Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| DEUTSCHE TELEKOM AG | Germany | Public Company | Mobile services (retail and wholesale),Fixed-network & broadband services,ICT, cloud, and digital solutions, |
| ALTRAN | France | Private Company | Engineering and R&D services,Organization and IT systems consulting,Embedded systems and next-gen connectivity projects, |
| LARSEN & TOUBRO LTD. | India | Public Company | Infrastructure Projects (buildings, transport, heavy civil, T&D, water, minerals & metals),Energy Projects (clean energy, oil & gas, refineries, petrochemicals, offshore wind, CarbonLite),Hi-Tech Manufacturing (nuclear, green hydrogen, defense, aerospace, precision and electronics, electrolysers), |
| PARSONS | United States | Public Company | Federal Solutions – Cyber, Intelligence, and Electronic Warfare,Federal Solutions – Space, Missile Defense, and C2,Federal Solutions – Border, Biometrics, and Environmental Remediation, |
| ATOS SE | France | Public Company | Infrastructure & Cloud Managed Services,Digital Workplace & End-User Services,Business & Platform Integration / Applications, |
| NVIDIA | United States | Public Company | Data Center AI Compute & Networking,Gaming GPUs (GeForce),Professional Visualization (RTX/Workstations), |
| INTEL | United States | Public Company | Client Computing Group (client and commercial CPUs, discrete client GPUs, edge and connectivity),Data Center and AI (server CPUs, discrete GPUs, networking),Intel Foundry (wafer fabrication, substrates, related services), |
| AMD | United States | Public Company | Data Center (EPYC, Instinct, Pensando, Alveo, AI infrastructure),Client (Ryzen, Ryzen AI, desktop and mobile CPUs),Gaming and Graphics (Radeon, Radeon Pro, semi-custom SoCs), |
| SAMSUNG ELECTRONICS CO., LTD | South Korea | Public Company | Smartphones, tablets, wearables, and accessories (DX mobile),Semiconductors (memory, foundry, system LSI, toll processing),TVs, displays, and digital signage (DX + SDC), |
| MICRON TECHNOLOGY | United States | Public Company | DRAM (cloud, data center, PC, graphics, mobile, automotive, embedded),NAND Components & Managed NAND (including MCPs, UFS, eMMC),SSD (data center, client, automotive & industrial), |
| IBM | United States | Public Company | Software (Hybrid Cloud and AI Platforms),Consulting,Infrastructure, |
| MICROSOFT CORPORATION | United States | Public Company | Productivity and Business Processes,Intelligent Cloud,Personal Computing, |
| PALO ALTO NETWORKS | United States | Public Company | Network Security (Strata, VM-Series, CN-Series, subscriptions),Cloud Security (Prisma Cloud, Code to Cloud, Prisma Access SASE),Security Operations (Cortex XSIAM, XDR, XSOAR, Xpanse, Unit 42), |
| CROWDSTRIKE | United States | Public Company | Endpoint & Cloud Workload Protection (Falcon core),Managed Security & Threat Intelligence,Identity, Data Protection & SaaS Security, |
| GEN DIGITAL | United States | Public Company | Consumer endpoint security & performance (Norton, Avast, AVG, Avira, CCleaner),Identity protection & restoration (LifeLock, MoneyLion-linked, reputation services),Online privacy & VPN, |
DEUTSCHE TELEKOM AG
Deutsche Telekom AG is a German public telecommunications company founded in 1995 with 196,586 employees.
ALTRAN
Altran is a French private engineering and consulting company founded in 1970 with 50,124 employees.
LARSEN & TOUBRO LTD.
Larsen & Toubro Ltd. is an Indian public multinational conglomerate founded in 1938 with 55,662 employees.
PARSONS
Parsons is a publicly traded American engineering and construction company founded in 1944 with 21,000 employees.
ATOS SE
Atos SE is a French public information technology and consulting company founded in 1997.
NVIDIA
NVIDIA is an American public technology company founded in 1993 with 42,000 employees.
INTEL
Intel is an American public semiconductor company founded in 1968 with 85,100 employees.
AMD
AMD is an American public semiconductor company founded in 1969 with 31,000 employees.
SAMSUNG ELECTRONICS CO., LTD
Samsung Electronics Co., Ltd. is a South Korean public electronics conglomerate founded in 1969 with 128,735 employees.
MICRON TECHNOLOGY
Micron Technology is an American public semiconductor and memory company founded in 1978 with 53,000 employees.
IBM
IBM is an American public technology and consulting company founded in 1911 with 264,300 employees.
MICROSOFT CORPORATION
Microsoft Corporation is an American public software and technology company founded in 1975 with 228,000 employees.
PALO ALTO NETWORKS
Palo Alto Networks is an American public cybersecurity company founded in 2005 with 21,491 employees.
CROWDSTRIKE
CrowdStrike is an American public cybersecurity company founded in 2011 with 11,157 employees.
GEN DIGITAL
Gen Digital is an American public cybersecurity and digital safety company founded in 1982 with 3,900 employees.
Countries within Europe - compare and drill down
| Country | 2025 size (native) |
|---|
Country market size visualization
Reasons to Buy this Report
- Regional Market Sizing & Forecasts : Access precise valuation data for Europe's AI cybersecurity market with detailed 5-year projections, enabling accurate budget allocation and investment planning specific to European market dynamics.
- Regulatory Compliance Insights : Understand how GDPR, NIS2 Directive, and other European regulations drive AI cybersecurity adoption, helping organizations align technology investments with mandatory compliance requirements.
- Competitive Landscape Analysis : Identify leading European and global vendors, their market positioning, and strategic initiatives tailored to European enterprises, supporting vendor selection and partnership decisions.
- Sector-Specific Growth Opportunities : Discover high-growth segments within European financial services, healthcare, government, and critical infrastructure sectors where AI cybersecurity solutions are experiencing accelerated deployment.
- Strategic Market Entry Planning : Leverage Europe-specific market intelligence to develop go-to-market strategies, identify key customer segments, and optimize resource allocation for European market penetration and expansion.
Frequently asked questions
What is the projected size of Europe's AI cybersecurity market by 2028?
Europe's AI cybersecurity market is projected to reach $5,692.6 million by 2028, growing from $1,947.2 million in 2023 at a CAGR of 23.9%.
How does Europe's AI cybersecurity growth compare to global trends?
Europe's 23.9% CAGR exceeds the global average of 21.9%, indicating that Europe is adopting AI cybersecurity solutions faster than other regions worldwide.
What regulatory factors are driving Europe's AI cybersecurity market growth?
Europe's stringent regulatory frameworks, including GDPR and the NIS2 Directive, mandate advanced cybersecurity measures that accelerate adoption of AI-powered security solutions across member states.
Which sectors in Europe are leading AI cybersecurity adoption?
Europe's financial services, healthcare, and critical infrastructure sectors are primary drivers of AI cybersecurity investment due to their exposure to sophisticated cyber threats and regulatory compliance requirements.
What AI capabilities are most in demand across Europe's cybersecurity market?
Europe's organizations prioritize AI-driven threat detection, anomaly identification, automated response systems, and behavioral analytics to combat ransomware, data breaches, and emerging threat vectors.
RESEARCH METHODOLOGY
Get the Full Artificial Intelligence in Cybersecurity Market Report
Full forecast, segment splits, and company analysis for all Artificial Intelligence in Cybersecurity Market.
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
