Spain Automotive Composites Market (2026-2031)
The Spain Automotive Composites Market was valued at $142.7 Million in 2026 and projected to reach to $222.2 Million by 2031, representing a compound annual growth rate of 9.3%. Spain's automotive composites market is poised for sustained expansion driven by the country's commitment to EU environmental standards and the automotive industry's shift toward lightweight materials.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Spain Automotive Composites Market Trends and Insights
- This 9.3% compound annual growth rate reflects Spain's strategic position within Europe's automotive manufacturing ecosystem and increasing adoption of lightweight composite materials to meet fuel efficiency and emissions regulations.
- Spain's automotive sector, anchored by major OEM facilities and Tier-1 suppliers, is driving demand for advanced composite solutions in body panels, structural components, and interior applications. The Spanish market benefits from the country's established automotive production base and proximity to key European markets.
- Spain's commitment to electrification and sustainability is accelerating composite adoption, as manufacturers seek to reduce vehicle weight and improve battery efficiency in electric vehicles.
- Between 2026 and 2031, Spain is expected to capture growing market share as regional supply chains strengthen and local composite manufacturers expand capacity to support both traditional and EV platforms..
Key Market Statistics
- CAGR (2026-2031) 9.3% CAGR
- Market Size, 2026 ~USD 142.7 Million
- Forecast, 2031 ~USD 222.2 Million
- Country Spain
Spain Automotive Composites Market Overview
Market Valuation Growth :
Spain's automotive composites market is valued at USD 142.7 million in 2026 and is projected to reach USD 222.2 million by 2031, representing a robust 9.3% CAGR over the forecast period.
EU Regulatory Compliance Driver :
Spain's automotive manufacturers are increasingly adopting lightweight composite materials to comply with stringent EU emissions regulations and fuel efficiency standards, positioning the country as a key compliance hub.
Strategic Manufacturing Hub :
Spain's established automotive manufacturing ecosystem, including major OEM facilities and Tier-1 suppliers, creates a strong foundation for composite material integration and supply chain development.
Lightweight Material Adoption :
Growing demand for weight reduction in vehicles to improve performance and reduce carbon footprint is accelerating composite material adoption across Spain's automotive production sector.
Spain Automotive Composites Market Dynamics
- The 9.3% CAGR reflects increasing investments in composite manufacturing capabilities and growing partnerships between Spanish OEMs and composite material suppliers.
- Spain's strategic location within Europe's automotive supply chain and its established manufacturing infrastructure position it favorably for continued market penetration. Looking ahead, Spain's market growth will be supported by rising electrification trends requiring lighter vehicle structures for improved battery efficiency, coupled with ongoing regulatory pressure to reduce emissions.
- Investment in advanced composite technologies and localized production facilities will further strengthen Spain's competitive position within the European automotive composites landscape through 2031..
Market Ecosystem

AUTOMOTIVE COMPOSITES MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Utilizes glass fiber and carbon fiber composites in battery enclosures, body structures, underbody shields, and interior components to reduce vehicle weight and improve EV efficiency | Extends driving range | Improves energy efficiency, enhances crash protection | Reduces overall vehicle weight |
 |
Incorporates carbon fiber-reinforced composites in passenger cells, roof systems, body structures, and lightweight EV platforms | Improves vehicle performance | Crash resistance, battery efficiency | Fuel economy while reducing emissions |
 |
Uses advanced composites in body panels, structural components, battery housings, and luxury vehicle applications | Enables lightweighting | Enhances structural rigidity | Improves safety performance | Supports vehicle electrification |
 |
Deploys glass fiber and thermoplastic composites in interior components, exterior panels, and lightweight structural applications across passenger and hybrid vehicles | Reduces vehicle mass | Improves fuel efficiency | Lowers manufacturing costs | Enhances durability |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Automotive Advance Technologies
- Battery Electric Vehicle (BEV)
- Light Commercial Vehicles (LCVs)
- Fuel Cell Electric Vehicle (FCEV)
- Hybrid Electric Vehicle (HEV)
- Internal Combustion Engine (ICE)
- BOSCH LIMITED
- Continental ag
- Visteon Corporation
- DENSO Corporation
- ZF FRIEDRICHSHAFEN AG
Fibers And Composites
- Polyetheretherketone (PEEK)
- Polyphenylene Sulfide (PPS)
- Epoxy Resin
- Polycarbonate
- Polyester Resin
- Toray Industries, Inc.
- Teijin Limited
- Hexcel Corporation
- Sgl carbon se
- Solvay sa
Speciality Chemicals
- Corrosion Inhibitors
- Polyetheretherketone (PEEK)
- Acrylonitrile Butadiene Styrene (ABS)
- Epoxy Resin
- Polycarbonate
- Basf se
- DOW CHEMICAL COMPANY
- Evonik industries ag
- Clariant ag.
- Solvay sa
Key Takeaways
- Spain's automotive composites market is valued at USD 142.7 million in 2026 and will reach USD 222.2 million by 2031, representing a 9.3% CAGR.
- Spain's established OEM and Tier-1 supplier base is a primary driver of composite material demand across body, structural, and interior applications.
- EV electrification initiatives in Spain are accelerating lightweight composite adoption to improve battery efficiency and vehicle range.
- Spain's regional supply chain integration and manufacturing proximity to Western Europe position the country as a key composite hub through 2031.
Automotive Composites Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | RESIN TRANSFER MOLDING (Manufacturing Process) |
| Forecast Period | 2026-2031 |
| Growth Rate | CAGR of 12.5% from 2026 to 2031 |
| Largest Segment | NON-ELECTRIC (Vehicle Type) |
| Market Size Base Year (Billions) | ~USD 10.74 (2026) |
| Revenue Forecast (Billions) | ~USD 19.35 (2031) |
| Segments Covered | Application, Fiber Type, Manufacturing Process, Resin Type, Vehicle Type |
Spain Automotive Composites Market Report Segmentation
5 segment dimensions are covered across the global market.
By Application
- Battery Enclosures
- Exterior
- Interior
- Powertrain & Chassis
By Fiber Type
- Carbon Fiber
- Glass Fiber
- Other Fiber Types
By Manufacturing Process
- Compression Molding
- Injection Molding
- Other Manufacturing Processes
- Resin Transfer Molding
By Resin Type
- Epoxy
- Other Thermoplastic Resin Types
- Other Thermoset Resin Types
- Polyamide
- Polyester
- Polyphenylene Sulfide (Pps)
- Polypropylene
- Thermoplastic
- Thermoset
- Vinyl Ester
By Vehicle Type
- Electric
- Non-Electric
Target Audience
- Automotive OEMs & Manufacturers : Spanish and international automotive manufacturers need Spain-specific market data to optimize composite material sourcing, production planning, and compliance with EU regulations affecting their Spanish operations.
- Composite Material Suppliers : Composite resin, fiber, and finished component suppliers require detailed Spain market insights to identify growth opportunities, assess demand from Spanish OEMs, and plan localized production investments.
- Investment & Private Equity Firms : Investors evaluating opportunities in Spain's automotive supply chain need market-specific data on growth trajectories, regulatory drivers, and competitive dynamics to assess investment viability and returns.
- Automotive Tier-1 & Tier-2 Suppliers : Spanish and European suppliers serving automotive manufacturers require market forecasts and growth drivers specific to Spain to align capacity planning, R&D investments, and customer engagement strategies.
- Business Development & Strategy Teams : Corporate strategy, M&A, and business development professionals need Spain-focused market intelligence to identify acquisition targets, partnership opportunities, and market expansion strategies in the automotive composites sector.
Reasons to Buy this Report
- Spain-Specific Market Sizing : Access precise valuation data for Spain's automotive composites market with verified 2026 baseline (USD 142.7M) and 2031 forecast (USD 222.2M), enabling accurate business planning and investment decisions.
- Regulatory & Compliance Insights : Understand how EU emissions regulations and fuel efficiency mandates are specifically driving composite adoption in Spain's automotive sector, critical for compliance-focused manufacturers and suppliers.
- Supply Chain Opportunity Mapping : Identify growth opportunities within Spain's established automotive manufacturing ecosystem, including OEM partnerships, Tier-1 supplier relationships, and localized production facility development.
- Competitive Positioning Strategy : Benchmark your business against Spain's 9.3% CAGR growth trajectory and understand market dynamics specific to Spanish automotive manufacturers to refine competitive strategies.
- Investment & Expansion Planning : Make informed decisions on market entry, facility expansion, or partnership development in Spain with comprehensive data on market growth drivers and manufacturing infrastructure maturity.
Frequently asked questions
What is the current size of Spain's automotive composites market?
Spain's automotive composites market is valued at USD 142.7 million in 2026 and is projected to grow to USD 222.2 million by 2031.
What is the growth rate for Spain's automotive composites market?
Spain's automotive composites market is expected to grow at a compound annual growth rate (CAGR) of 9.3% from 2026 to 2031.
Which applications drive composite demand in Spain's automotive sector?
Spain's automotive composites are primarily used in body panels, structural components, interior trim, and EV battery enclosures, driven by OEM and Tier-1 supplier requirements.
How is Spain's EV transition affecting the composites market?
Spain's shift toward electric vehicles is accelerating composite adoption, as manufacturers use lightweight materials to reduce vehicle weight and extend battery range.
What competitive advantages does Spain hold in automotive composites?
Spain benefits from an established automotive manufacturing base, proximity to Western European markets, skilled workforce, and integrated supply chains supporting composite production and integration.
RESEARCH METHODOLOGY
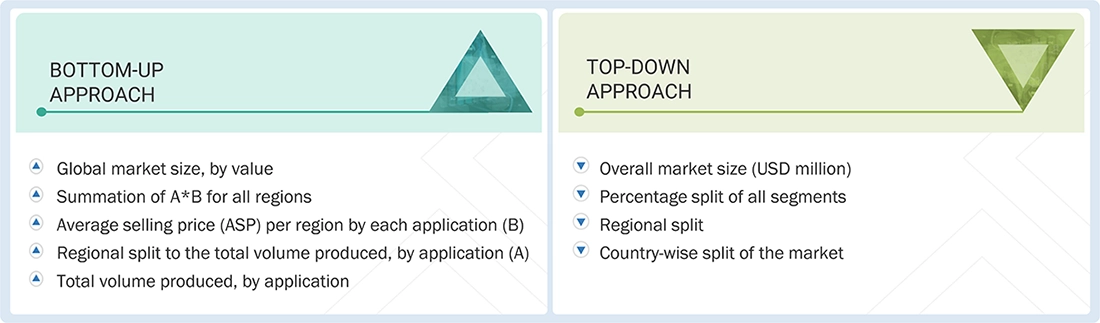
The study involves two major activities in estimating the current market size for the automotive composites market. Exhaustive secondary research was done to collect information on the market, peer market, and parent market. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. After that, market breakdown and data triangulation were used to estimate the market size of segments and subsegments.
Secondary Research
Secondary sources referred to for this research study include financial statements of companies offering automotive composites and information from various trade, business, and professional associations. Secondary research has been used to obtain critical information about the industry’s value chain, the total pool of key players, market classification, and segmentation according to industry trends to the bottom-most level and regional markets. The secondary data was collected and analyzed to arrive at the overall size of the automotive composites market, which was validated by primary respondents.
Primary Research
Extensive primary research was conducted after obtaining information regarding the automotive composites market scenario through secondary research. Several primary interviews were conducted with market experts from both the demand and supply sides across major countries of North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America. Primary data was collected through questionnaires, emails, and telephonic interviews. The primary sources from the supply side included various industry experts, such as chief experience officers (CXOs), vice presidents (VPs), business development/marketing directors, product development/innovation teams, related key executives from the automotive composites industry, system integrators, component providers, distributors, and key opinion leaders. Primary interviews were conducted to gather insights such as market statistics, data on revenue collected from the products and services, market breakdowns, market size estimations, market forecasting, and data triangulation. Primary research helped in understanding the various trends related to fiber type, resin type, manufacturing process, application, vehicle type, and region. Stakeholders from the demand side, such as CIOs, CTOs, CSOs, and installation teams of the customers/end users who are seeking automotive Composites services, were interviewed to understand the buyer’s perspective on the suppliers, products, component providers, and their current usage of automotive composites and future outlook of their business, which will affect the overall market.
Breakup of Primary Research
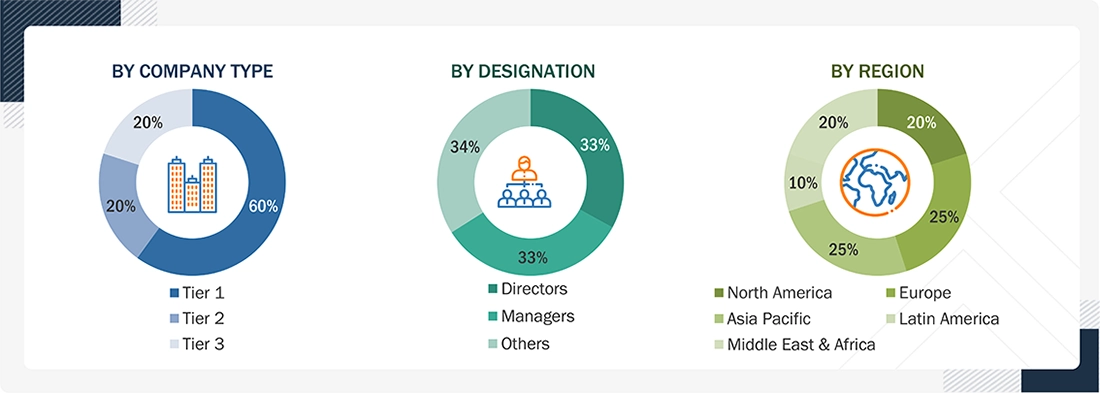
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The research methodology used to estimate the size of the automotive composites market includes the following details. The market size was determined from the demand side. The market was upsized based on the demand for automotive composites in different applications at the regional level. Such procurements provide information on the demand aspects of the automotive composites industry for each application. For each application, all possible segments of the automotive Composites market were integrated and mapped.
Automotive Composites Market : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall size from the market size estimation process explained above, the total market was split into several segments and subsegments. The data triangulation and market breakdown procedures explained below were implemented, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics for various market segments and subsegments. The data was triangulated by studying various factors and trends from the demand and supply sides. Along with this, the market size was validated using both the top-down and bottom-up approaches.
Market Definition
Automotive composites are advanced materials made by combining reinforcing fibers such as glass, carbon, natural, or aramid fibers with thermoset or thermoplastic resins. These materials offer high strength-to-weight ratios, corrosion resistance, and design flexibility, making them ideal for applications such as body panels, battery enclosures, chassis components, and structural reinforcements. By reducing vehicle weight while maintaining performance and safety, automotive composites help improve fuel efficiency, extend EV range, and support sustainability goals.
Key Stakeholders
- Automotive composites manufacturers
- Automotive composites distributors and suppliers
- Universities, governments, and research organizations
- Associations and industrial bodies
- R&D institutes
- Environmental support agencies
- Investment banks and private equity firms
- Research and consulting firms
Report Objectives
- Automotive composites manufacturers
- Automotive composites distributors and suppliers
- Universities, governments, and research organizations
- Associations and industrial bodies
- R&D institutes
- Environmental support agencies
- Investment banks and private equity firms
- Research and consulting firms
Available customizations:
MarketsandMarkets offers the following customizations for this market report:
- Additional country-level analysis of the automotive composites market
Product Analysis
- Product matrix, which provides a detailed comparison of the product portfolio of each company’s market
Get the Full Automotive Composites Market Report
Full forecast, segment splits, and company analysis for all Automotive Composites Market.
- Canada Automotive Composites Market
- US Automotive Composites Market
- Germany Automotive Composites Market
- France Automotive Composites Market
- UK Automotive Composites Market
- Italy Automotive Composites Market
- Russia Automotive Composites Market
- Belgium Automotive Composites Market
- Mexico Automotive Composites Market
- Brazil Automotive Composites Market
- China Automotive Composites Market
- Japan Automotive Composites Market
- India Automotive Composites Market
- South Korea Automotive Composites Market
- Australia Automotive Composites Market
- South Africa Automotive Composites Market
- Rest Of Europe Automotive Composites Market
- Rest Of Asia Pacific Automotive Composites Market
- Rest Of Latin America Automotive Composites Market
- GCC Countries Automotive Composites Market
- -Rest Of GCC Countries Automotive Composites Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report