Spain Cancer/Tumor Profiling Market (2022-2027)
The Spain Cancer/Tumor Profiling Market was valued at $73.8 Million in 2022 and projected to reach to $85.9 Million by 2027, representing a compound annual growth rate of 3.1%. Spain's cancer/tumor profiling market is positioned for steady growth as healthcare providers increasingly recognize the clinical and economic value of precision oncology.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Spain Cancer/Tumor Profiling Market Trends and Insights
- This moderate growth trajectory reflects Spain's established healthcare infrastructure and increasing adoption of precision oncology diagnostics.
- Spain's market expansion is driven by rising cancer incidence, growing investment in genomic testing capabilities, and integration of tumor profiling into clinical treatment protocols across Spanish healthcare institutions. The Spanish cancer/tumor profiling market benefits from strong regulatory frameworks and reimbursement policies that support molecular diagnostics.
- Spain's healthcare system continues to prioritize personalized medicine approaches, with tumor profiling becoming increasingly standard in oncology practice.
- Between 2022 and 2027, Spain is expected to see steady market maturation as laboratories expand profiling services and clinicians adopt genomic insights for treatment selection..
Key Market Statistics
- CAGR (2022-2027) 3.1% CAGR
- Market Size, 2022 ~USD 73.8 Million
- Forecast, 2027 ~USD 85.9 Million
- Country Spain
Spain Cancer/Tumor Profiling Market Overview
Market Valuation :
Spain's cancer/tumor profiling market reached USD 73.8 million in 2022, with projections to grow to USD 85.9 million by 2027, demonstrating steady expansion in precision oncology diagnostics.
Growth Rate :
The Spanish market exhibits a CAGR of 3.1% through 2027, reflecting moderate but consistent growth driven by healthcare infrastructure advancement and increased adoption of molecular profiling technologies.
Healthcare Infrastructure :
Spain's established healthcare system and universal coverage model support widespread implementation of advanced cancer profiling technologies across public and private oncology centers.
Rising Cancer Incidence :
Increasing cancer prevalence in Spain drives demand for precision diagnostics and personalized treatment approaches, positioning tumor profiling as essential for modern oncology practice.
Spain Cancer/Tumor Profiling Market Dynamics
- The Spanish healthcare system's commitment to modernization and integration of advanced diagnostics supports market expansion, particularly in genomic sequencing and molecular pathology services.
- Rising cancer incidence rates and aging demographics further accelerate adoption of tumor profiling across Spanish hospitals and diagnostic laboratories. The market will benefit from growing reimbursement support, collaborative research initiatives, and investment in oncology infrastructure.
- Spanish pharmaceutical companies and diagnostic providers are expanding their precision medicine portfolios, while international players strengthen their presence.
- By 2027, tumor profiling is expected to become standard practice in Spanish oncology centers, driving sustained market growth and improved patient outcomes through personalized treatment strategies..
Market Ecosystem
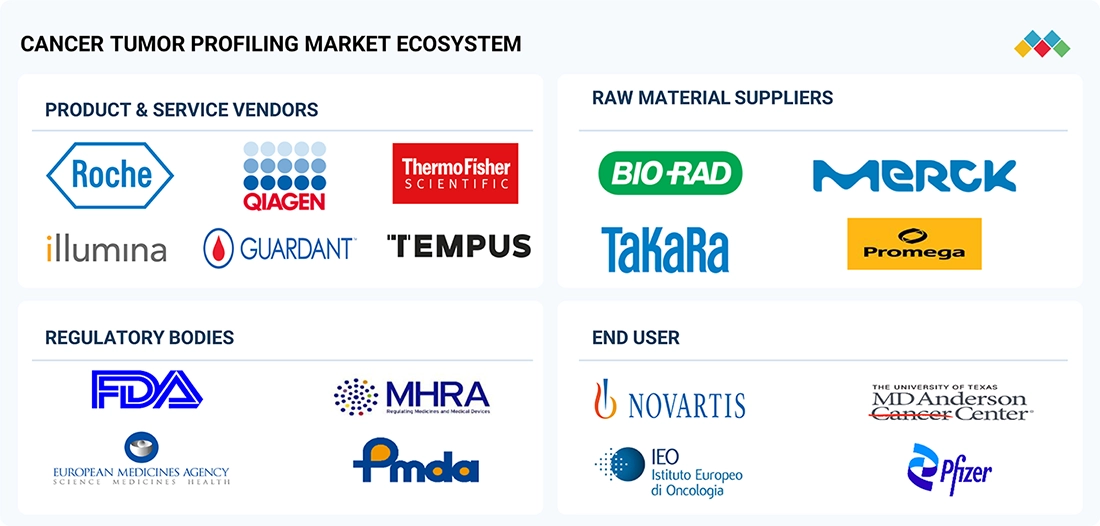
CANCER TUMOR PROFILING MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Through Foundation Medicine and Roche Diagnostics, the company provides comprehensive genomic profiling (CGP) solutions using tissue and liquid biopsy-based testing to identify actionable biomarkers and support companion diagnostic applications for targeted therapies and immunotherapies. | Enables accurate patient stratification, improves therapy selection, supports biomarker-driven treatment decisions, and accelerates adoption of precision oncology workflows. |
 |
Provides next-generation sequencing (NGS) platforms and oncology-focused assays, including TruSight Oncology Comprehensive, to enable multi-gene tumor profiling and detection of clinically relevant biomarkers across solid tumors. | Supports comprehensive biomarker identification, improves laboratory testing scalability, enables decentralized genomic testing, and supports pharmaceutical companion diagnostic development. |
 |
Provides liquid biopsy-based tumor profiling solutions, including Guardant360 CDx and related genomic testing platforms, for detecting actionable genomic alterations, monitoring treatment response, and supporting therapy selection in advanced cancers. | Enables minimally invasive testing, facilitates repeat monitoring, identifies resistance mechanisms, and expands access to precision oncology testing for patients with limited tissue availability. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Key Takeaways
- Spain's cancer/tumor profiling market reached USD 73.8 million in 2022 with projected growth to USD 85.9 million by 2027.
- Spain demonstrates a 3.1% CAGR, reflecting steady but moderate market expansion driven by precision oncology adoption.
- Spain's established healthcare system and reimbursement policies support integration of tumor profiling into standard oncology care.
- Spain's market growth is underpinned by rising cancer prevalence and increasing laboratory capacity for genomic testing services.
Cancer/Tumor Profiling Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2022 |
| Fastest Growing Segment | NEXT-GENERATION SEQUENCING (Technology) |
| Forecast Period | 2022-2027 |
| Growth Rate | CAGR of 10.6% from 2022 to 2027 |
| Largest Segment | RESEARCH APPLICATIONS (Application) |
| Market Size Base Year (Billions) | ~USD 9.67 (2022) |
| Revenue Forecast (Billions) | ~USD 16 (2027) |
| Segments Covered | Technology, Cancer Type, Biomarker Type, Application, Type |
Spain Cancer/Tumor Profiling Market Report Segmentation
5 segment dimensions are covered across the global market.
By Technology
- Immunoassays
- In Situ Hybridization
- In-Situ Hybridization
- Mass Spectrometry
- Microarrays
- Next-Generation Sequencing
- Other Technologies
- Others Technologies
- Polymerase Chain Reaction
By Cancer Type
- Breast Cancer
- Colorectal Cancer
- Lung Cancer
- Melanoma Cancer
- Other Cancers
- Prostate Cancer
By Biomarker Type
- Genetic Biomarkers
- Genomic Biomarkers
- Other Biomarkers
- Protein Biomarkers
By Application
- Clinical Applications
- Research Applications
By Type
- Biomarker Discovery
- Diagnostics
- Monitoring & Treatment
- Personalized Medicine
- Prognostics
- Screening
Target Audience
- Diagnostic Laboratory Operators : Spanish diagnostic centers need market intelligence to assess growth opportunities, benchmark performance, and plan investments in tumor profiling capabilities and molecular testing infrastructure.
- Pharmaceutical & Biotech Companies : Companies developing oncology drugs and companion diagnostics require Spain-specific market data to identify patient populations, plan clinical trials, and establish partnerships with Spanish healthcare providers.
- Hospital & Oncology Center Administrators : Spanish hospital leaders need market insights to justify investments in precision oncology programs, evaluate vendor solutions, and align cancer care strategies with market trends and patient demand.
- Medical Device & IVD Manufacturers : Manufacturers of cancer profiling platforms and diagnostic equipment require Spain market analysis to assess commercial viability, competitive positioning, and regulatory pathways for market penetration.
- Healthcare Investors & Consultants : Investment firms and management consultants need detailed Spain market data to evaluate acquisition targets, assess portfolio companies, and identify emerging opportunities in precision oncology.
Reasons to Buy this Report
- Market Size & Growth Projections : Access precise valuation data for Spain's cancer profiling market with detailed forecasts through 2027, enabling accurate financial planning and investment decisions for market entry or expansion.
- Competitive Landscape Analysis : Understand Spain-specific market dynamics, key players, and competitive positioning to identify opportunities for differentiation and strategic partnerships within the Spanish oncology diagnostics sector.
- Healthcare Policy & Reimbursement Insights : Gain detailed knowledge of Spanish healthcare regulations, reimbursement frameworks, and clinical adoption drivers to navigate market entry and optimize pricing strategies for tumor profiling services.
- Regional Growth Drivers : Identify Spain-specific factors including rising cancer incidence, aging demographics, and healthcare infrastructure investments that create targeted opportunities for precision oncology solutions.
- Strategic Decision Support : Leverage comprehensive Spain market intelligence to support product development, market positioning, and go-to-market strategies tailored to Spanish healthcare providers and patient populations.
Frequently asked questions
What is the current size of Spain's cancer/tumor profiling market?
Spain's cancer/tumor profiling market was valued at USD 73.8 million in 2022 and is expected to reach USD 85.9 million by 2027.
What is the projected growth rate for Spain's cancer/tumor profiling market?
Spain's cancer/tumor profiling market is projected to grow at a CAGR of 3.1% from 2022 to 2027.
What factors are driving growth in Spain's cancer/tumor profiling market?
Spain's market growth is driven by rising cancer incidence, increased adoption of precision oncology, expanding laboratory capabilities, and supportive reimbursement policies within the Spanish healthcare system.
How does Spain's market compare to global cancer/tumor profiling trends?
Spain's 3.1% CAGR represents a more conservative growth trajectory compared to the global market CAGR of 10.6%, reflecting Spain's mature healthcare infrastructure and established diagnostic adoption.
What role does Spain's healthcare system play in tumor profiling adoption?
Spain's centralized healthcare system, regulatory frameworks, and reimbursement policies facilitate standardized adoption of tumor profiling across oncology centers, supporting market expansion through clinical integration.
RESEARCH METHODOLOGY
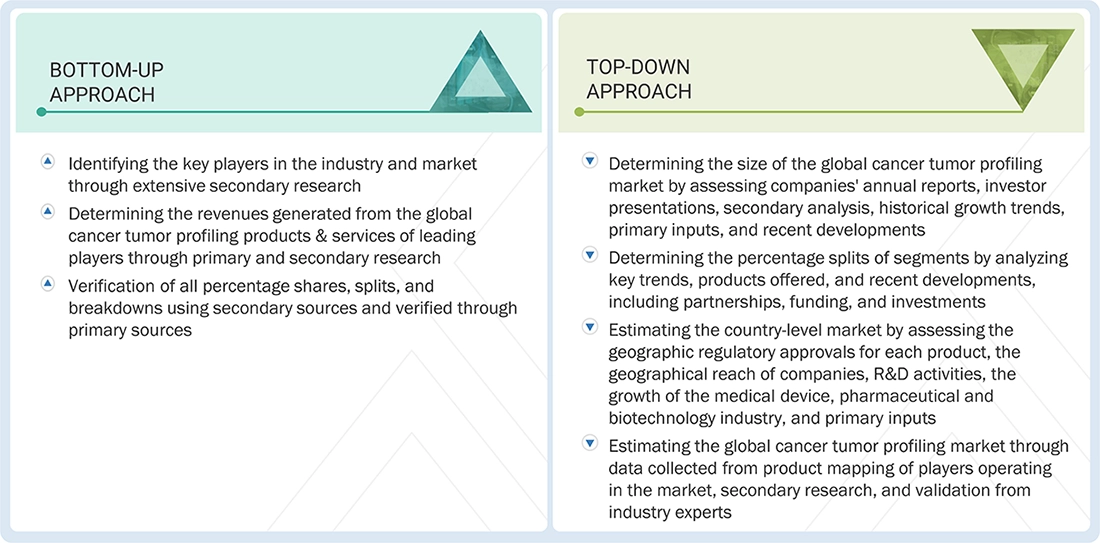
This study involved four major activities in estimating the current size of the cancer tumor profiling market. Exhaustive secondary research was conducted to collect information on the market, its peer markets, and the broader precision-oncology ecosystem. The findings, assumptions, and market sizing estimates were then validated through primary research with participants across the value chain. Both top-down and bottom-up approaches were used to estimate the complete market. Following this, data triangulation was applied to finalize the market size and the values of individual segments and subsegments.
Secondary Research
Secondary research was used to identify and gather information for this extensive technical, market-oriented, and commercial study. Public-sector sources included the US Food and Drug Administration (FDA), National Institutes of Health (NIH), National Cancer Institute (NCI), National Center for Biotechnology Information (NCBI), Centers for Disease Control and Prevention (CDC), World Health Organization (WHO), International Agency for Research on Cancer (IARC), Global Cancer Observatory (GLOBOCAN), European Medicines Agency (EMA), European Commission, and relevant national health ministries and cancer registries.
Company and industry sources included annual reports, SEC and other regulatory filings, investor presentations, earnings releases, product catalogs, regulatory databases, company websites, scientific publications, clinical trial registries, peer-reviewed journals, and publications from pathology, genomics, oncology, and laboratory medicine associations. These sources were used to identify major participants, product and service portfolios, regulatory approvals, installed sequencing and pathology capabilities, test volumes, oncology revenue exposure, partnerships, clinical-trial activity, regional presence, technology adoption, and market developments.
Secondary data were analyzed to estimate the overall cancer tumor profiling market and to construct preliminary splits by product and service, technology, sample type, application, cancer type, end user, and region. The resulting estimates were subsequently validated and refined through primary research.
Primary Research
In-depth interviews were conducted with primary respondents, including executives of diagnostics and life-science companies, laboratory directors, molecular pathologists, oncologists, sequencing specialists, product managers, business-development leaders, clinical-trial professionals, and subject-matter experts. Interviews were conducted across both the supply and demand sides to validate market definitions, adoption levels, average selling prices, test volumes, technology mix, regional variation, end-user behavior, growth assumptions, and competitive positioning:
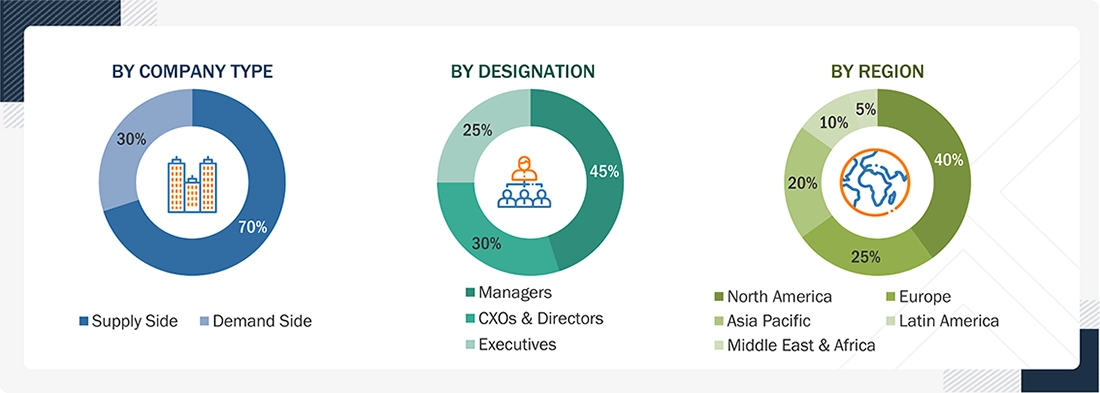
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The global cancer tumor profiling market was estimated through multiple complementary approaches. A detailed market-engineering model was used to estimate and validate the overall market and each segment. The process combined company-level revenue analysis, product and service mapping, test-volume assessment, installed-base evaluation, average selling price analysis, end-user demand estimation, and regional adoption patterns. The research methodology used to estimate the market size includes the following:
Cancer Tumor Profiling Market : Top-Down and Bottom-Up Approach
Data Triangulation
After estimating the overall market through the market-size estimation process, the total market was split into the defined segments and subsegments. To complete the market-engineering process and arrive at the final statistics, data triangulation was employed. The process examined factors and trends from both the demand and supply sides and reconciled company revenues, test volumes, installed systems, consumable pull-through, service revenue, technology adoption, cancer incidence, biomarker-testing patterns, and regional market conditions.
The final estimates were checked for consistency across all dimensions. For example, the product and service totals were reconciled with technology, sample type, application, cancer type, end user, and regional totals. Company-share estimates were also compared with the independently derived global market size to ensure that no major revenue pools were omitted or double-counted.
Market Definition
Cancer tumor profiling refers to the analysis of molecular, genomic, proteomic, and histopathologic characteristics of tumor material to support cancer diagnosis and molecular characterization, prognostic or risk assessment, treatment selection, companion diagnostic use, treatment-response and resistance monitoring, residual disease assessment, post-treatment surveillance, recurrence detection, biomarker discovery, and oncology drug development.
The market includes instruments and systems; assays, kits, reagents, and consumables; clinical tumor profiling testing services; and biopharmaceutical, clinical-trial, and companion diagnostic services. It covers next-generation sequencing, PCR-based technologies, immunohistochemistry, in situ hybridization, and other tumor profiling technologies applied to tissue, whole blood and plasma, bone marrow, and other relevant samples across solid tumors and hematologic malignancies.
The market excludes unrelated general laboratory testing, non-oncology molecular diagnostics, routine pathology procedures that do not contribute to tumor characterization, and hereditary or germline testing performed outside a cancer tumor profiling workflow.
Key Stakeholders
- Manufacturers and distributors of cancer tumor profiling instruments and systems
- Assay, kit, reagent, antibody, probe, and consumable suppliers
- Next-generation sequencing, PCR, IHC, and ISH technology providers
- Clinical tumor profiling and liquid-biopsy testing laboratories
- Hospitals, dedicated cancer centers, and oncology clinics
- Independent and specialty reference laboratories
- Pharmaceutical and biotechnology companies
- Contract research organizations and central laboratories
- Companion diagnostic developers and service providers
- Research institutes and academic medical center laboratories
- Regulatory agencies, reimbursement bodies, and cancer registries
- Market research and consulting firms
- Private equity firms, venture capitalists, and other investors.
Report Objectives
- To define, describe, segment, and forecast the global cancer tumor profiling market by offering, technology, sample type, application, cancer type, end user, and region
- To provide detailed information regarding the major factors influencing market growth, including drivers, restraints, opportunities, and challenges
- To analyze micromarkets with respect to individual growth trends, prospects, and contributions to the overall cancer tumor profiling market
- To analyze market opportunities for stakeholders and provide details of the competitive landscape for key players
- To forecast the size of the market segments with respect to six regions: North America(US and Canada), Europe (Germany, France, the UK, Italy, Spain, and the Rest of Europe), Asia Pacific (China, Japan, India, South Korea, Australia, and the Rest of Asia Pacific), Latin America (Brazil, Mexico, Argentina, and the Rest of Latin America), the Middle East [GCC and the Rest of Middle East], and Africa
- To profile the key players and comprehensively analyze their product portfolios, market positions, and core competencies
- To track and analyze company developments such as product launches & approvals, partnerships, acquisitions, agreements, collaborations, expansions, and other developments
- To benchmark players within the market using the proprietary “Company Evaluation Matrix” framework, which analyzes market players on various parameters within the broad categories of business and product excellence strategy
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per the company’s specific needs. The following customization options are available for the report:
Geographic Analysis
-
Further breakdown of the Rest of Europe cancer/tumor profiling market, by country
-
Further breakdown of the Rest of Asia Pacific cancer/tumor profiling market, by country
Company Information
-
Detailed analysis and profiling of additional market players (up to five)
-
Further breakup of additional Asia Pacific countries by offering, deployment mode, enterprise size, application, and vertical
-
Further breakup of additional Middle Eastern & African countries by offering, deployment mode, enterprise size, application, and vertical
Segment Analysis
- Cross-segment analysis
Get the Full Cancer/Tumor Profiling Market Report
Full forecast, segment splits, and company analysis for all Cancer/Tumor Profiling Market.
- Canada Cancer/Tumor Profiling Market
- US Cancer/Tumor Profiling Market
- France Cancer/Tumor Profiling Market
- Germany Cancer/Tumor Profiling Market
- Italy Cancer/Tumor Profiling Market
- UK Cancer/Tumor Profiling Market
- China Cancer/Tumor Profiling Market
- India Cancer/Tumor Profiling Market
- Japan Cancer/Tumor Profiling Market
- Rest Of Europe Cancer/Tumor Profiling Market
- Roapac Cancer/Tumor Profiling Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report