Europe Cold Chain Monitoring Market (2025-2030)
The Europe Cold Chain Monitoring Market was valued at $2276.7 Million in 2025 and projected to reach to $3839.1 Million by 2030, representing a compound annual growth rate of 11.0%. Europe's cold chain monitoring market is poised for sustained expansion through 2030, driven by increasingly stringent regulatory frameworks and the region's commitment to pharmaceutical safety standards.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Europe Cold Chain Monitoring Market Trends and Insights
- This 11.0% compound annual growth rate reflects Europe's stringent pharmaceutical and food safety regulations, which drive demand for advanced temperature and humidity tracking solutions across the region.
- Europe's mature healthcare infrastructure and high adoption of IoT-enabled monitoring systems position the continent as a critical hub for cold chain innovation. The European market benefits from strong regulatory frameworks including GDP (Good Distribution Practice) guidelines and GDPR compliance requirements, compelling pharmaceutical manufacturers, logistics providers, and food distributors to invest in sophisticated monitoring technologies.
- Europe's emphasis on supply chain transparency and product integrity has accelerated the deployment of real-time monitoring systems throughout the region.
- By 2030, Europe is expected to maintain its leadership position in cold chain monitoring adoption, driven by continued investments in healthcare logistics and food safety infrastructure..
Key Market Statistics
- CAGR (2025-2030) 11.0% CAGR
- Market Size, 2025 ~USD 2276.7 Million
- Forecast, 2030 ~USD 3839.1 Million
- Geography Europe
Europe Cold Chain Monitoring Market Overview
Regulatory Compliance Driving Growth :
Europe's stringent pharmaceutical and food safety regulations, including GDP and HACCP standards, mandate advanced temperature and humidity monitoring solutions, creating sustained demand across the region's cold chain infrastructure.
Germany Leads European Market :
Germany dominates Europe's cold chain monitoring market with $760.8 million in market size, driven by its robust pharmaceutical manufacturing sector and strict regulatory requirements for temperature-controlled logistics.
11% CAGR Through 2030 :
Europe's cold chain monitoring market is projected to grow from $2,276.7 million in 2025 to $3,839.1 million by 2030, reflecting strong adoption of IoT-enabled monitoring solutions across healthcare and food distribution networks.
Mature Healthcare Infrastructure :
Europe's established healthcare systems and advanced logistics networks accelerate the adoption of real-time monitoring technologies, ensuring product integrity and regulatory compliance across pharmaceutical supply chains.
Europe Cold Chain Monitoring Market Dynamics
- The market's 11% CAGR reflects growing investments in IoT and cloud-based monitoring solutions that enable real-time visibility across temperature-sensitive supply chains.
- Germany's leadership, combined with strong demand from the UK, France, and Spain, underscores the region's focus on advanced cold chain infrastructure. The outlook is further strengthened by Europe's mature healthcare ecosystem and the rising prevalence of biologics requiring precise temperature control.
- Digital transformation initiatives and sustainability concerns are pushing organizations to adopt intelligent monitoring systems that reduce product waste and ensure compliance.
- As regulatory pressures intensify and supply chain complexity increases, European enterprises will continue prioritizing advanced cold chain monitoring technologies to maintain competitive advantage and operational excellence..
Market Ecosystem
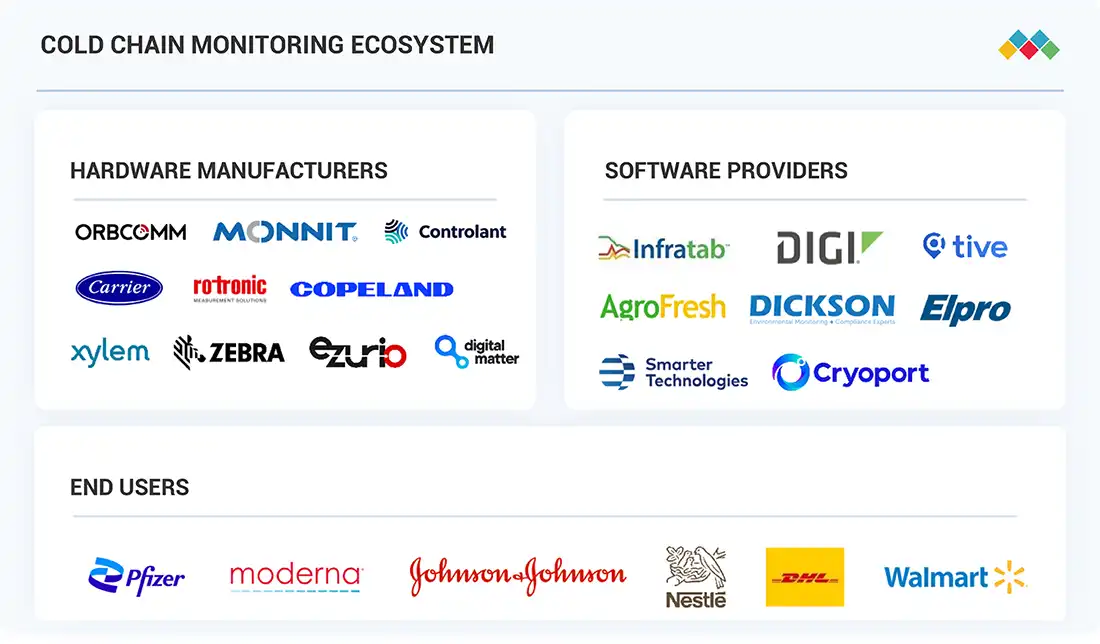
Cold Chain Monitoring Market Growth: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Offers comprehensive supply chain visibility solutions for temperature-sensitive cargo, including IoT-enabled data loggers, real-time telematics, and cloud-based platforms for monitoring pharmaceuticals, biologics, and perishable goods from origin to destination | Enhances cargo transparency, enables proactive issue resolution, ensures regulatory compliance, reduces spoilage risks, and supports sustainability by minimizing waste in the cold chain |
 |
Provides wireless data loggers and monitoring systems for temperature and humidity in storage, transport, and facilities, with cloud-based Saveris platform for food retail, pharma, and logistics applications | Optimizes compliance with HACCP and GxP standards, enables real-time alerts for deviations, reduces manual logging, improves food safety, and cuts operational costs through automated reporting |
 |
Delivers cryogenic and ultra-cold shipping systems with integrated Smartpak monitoring, including LN2 dry-vapor shippers and cloud platforms for biologics, vaccines, and cell therapies across the life sciences supply chain | Ensures chain-of-condition and custody for high-value materials, mitigates risks in multi-modal transport, supports ISO compliance, and provides 24/7 visibility to prevent product degradation and enable faster commercialization |
 |
Supplies reefer telematics solutions with sensors, satellite/cellular connectivity, and CargoWatch software for remote monitoring and control of refrigerated trailers, containers, and assets in food and pharma logistics | Prevents spoilage and lost revenue through automated alarms and two-way control, simplifies FSMA compliance with data retention, optimizes fuel and maintenance, and boosts fleet efficiency across road, rail, and sea |
 |
Offers IoT-based real-time visibility platforms with sensors, analytics, and 24/7 monitoring services for end-to-end cold chain management in pharma, biotech, and food sectors | Drives zero-waste supply chains via predictive insights and automated workflows, enhances patient safety and product integrity, reduces environmental impact, and ensures GxP compliance with audit-ready reporting |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Industrial Automation
- Sensors
- Image Sensors
- Manufacturing Execution System (MES)
- Actuators
- Flow Sensors
- ABB India Limited
- Siemens ag
- Emerson Electric Co.
- HONEYWELL INTERNATIONAL INC.
- SCHNEIDER ELECTRIC SE
Key Takeaways
- Europe's cold chain monitoring market will grow from $2,276.7M (2025) to $3,839.1M (2030) at an 11.0% CAGR, reflecting strong regulatory compliance demand.
- Stringent GDP and GDPR regulations across Europe mandate advanced monitoring solutions for pharmaceutical and food supply chains.
- Europe's mature healthcare infrastructure and IoT adoption rates position the region as a leader in cold chain technology implementation.
- Continued investment in supply chain transparency and product integrity will sustain Europe's market growth through 2030.
Cold Chain Monitoring Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | SOFTWARE (Offering) |
| Forecast Period | 2025-2030 |
| Growth Rate | CAGR of 12.6% from 2025 to 2030 |
| Largest Segment | HARDWARE (Offering) |
| Market Size Base Year (Billions) | ~USD 8.31 (2025) |
| Revenue Forecast (Billions) | ~USD 15.04 (2030) |
| Segments Covered | Temperature Type, Offering, Type, Application, Logistics |
Europe Cold Chain Monitoring Market Report Segmentation
5 segment dimensions are covered across the global market.
By Temperature Type
- Chilled
- Frozen
By Offering
- Hardware
- Software
By Type
- Airways
- Biobanks
- Blast Freezers
- Cloud-Based
- Cold Containers
- Fruits & Vegetables
- Meat & Seafood
- Medicines & Drugs
- Networking Devices
- On-Premises
- Poultry & Dairy Products
- Processed Foods
- Railways
- Rfid Devices
- Roadways
- Sensors & Data Loggers
- Sensors And Data Loggers
- Telematics & Telemetry Devices
- Vaccines
- Warehouses
- Waterways
By Application
- Chemicals
- Food & Beverages
- Other Applications
- Pharmaceuticals & Healthcare
By Logistics
- Storage
- Transportation
REST OF EUROPE: COLD CHAIN MONITORING MARKET, BY APPLICATION, 2025–2030
| Segment | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | CAGR (%) |
|---|---|---|---|---|---|---|---|
| CHEMICALS | 11.4 | 12.4 | 13.5 | 14.7 | 15.8 | 16.8 | 8.1 |
| FOOD & BEVERAGES | 216.6 | 239 | 265 | 293.5 | 322.7 | 351.9 | 10.2 |
| OTHER APPLICATIONS | 12 | 13.1 | 14.6 | 15.3 | 16.4 | 16.6 | 6.8 |
| PHARMACEUTICALS & HEALTHCARE | 70.6 | 81.4 | 94.1 | 108.7 | 124.4 | 141.3 | 14.9 |
| TOTAL | 310.6 | 345.8 | 387.1 | 432.2 | 479.3 | 526.6 | 11.1 |
Target Audience
- Pharmaceutical Manufacturers : European pharma companies require detailed market intelligence on cold chain monitoring solutions to ensure regulatory compliance, protect product integrity, and optimize supply chain efficiency across the region.
- Cold Chain Solution Providers : Technology vendors and logistics service providers need country-specific market data to develop targeted go-to-market strategies, identify partnership opportunities, and expand their European footprint.
- Food & Beverage Distributors : European food logistics companies need insights into temperature monitoring adoption trends and regulatory requirements to enhance supply chain visibility and reduce product spoilage.
- Healthcare & Hospital Networks : Hospital systems and healthcare providers require market analysis to evaluate cold chain monitoring investments for vaccine storage, blood products, and biologics management across European facilities.
- Investment & Strategy Consultants : Management consultants and private equity firms need comprehensive European market data to assess investment opportunities, identify acquisition targets, and develop growth strategies in the cold chain sector.
Countries within Europe - compare and drill down
| Country | 2025 size (native) |
|---|---|
| Germany | USD 760.8 Million |
| UK | USD 136 Million |
| France | USD 112.6 Million |
| Spain | USD 124.1 Million |
| Italy | USD 93.5 Million |
| Poland | USD 89.7 Million |
| Nordic Countries | USD 78.3 Million |
| Rest Of Europe | USD 141.3 Million |
Country market size visualization
Reasons to Buy this Report
- Country-Level Market Insights : Access detailed market sizing and growth projections for Germany, UK, France, Spain, Italy, Poland, and Nordic countries to identify high-opportunity markets within Europe.
- Regulatory Landscape Analysis : Understand how EU GDP, HACCP, and national regulations shape cold chain monitoring adoption across pharmaceutical, food, and healthcare sectors in each European market.
- Competitive Positioning Strategy : Benchmark your solutions against regional competitors and identify market gaps in Germany's $760.8M market and emerging opportunities in Central and Eastern European countries.
- Investment & Expansion Planning : Make data-driven decisions on market entry, partnership development, and resource allocation across Europe's fastest-growing cold chain monitoring segments through 2030.
- Technology Adoption Trends : Gain insights into IoT, cloud-based monitoring, and real-time tracking adoption rates across European pharmaceutical, food distribution, and healthcare logistics networks.
Frequently asked questions
What is the current size of Europe's cold chain monitoring market?
Europe's cold chain monitoring market is valued at $2,276.7 million in 2025, with expectations to reach $3,839.1 million by 2030.
What is the projected growth rate for Europe's cold chain monitoring market?
Europe's cold chain monitoring market is projected to grow at an 11.0% CAGR from 2025 to 2030.
Which regulations drive cold chain monitoring adoption in Europe?
Europe's GDP (Good Distribution Practice) guidelines, GDPR compliance requirements, and food safety regulations are primary drivers of cold chain monitoring adoption across the region.
What industries are the primary adopters of cold chain monitoring in Europe?
Pharmaceutical manufacturers, healthcare logistics providers, food distributors, and vaccine storage facilities are the primary adopters of cold chain monitoring solutions in Europe.
How does Europe's market compare to global cold chain monitoring trends?
Europe's 11.0% CAGR is slightly below the global 12.6% CAGR, but Europe maintains higher market maturity and stricter regulatory compliance standards that drive premium solution adoption.
RESEARCH METHODOLOGY
The study involved major activities in estimating the current market size for the cold chain monitoring market. Exhaustive secondary research was done to collect information on the cold chain monitoring industry. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain using primary research. Different approaches, such as top-down and bottom-up, were employed to estimate the total market size. After that, the market breakup and data triangulation procedures were used to estimate the market size of the segments and subsegments of the cold chain monitoring market.
Secondary Research
Secondary research for this study involved gathering information from various credible sources such as company reports, white papers, journals, and industry publications. This process helped in understanding the supply and value chains, identifying key players, analyzing market segmentation and regional trends, and tracking major market and technology developments. The data collected was used to estimate the overall market size, which was later validated through primary research.
Primary Research
Extensive primary research was conducted after gaining knowledge about the current scenario of the cold chain monitoring market through secondary research. Several primary interviews were conducted with experts from the demand and supply sides across four major regions—North America, Europe, Asia Pacific, and RoW. This primary data was collected through questionnaires, emails, and telephonic interviews.
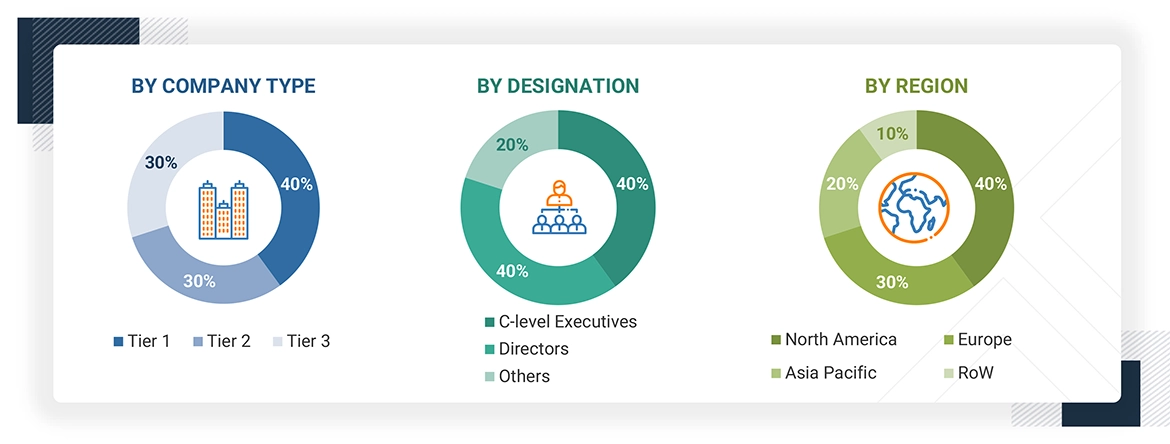
Notes: RoW mainly comprises the Middle East, Africa, and South America.
Other designations include product managers, sales managers, and marketing managers.
Tier 1 companies include market players with revenues above USD 500 million; tier 2 companies earn revenues between USD 100 million and USD 500 million; and tier 3 companies earn revenues of up to USD 100 million.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
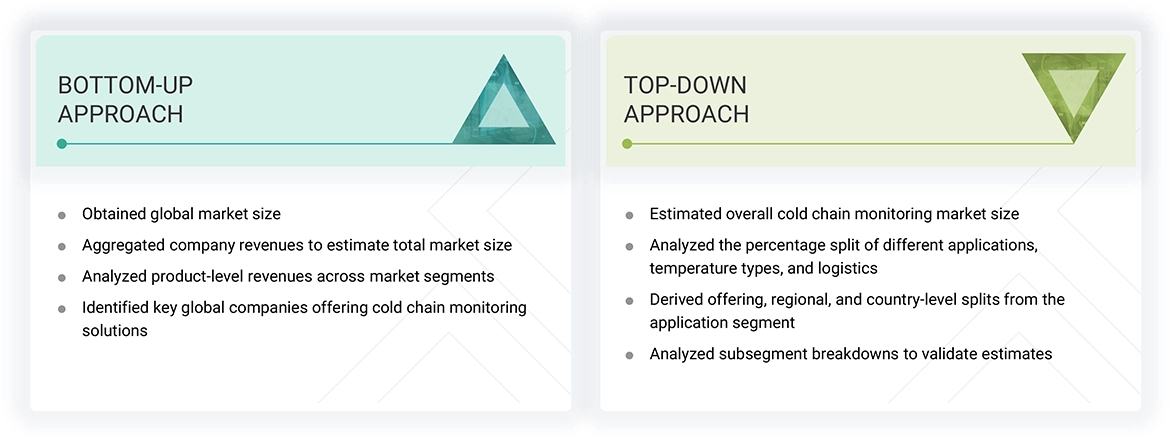
The bottom-up procedure has been employed to arrive at the overall size of the cold chain monitoring market.
- Collected company-level revenues from annual reports and financial disclosures
- Aggregated product-level revenues across hardware and software to estimate market segments
- Identified key players’ contributions to cold chain monitoring solutions
- Summed up the company revenues to obtain the global market size
The top-down approach has been used to estimate and validate the total size of the cold-chain monitoring market.
- Estimated overall cold chain monitoring market size using industry-level data (cold chain logistics spend, cold storage capacity, pharma & F&B trade volumes)
- Applied adoption/penetration rates of monitoring solutions across applications, temperature ranges, and logistics
- Derived regional and country-level splits based on infrastructure readiness, regulatory compliance, and trade data
- Validated subsegment distribution through primary research and expert insights
Cold Chain Monitoring Market : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size using the market size estimation processes as explained above, the market has been split into several segments and subsegments. To complete the entire market engineering process and arrive at the exact statistics of each market segment and subsegment, data triangulation and market breakdown procedures have been employed, wherever applicable. The data has been triangulated by studying various factors and trends from the demand and supply sides in the cold chain monitoring market.
Market Definition
The cold chain monitoring refers to the ecosystem of technologies, solutions, and services designed to track, control, and optimize temperature-sensitive supply chains, ensuring product safety, regulatory compliance, and operational efficiency across industries such as food & beverages, pharmaceuticals & healthcare, chemicals, agriculture, and manufacturing. It encompasses hardware devices like sensors & data loggers, RFID devices, telematics & telemetry devices, and networking devices, as well as advanced software platforms that leverage IoT, cloud computing, and AI for real-time visibility and predictive analytics. Unlike traditional logistics systems, cold chain monitoring focuses on maintaining product integrity during storage, transportation, and distribution by reducing temperature excursions and minimizing spoilage.
Key Stakeholders
- Cold chain warehouses
- Sensors manufactures
- Logistics companies
- Manufacturers of pharmaceuticals
- Large-scale farmers
- Fisheries
- Manufacturers of dairy products
- Pharmacies
- Large food retailers
- Food processing companies
- Distributors
- Investors
- Government organizations
- Research organizations
- Organizations related to cold chains
Report Objectives
- To define, describe, and forecast the size of the cold chain monitoring market, by temperature type, logistics, offering, application, and region, in terms of value
- To describe and forecast the size of the cold chain monitoring market, by offering, in terms of volume
-
To forecast the market for various segments concerning the main regions, namely,
North America, Europe, Asia Pacific, and the Rest of the World (RoW), in terms of value - To provide macroeconomic outlooks concerning the main regions, namely, North America, Europe, Asia Pacific, and the Rest of the World (RoW)
- To provide detailed information regarding the drivers, restraints, opportunities, and challenges influencing the market’s growth
- To strategically analyze micromarkets1 concerning individual growth trends, prospects, and contributions to the total market
- To provide ecosystem analysis, value chain, trends/disruptions impacting customer business, technology analysis, pricing analysis, case study analysis, trade analysis, patent analysis, Porter’s five forces, key conferences & events, AI impact, impact of 2025 US tariff, and regulations related to the cold chain monitoring market
- To analyze the opportunities in the market for stakeholders by identifying high-growth segments and detailing the competitive landscape for market players
- To strategically profile key players and comprehensively analyze their market rankings, core competencies, company evaluation matrix, and competitive scenario, along with detailing the competitive landscape for the market leaders
- To analyze competitive developments, such as product launches, collaborations, and acquisitions, carried out by market players
- To benchmark players within the market using the competitive leadership mapping framework, which analyzes market players on various parameters within the broad categories of business strategy excellence and strength of product portfolio.
Available Customizations
With the given market data, MarketsandMarkets offers customizations according to the company‘s specific needs. The following customization options are available for the report.
Company Information:
- Detailed analysis and profiling of additional market players (up to five)
Get the Full Cold Chain Monitoring Market Report
Full forecast, segment splits, and company analysis for all Cold Chain Monitoring Market.
- US Cold Chain Monitoring Market
- Canada Cold Chain Monitoring Market
- Mexico Cold Chain Monitoring Market
- Germany Cold Chain Monitoring Market
- UK Cold Chain Monitoring Market
- France Cold Chain Monitoring Market
- Spain Cold Chain Monitoring Market
- Italy Cold Chain Monitoring Market
- Poland Cold Chain Monitoring Market
- China Cold Chain Monitoring Market
- Japan Cold Chain Monitoring Market
- South Korea Cold Chain Monitoring Market
- India Cold Chain Monitoring Market
- Australia Cold Chain Monitoring Market
- Indonesia Cold Chain Monitoring Market
- Malaysia Cold Chain Monitoring Market
- Thailand Cold Chain Monitoring Market
- Vietnam Cold Chain Monitoring Market
- Nordic Countries Cold Chain Monitoring Market
- Rest Of Europe Cold Chain Monitoring Market
- Rest Of Asia Pacific Cold Chain Monitoring Market
- Bahrain Cold Chain Monitoring Market
- Kuwait Cold Chain Monitoring Market
- Oman Cold Chain Monitoring Market
- Qatar Cold Chain Monitoring Market
- Rest Of The Middle East Cold Chain Monitoring Market
- Saudi Arabia Cold Chain Monitoring Market
- United Arab Emirates (UAE) Cold Chain Monitoring Market
- Rest Of Africa Cold Chain Monitoring Market
- South Africa Cold Chain Monitoring Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report