China eGRC Market (2024-2029)
The China eGRC Market was valued at $1342.2 Million in 2024 and projected to reach to $2564.2 Million by 2029, representing a compound annual growth rate of 13.8%. China's eGRC market is positioned for sustained growth driven by escalating regulatory requirements and enterprise digital modernization efforts.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
China eGRC Market Trends and Insights
- This growth trajectory reflects China's increasing regulatory complexity and heightened focus on governance, risk, and compliance frameworks across enterprises.
- China's digital transformation initiatives and stricter data protection regulations are driving widespread adoption of eGRC solutions among financial institutions, technology companies, and multinational corporations operating within the region. The 13.8% compound annual growth rate underscores China's commitment to strengthening internal controls and regulatory adherence.
- China's market is characterized by rapid digitalization, evolving compliance requirements, and growing cybersecurity concerns that necessitate comprehensive eGRC platforms.
- By 2029, China is expected to consolidate its position as a critical eGRC hub, with enterprises increasingly investing in integrated governance solutions to navigate complex regulatory landscapes and mitigate operational risks..
Key Market Statistics
- CAGR (2024-2029) 13.8% CAGR
- Market Size, 2024 ~USD 1342.2 Million
- Forecast, 2029 ~USD 2564.2 Million
- Country China
China eGRC Market Overview
Rapid Market Expansion :
China's eGRC market is growing at 13.8% CAGR, expanding from $1,342.2 million in 2024 to $2,564.2 million by 2029, outpacing the global growth rate of 13.4%.
Regulatory Complexity Driving Adoption :
Increasingly stringent Chinese regulations, including data protection laws and compliance mandates, are compelling enterprises to invest in comprehensive governance, risk, and compliance solutions.
Digital Transformation Catalyst :
China's aggressive digital transformation initiatives across industries are accelerating eGRC platform adoption as organizations modernize their compliance and risk management infrastructure.
Data Protection Focus :
Enhanced data protection regulations and cybersecurity requirements are pushing Chinese enterprises to implement robust eGRC frameworks to ensure regulatory adherence and operational resilience.
China eGRC Market Dynamics
- The market's expansion reflects heightened awareness among Chinese organizations regarding the critical importance of integrated governance, risk, and compliance frameworks in managing operational complexity and regulatory exposure.
- Government initiatives promoting digital transformation across sectors are creating substantial demand for advanced eGRC solutions. Looking ahead, China's eGRC market will be shaped by evolving data protection standards, increased cybersecurity mandates, and the need for enterprises to maintain compliance across multiple jurisdictions.
- As organizations expand internationally and face more complex regulatory landscapes, investment in sophisticated eGRC platforms will become essential for competitive advantage and risk mitigation..
Market Ecosystem


OVERVIEW
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
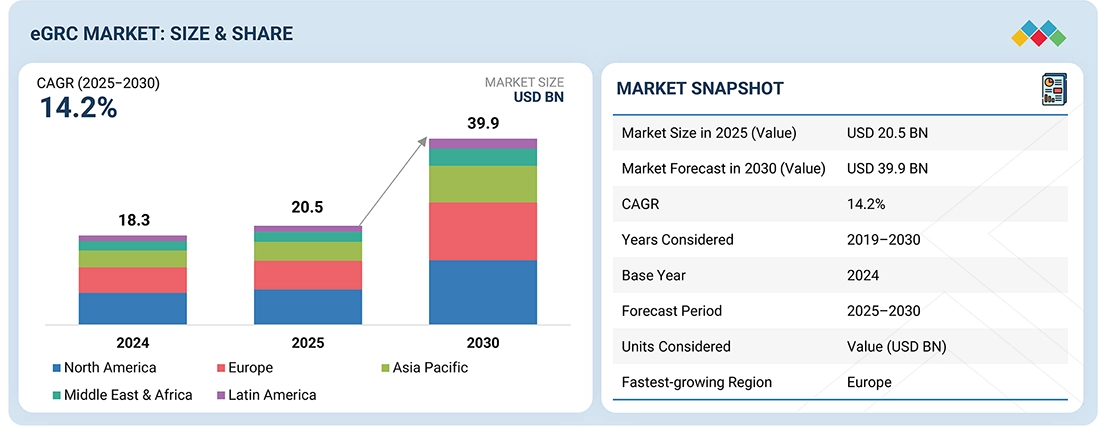
The eGRC market is projected to reach USD 39.99 billion by 2030 from USD 20.56 billion in 2025, at a CAGR of 14.2%. Growth in the eGRC market is fueled by multiple factors, including increased global regulations, rapidly evolving third-party ecosystems, and a heightened focus on cyber and data privacy risks. Expectations are increasing from investors, customers, and regulators for transparency and accountability in governance and compliance. Increasingly, organizations are moving from fragmented manual compliance processes to Integrated eGRC platforms that provide centralized risk visibility, continuous compliance monitoring, and audit-ready reporting across all business functions.
Market Size and Forecast:
- Market Size Value in 2024: USD 18.3 Billion
- Market Size Value in 2025: USD 20.5 Billion
- Revenue Forecast in 2030: USD 39.9 Billion
- Growth Rate: CAGR of 14.2 % from 2025 to 2030
- Data available from 2019 to 2030
- Base year: 2024
- Forecast period: 2025-2030
- Largest Growing Region: Europe
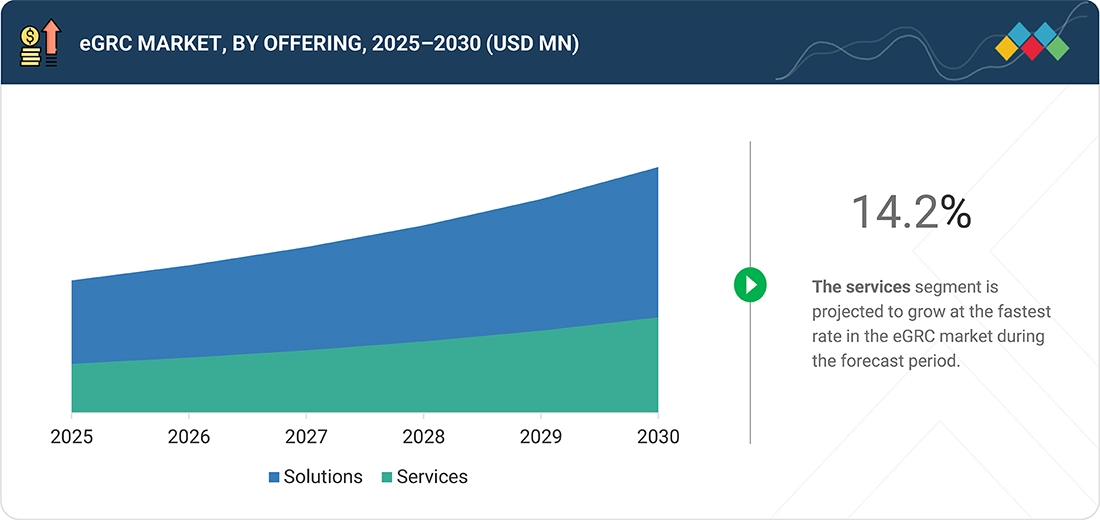
- The eGRC services growing at a CAGR of 14.2 %
-
US eGRC Market
- Market size USD 5.45 billion in 2025
- Market forecast USD 10.17 billion in 2030
- Market Growing at a CAGR of 13.3 %
-
Europe eGRC Market
- Market size USD 6.03 billion in 2025
- Market forecast USD 12.60 billion in 2030
- Market Growing at a CAGR of 15.9 %
-
Asia Pacific eGRC Market
- Market size USD 3.94 billion in 2025
- Market forecast USD 7.87 billion in 2030
- Market Growing at a CAGR of 14.9 %
KEY TAKEAWAYS
-
BY REGIONNorth America is estimated to account for the largest share of the global eGRC market in 2025.
-
BY OFFERINGBy offering, the solutions segment is expected to dominate the market during the forecast period.
-
BY SOLUTION USAGEBy solution usage, the internal segment is expected to dominate the market during the forecast period.
-
BY DEPLOYMENT MODEBy deployment mode, the on-premise segment is expected to dominate the market during the forecast period.
-
BY ORGANIZATION SIZEBy organization size, the SMEs segment is projected to grow at a higher CAGR of 15.1% during the forecast period.
-
BY BUSINESS FUNCTIONBy business function, the IT segment is projected to grow at the highest CAGR of about 14.6% from 2025 to 2030.
-
BY VERTICALBy vertical, the healthcare segment is projected to witness the highest CAGR of 13.3% during the forecast period.
-
COMPETITIVE LANDSCAPE - KEY PLAYERSWolters Kluwer, FIS, and Microsoft lead the eGRC market with broad, integrated platforms that unify risk, compliance, audit, policy, and privacy management across global enterprises.
-
COMPETITIVE LANDSCAPE - STARTUPSStandardFusion, Comensure, and DynamicGRC are emerging eGRC innovators delivering agile, cloud-native governance solutions tailored to mid-market and fast-growing organizations.
As enterprises scale across regions, business units, and supply chains, managing risk in fragmented ways creates blind spots. This makes a centralized, real-time view of risk essential, as it helps organizations identify emerging threats early and apply consistent controls. With better visibility, enterprises can make informed decisions and maintain compliance across global operations.
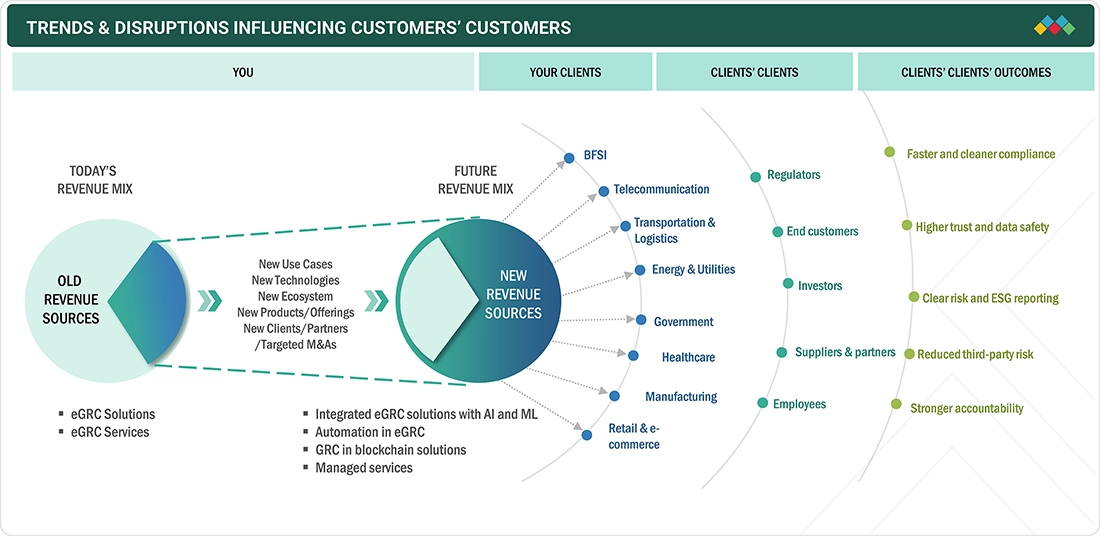
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
The growing demand for eGRC solutions and services that utilize advanced technologies is creating new revenue opportunities for vendors in the eGRC market. As organizations expand their digital operations, they face more complex governance requirements, higher cyber risks, and a wider range of compliance obligations. At the same time, regulators are tightening rules and imposing stricter penalties for non-compliance. As a result, businesses are seeking eGRC platforms that enable them to manage these challenges through enhanced visibility, streamlined compliance processes, and improved risk management.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Increasing regulatory compliance mandates

-
Rising cybersecurity threats


Level
-
Complexity in keeping pace with evolving laws and regulatory requirements

-
Inconsistent data quality limiting reliability of risk insights


Level
-
Integration of AI/ML and blockchain technologies in GRC solutions

-
Integration of eGRC with core business operations


Level
-
Gap between company’s culture and its eGRC framework

-
Provision of comprehensive eGRC solutions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Increasing regulatory compliance mandates
eGRC solutions are becoming an essential tool for many organizations as they seek to manage the growing regulatory landscape for data privacy, financial reporting, and sector-specific requirements. To provide an integrated approach to compliance management, companies are leveraging solutions like risk management, compliance management, and policy management across all industries.
Restraint: Complexity in keeping pace with evolving laws and regulatory requirements
Compliance management has become complex and resource-intensive due to frequent updates to global, federal, and industry-specific regulations. There are compliance delays, operational inefficiencies, and increased regulatory penalties, as organizations often struggle to interpret new requirements, update internal policies, retrain employees, and realign controls.
Opportunity: Integration of eGRC with core business operations
eGRC can provide organizations with "real-time" visibility into risks, support consistent business decisions, and, consequently, a unified focus on the organization's performance goals by integrating eGRC into all functions. Thus, the objectives of compliance management become part of an organization's everyday operations and resiliency planning, in addition to meeting regulatory obligations.
Challenge: Gap between company’s culture and its eGRC framework
There are two critical components for successful adoption of eGRC, People and Technology. People must be assigned to leadership roles in a manner that provides clear accountability and support from every level of the organization. Organizations must have clear definitions of the regulatory risks associated with their business and established performance goals for controlling those risks. The inability of individuals to understand regulatory risks and hold themselves accountable for mitigating the associated risks, as well as the speed of adoption and the subsequent positive impact of the adoption, will be significantly reduced, thereby limiting the success of the organization's governance and compliance programs.
only Driver, Opportunity and Challenge
EGRC MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
A North American bank uses Wolters Kluwer OneSumX to centralize regulatory reporting, policy management, and audit workflows across multiple subsidiaries, ensuring alignment with FFIEC and Basel guidelines. | Smoother compliance processes, minimum reporting errors, faster audits, and clear regulatory oversight |
 |
Mid-sized financial institutions leverage FIS enterprise risk and compliance solutions to automate KYC, vendor risk, and operational risk assessments, such as monitoring third-party fintech partners. | Lower compliance workload, real-time risk visibility, better vendor governance, fewer manual review bottlenecks |
 |
Global enterprises use Microsoft Purview and Azure-based eGRC tools to manage data governance, privacy risks, and regulatory compliance across cloud environments. | Unified risk oversight, enhanced data protection, scalable compliance management, reduced remediation time |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
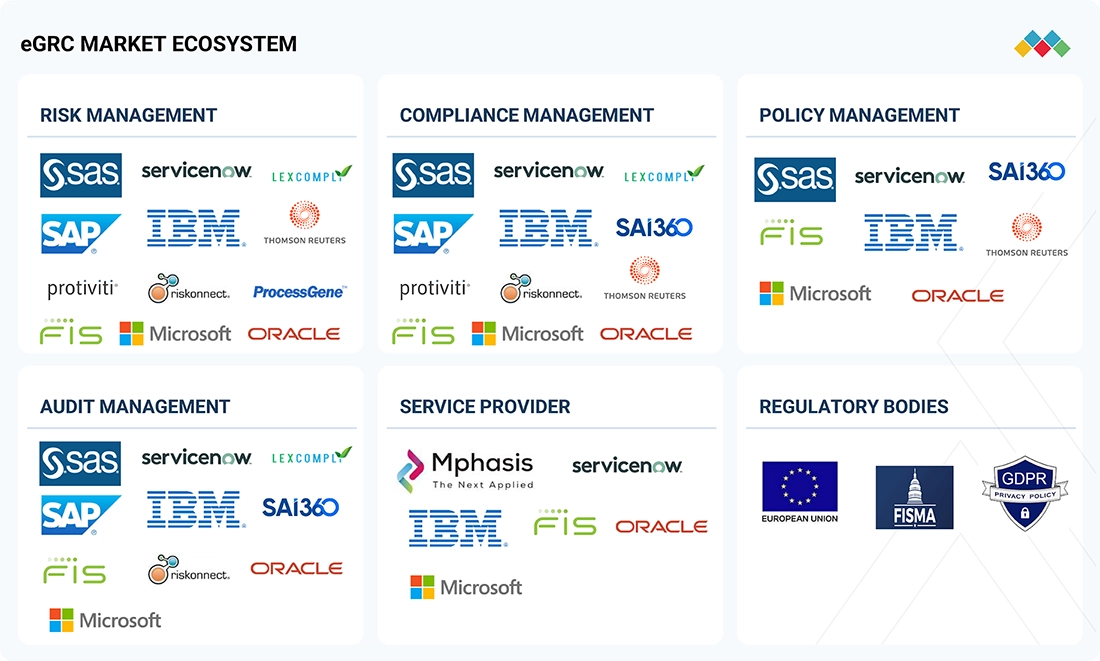
The eGRC ecosystem includes technology vendors that provide platforms for managing risk, compliance, policies, and audits, along with consulting and managed service providers that help organizations deploy and run these systems. Regulators play a key role by setting requirements that encourage adoption across industries as companies look for integrated ways to manage data privacy, financial controls, and cybersecurity obligations.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
eGRC, By Offering
The solutions segment holds the largest share as organizations rely on software platforms to manage governance, risk, and compliance activities in a more structured way. These tools help teams gain visibility, maintain consistency, and respond faster to regulatory requirements across daily operations.
eGRC, By Solution
The risk management segment is the fastest-growing, as organizations focus on identifying and addressing risks before they affect operations. Increasing reliance on third-party vendors, digital processes, and interconnected systems has expanded exposure. As a result, businesses are prioritizing risk visibility and continuous monitoring to support informed decision-making.
eGRC, By Deployment Mode
The on-premises segment accounts for the largest market share as many organizations operate under strict regulatory and data-residency requirements. Keeping systems in-house allows closer control over sensitive compliance and risk data.
eGRC, By Organization Size
The SMEs segment is the fastest-growing segment, as rising cyber risks and tighter regulations are pushing smaller organizations to formalize governance and compliance processes. At the same time, customer expectations, partner requirements, and contractual obligations are increasingly forcing SMEs to demonstrate stronger control and accountability.
eGRC, By Solution Usage
The internal segment accounts for the largest share as organizations depend on eGRC platforms for their day-to-day governance, risk, and compliance activities. These systems are used regularly by internal teams to track controls, manage audits, and monitor risks. Keeping these processes internal helps improve coordination, strengthen accountability, and maintain consistency across the organization.
eGRC Market, By Business Function
The finance segment holds the largest share in the overall market as audits, internal controls, and regulatory reporting are primarily managed by finance teams. eGRC platforms support accuracy, transparency, and accountability in financial oversight. This helps finance teams stay prepared for reviews and reduce last-minute compliance pressure.
eGRC Market, By Vertical
The retail and e-commerce segment is the fastest-growing segment as rapid digital expansion and complex supply chains increase compliance and data privacy exposure. Organizations in this vertical are adopting eGRC to maintain control while scaling operations. It enables operational expansion without compromising risk and compliance oversight.
REGION
Europe to be fastest-growing region in global eGRC market during forecast period
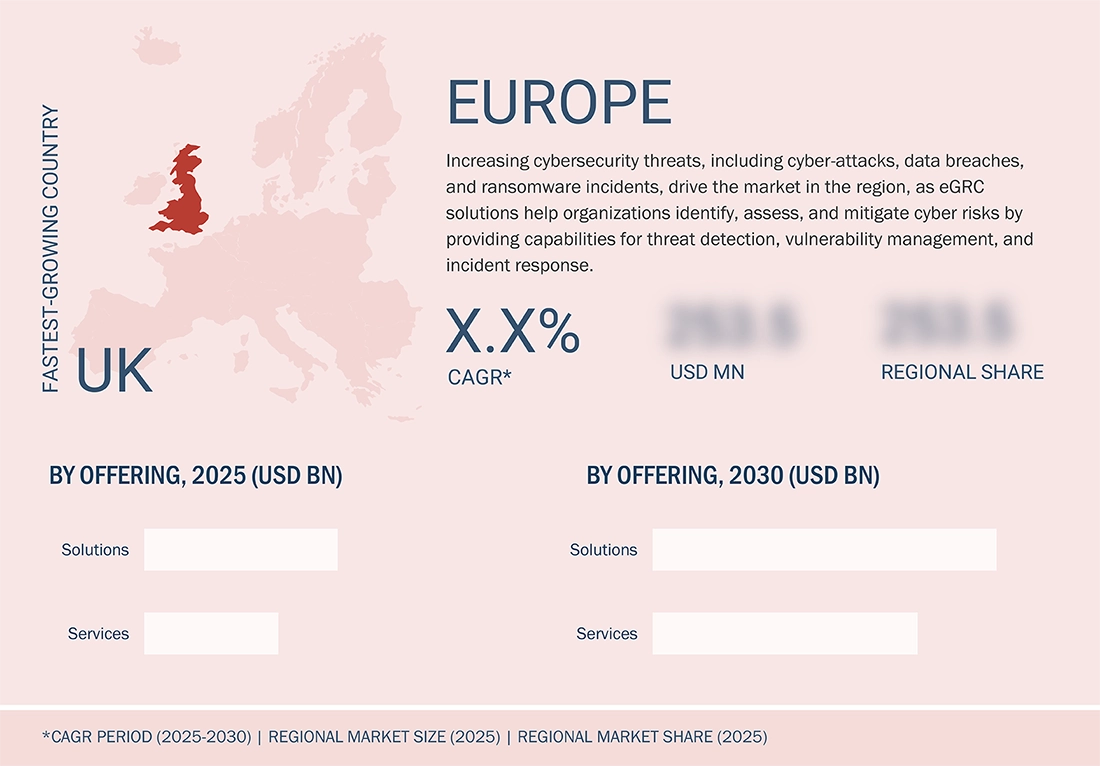
The eGRC market in Europe is experiencing rapid growth due to the increasing global eGRC regulations, such as the GDPR, and the expansion of ESG disclosures. In addition, European regulations are enforced with severe penalties. Countries such as Germany, the UK, France, and the Nordic nations are at the forefront of eGRC adoption. Organizations in these markets aim to maintain operations across multiple locations and manage complex supply chains. At the same time, they face increasing data and cyber-related risks, which is pushing them toward eGRC solutions. Cloud-based, integrated eGRC platforms, along with a stronger focus on ESG and third-party risks, are driving vendors in Europe to identify new areas for growth and expansion.
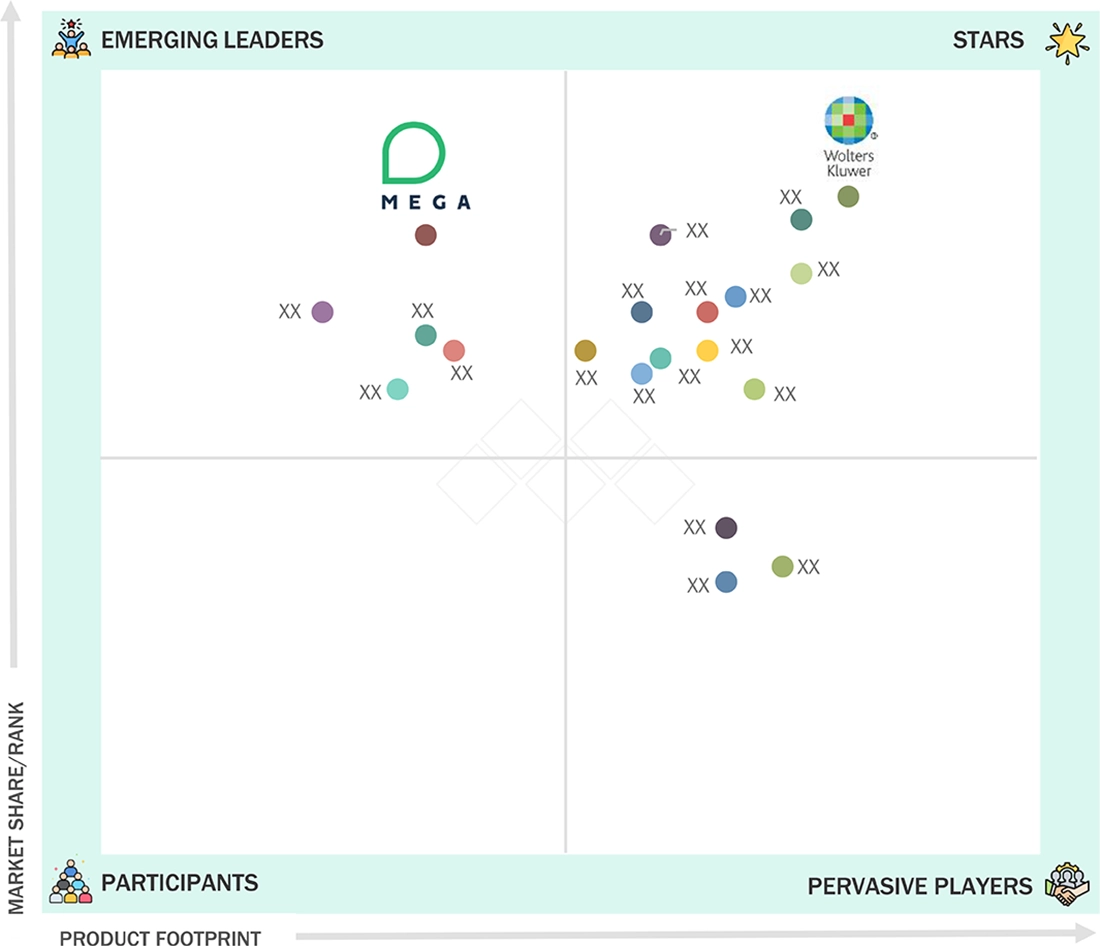
EGRC MARKET: COMPANY EVALUATION MATRIX
In the eGRC market matrix, Wolters Kluwer (Star) leads with its comprehensive OneSumX platform, deep regulatory intelligence, automated reporting, and strong integration of audit, risk, and compliance, enabling global enterprises to standardize controls and navigate multi-jurisdictional regulations with confidence. Mega International (Emerging Leader) is rapidly gaining momentum through its flexible HOPEX platform, scalable governance workflows, and expanding risk and process-management capabilities.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- ServiceNow (US)
- Wolters Kluwer (Netherlands)
- LexisNexis (US)
- MetricStream (US)
- Riskonnect (US)
- SAS Institute (US)
- Thomson Reuters (Canada)
- FIS (US)
- IBM (US)
- Microsoft (US)
- Mphasis (India)
- Oracle (US)
- SAP (Germany)
- Navex Global (US)
- OneTrust (US)
- Mega International (France)
- LogicManager (US)
- Acuity Risk Management (UK)
- C&F SA (Poland)
- Allgress (US)
- GlobalSuite Solutions (Spain)
- Onspring (US)
- Optimiso (US)
- ReadiNow (Australia)
- SureCloud (UK)
- StandardFusion (Canada)
- Comensure (US)
- Dynamic GRC (Singapore)
- LogicGate (US)
- VComply (US)
- SmartSuite (US)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2024 (Value) | USD 18.3 Billion |
| Market Forecast in 2030 (Value) | USD 39.9 Billion |
| Growth Rate | CAGR of 14.2% from 2025-2030 |
| Years Considered | 2019-2030 |
| Base Year | 2024 |
| Forecast Period | 2025-2030 |
| Units Considered | Value (USD Billion) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Regions Covered | North America, Europe, Asia Pacific, Middle East & Africa, Latin America |
WHAT IS IN IT FOR YOU: EGRC MARKET REPORT CONTENT GUIDE
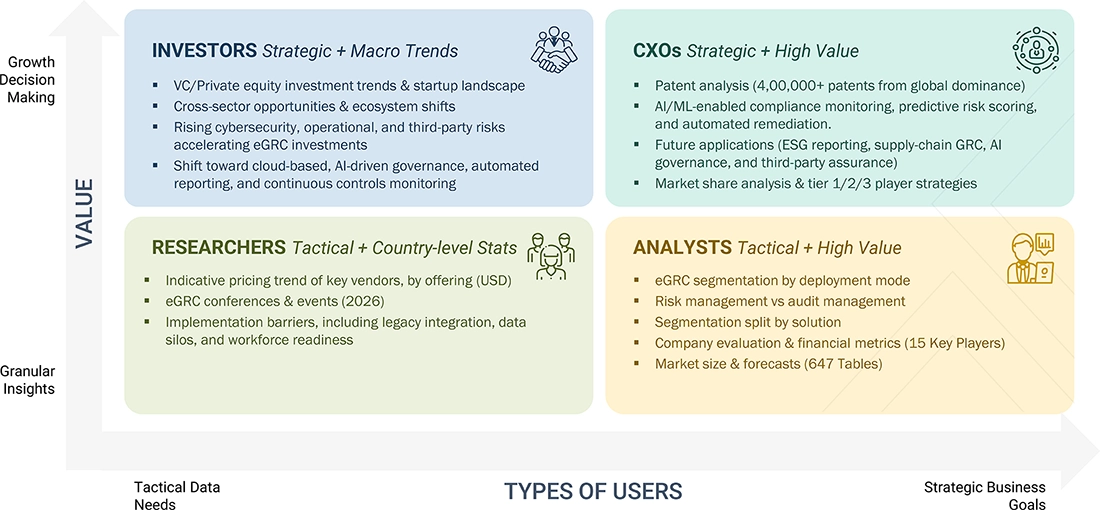
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Leading Solution Provider (US) | Product Analysis: eGRC Solution Matrix offering an in-depth comparison of each vendor’s capabilities, including enterprise risk management, compliance automation, audit workflows, policy lifecycle management, ESG reporting, third-party risk oversight, data privacy controls, workflow orchestration, analytics, and cloud/on-premises deployment flexibility | Stronger understanding of competitive eGRC positioning, product breadth, regulatory content depth, integration maturity, and automation capabilities to support strategic investment planning, platform enhancement, and multi-year governance, risk, and compliance transformation initiatives |
| Leading Service Provider (EU) | Company Information: Detailed profiling and evaluation of additional eGRC vendors (up to 5), covering solution modules, regulatory intelligence assets, implementation methodologies, managed compliance services, AI-enabled risk scoring, assurance frameworks, and strategic partnerships across diverse regulatory jurisdictions and IT environments | Comprehensive overview of the evolving eGRC landscape, highlighting managed service growth opportunities, rising compliance outsourcing demand, vendor collaboration potential, and expansion areas driven by ESG mandates, privacy regulations, operational risk modernization, and enterprise digital governance priorities |
RECENT DEVELOPMENTS
- April 2024 : To support more sustainable business practices worldwide, AdaptiveGRC partnered with Forward Earth. While staying aligned with regulatory requirements, this partnership helps organizations better track and manage their environmental impact. Together, they aim to make sustainability and compliance easier to manage as part of everyday business operations.
- February 2024 : SAS signed an agreement with Carahsoft to bring analytics, AI, and data management solutions to the public sector. Under the agreement, Carahsoft will serve as a SAS Public Sector Distributor, making the company's analytics, AI, and data management solutions available to US government agencies through Carahsoft's reseller partners and various contract vehicles and government schedules.
- February 2024 : To modernize its planning, operations, and resource management systems, Arab Developers Holding entered into a strategic partnership with SAP. By improving how teams work, manage data, and control processes, the collaboration supports the company’s broader digital transformation goals. It is designed to simplify day-to-day operations, improve visibility, and raise overall efficiency as customer expectations continue to evolve.
Related Ecosystem
Software And Services
- Natural Language Processing (NLP)
- Machine Learning
- Supply Chain Management
- Predictive Analytics
- Image Sensors
- International Business Machines Corporation
- MICROSOFT CORPORATION
- Oracle Corporation
- SAP SE
- Amazon.com, Inc.
Cyber Security
- Cloud Security
- Biometric Systems
- Multi-Factor Authentication
- Security Analytics
- Data Loss Prevention (DLP)
- International Business Machines Corporation
- Cisco Systems, Inc.
- MITSUI BUSSAN SECURE DIRECTIONS INC
- MICROSOFT CORPORATION
- Allot Ltd.
Key Takeaways
- China's eGRC market will nearly double from $1,342.2M (2024) to $2,564.2M (2029), driven by regulatory pressures and digital transformation.
- China's 13.8% CAGR outpaces global growth, reflecting accelerated compliance demands and cybersecurity investments across sectors.
- China's financial services, technology, and manufacturing sectors are primary adopters of eGRC solutions to manage governance complexity.
- China's market expansion is fueled by stricter data protection laws, SOX-equivalent regulations, and enterprise risk management mandates.
eGRC Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | HEALTHCARE (Vertical) |
| Forecast Period | 2024–2029 |
| Growth Rate | CAGR of 13.4% from 2024 to 2029 |
| Largest Segment | LARGE ENTERPRISES (Organization Size) |
| Market Size Base Year (Billions) | ~USD 18.4 (2024) |
| Revenue Forecast (Billions) | ~USD 34.5 (2029) |
| Segments Covered | Offering, Solution, Service, Solution Usage, Deployment Mode, Organization Size, Business Function, Vertical |
China eGRC Market Report Segmentation
8 segment dimensions are covered across the global market.
By Offering
- Services
- Solution
- Solutions
By Solution
- Audit Management
- Compliance Management
- Policy Management
- Privacy Management
- Risk Management
By Service
- Managed
- Professional
By Solution Usage
- External
- Internal
By Deployment Mode
- Cloud
- On-Premises
By Organization Size
- Large Enterprises
- Smes
By Business Function
- Finance
- It
- Legal
- Operations
By Vertical
- Bfsi
- Energy & Utilities
- Government
- Healthcare
- It & Ites
- Manufacturing
- Other Verticals
- Retail & Ecommerce
- Telecommunication
- Transportation & Logistics
CHINA: EGRC MARKET, BY VERTICAL, 2024–2029
| Segment | 2024 | 2025 | 2026 | 2027 | 2028 | 2029 | CAGR (%) |
|---|---|---|---|---|---|---|---|
| BFSI | 201.7 | 221.1 | 243.1 | 268 | 302 | 340.7 | 11.1 |
| ENERGY & UTILITIES | 44.2 | 47.7 | 51.9 | 56.9 | 62.4 | 69 | 9.3 |
| GOVERNMENT | 204.9 | 233.3 | 267.6 | 309.3 | 359.8 | 422.2 | 15.6 |
| HEALTHCARE | 204.1 | 237 | 277.2 | 326.6 | 385.9 | 460.2 | 17.7 |
| IT & ITES | 151.5 | 174.2 | 201.7 | 235.4 | 276 | 326.5 | 16.6 |
| MANUFACTURING | 162.3 | 179.1 | 199 | 222.8 | 251.2 | 285.6 | 12 |
| OTHER VERTICALS | 66.8 | 71.2 | 76.5 | 82.8 | 89.1 | 96.7 | 7.7 |
| RETAIL & ECOMMERCE | 80.7 | 87.9 | 96.4 | 106.5 | 118 | 132 | 10.3 |
| TELECOMMUNICATION | 107.5 | 121.2 | 137.6 | 157.4 | 181.4 | 210.9 | 14.4 |
| TRANSPORTATION & LOGISTICS | 118.6 | 132.3 | 148.5 | 168 | 191.6 | 220.3 | 13.2 |
| TOTAL | 1342.2 | 1505 | 1699.6 | 1933.6 | 2217.4 | 2564.2 | 13.8 |
Target Audience
- eGRC Software Vendors : Vendors need China-specific market insights to develop localized solutions, understand regulatory requirements, identify customer segments, and establish competitive positioning in this high-growth market.
- Enterprise Risk & Compliance Officers : Chinese enterprise leaders require market intelligence to benchmark their compliance investments, understand industry adoption trends, and justify eGRC platform implementations to stakeholders.
- Management Consulting Firms : Consultants advising Chinese enterprises on digital transformation and compliance strategies need detailed market data to support recommendations and validate eGRC investment business cases.
- Private Equity & Investment Firms : Investors evaluating opportunities in China's technology and compliance sectors require market sizing, growth projections, and regulatory drivers to assess eGRC company valuations and acquisition targets.
- System Integrators & Implementation Partners : Implementation partners serving Chinese enterprises need market insights to identify growth opportunities, understand customer pain points, and develop service offerings aligned with regional compliance needs.
Key Companies in the China eGRC Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| FIRST DATA CORPORATION | United States | Private Company | Merchant acquiring & POS processing,Issuer processing & network services,Integrated payments & software-led solutions, |
| CYNERGISTEK | United States | Private Company | Risk and program assessments (security, privacy, compliance),Technical testing and IT audits,Managed security, privacy, and program oversight services, |
| DIMENSION DATA | United Kingdom | Private Company | Managed Services (network, data center, end-user, support),Cloud & IT-as-a-Service (including Microsoft, contact center, mobility),System Integration & Professional Services, |
| TRANSUNION | United States | Public Company | Credit Reporting and Core Bureau Services,Analytics, Scoring, and Decisioning Solutions,Fraud, Identity, and Authentication Solutions, |
| EXPERIAN PLC | Ireland | Public Company | Business-to-Business – Credit & Risk Data,Business-to-Business – Software, AI & Decisioning,Business-to-Business – Marketing & Automotive Services, |
| EQUIFAX INC | United States | Public Company | Workforce Solutions (verification and employer services),U.S. Information Solutions (credit, fraud, marketing, mortgage),International Information Services, |
| CANON INC | Japan | Public Company | Printing Business Unit,Medical Business Unit,Imaging Business Unit, |
| CURA TECHNOLOGIES LTD | India | Public Company | Custom software development and application services,IT-enabled services and BPO (including call centers and back office),Analytics, data warehousing, AI and ML solutions, |
| EXL | United States | Public Company | Insurance digital operations and platforms,Healthcare and Life Sciences services,Banking, Capital Markets, and Diversified Industries, |
| WOLTERS KLUWER | Netherlands | Public Company | Health (clinical solutions and GenAI/agentic tools),Tax & Accounting (AI-powered cloud and on-premise suites),Financial & Corporate Compliance, |
| FIS | United States | Public Company | Banking Solutions (core, digital, fraud, card & retail payments),Capital Market Solutions (trading, lending, treasury & risk),Corporate and Other (wealth, retirement, item processing, ancillary), |
| MICROSOFT | United States | Public Company | Intelligent Cloud (Azure, server, GitHub, Nuance, services),Productivity & Business Processes (Microsoft 365, LinkedIn, Dynamics),Personal Computing (Windows, devices, gaming, search ads), |
| IBM | United States | Public Company | Software (hybrid cloud and AI platforms),Consulting (strategy, technology services, intelligent operations),Infrastructure (servers, storage, lifecycle services), |
| ORACLE | United States | Public Company | Cloud applications (Fusion ERP/EPM/SCM/HCM, NetSuite, Oracle Health, CX),Cloud and license infrastructure (Oracle Database, MySQL, Java, middleware, OCI, autonomous database, AI/ML/IoT/blockchain services),Hardware and related support (engineered systems, servers, storage, OS, management software), |
| SAP | Germany | Public Company | Core ERP and Finance (SAP S/4HANA),Human Experience Management (SuccessFactors),Spend Management and Business Network, |
| SERVICENOW | United States | Public Company | IT Service & Operations Management (including OT management),Customer & Field Service / Sales & Order Management,Employee Workflows (HR, Workplace, Legal, Source-to-Pay), |
| THOMSON REUTERS | Canada | Public Company | Legal Professionals,Tax, Audit & Accounting Professionals,Corporates, |
| MEGA INTERNATIONAL | Taiwan | Private Company | Demand, time, and savings deposits,Corporate and retail lending (incl. mortgages),Foreign exchange and remittances, |
| MPHASIS | India | Public Company | Banking and Financial Services,Insurance,Technology, Media & Telecom, |
FIRST DATA CORPORATION
First Data Corporation is a private company founded in 1992 in the United States with 19,000 employees. The company operates as a major player in financial services and payment processing.
CYNERGISTEK
Cynergistek is a private company founded in 1995 in the United States with 89 employees. The company specializes in healthcare compliance and security solutions.
DIMENSION DATA
Dimension Data is a private company founded in 1983 in the United Kingdom with 11,032 employees. The company offers IT services, consulting, and managed services to enterprise clients.
TRANSUNION
TransUnion is a public company founded in 1968 in the United States with 13,500 employees. The company operates as a leading provider of credit information and risk management solutions.
EXPERIAN PLC
Experian PLC is a public company founded in 1826 and based in Ireland with 25,200 employees. The company is a global leader in credit reporting, data analytics, and consumer services.
EQUIFAX INC
Equifax Inc. is a public company founded in 1899 in the United States with 15,000 employees. The company provides credit information, data analytics, and identity verification services.
CANON INC
Canon Inc. is a public company founded in 1933 in Japan with 165,547 employees. The company is a global leader in imaging and optical products, including cameras, printers, and office equipment.
CURA TECHNOLOGIES LTD
Cura Technologies Ltd. is a public company founded in 1991 and based in India. The company provides technology and software services to clients across various industries.
EXL
EXL is a public company founded in 1999 in the United States with 65,000 employees. The company provides business process management, analytics, and digital transformation services.
WOLTERS KLUWER
Wolters Kluwer is a public company founded in 1836 in the Netherlands with 19,812 employees. The company is a global provider of professional information, software solutions, and services.
FIS
FIS is a public company founded in 1968 in the United States with 44,000 employees. The company provides financial services technology, including banking, payments, and capital markets solutions.
MICROSOFT
Microsoft is a public company founded in 1975 in the United States with 228,000 employees. The company is a global technology leader providing software, cloud services, and enterprise solutions.
IBM
IBM is a public company founded in 1911 in the United States with 264,300 employees. The company is a global technology and consulting leader providing hardware, software, and IT services.
ORACLE
Oracle is a public company founded in 1977 in the United States with 141,000 employees. The company is a leading provider of database software, cloud computing, and enterprise solutions.
SAP
SAP is a public company founded in 1972 in Germany with 111,038 employees. The company is a global leader in enterprise resource planning (ERP) software and business solutions.
SERVICENOW
ServiceNow is a public company founded in 2004 in the United States with 29,187 employees. The company provides cloud-based workflow and IT service management solutions.
THOMSON REUTERS
Thomson Reuters is a public company founded in 1799 in Canada with 27,100 employees. The company is a global provider of news, information, and analytics for professional markets.
MEGA INTERNATIONAL
Mega International is a private company founded in 1971 in Taiwan with 7,120 employees. The company provides enterprise software and business solutions to clients worldwide.
MPHASIS
Mphasis is a public company founded in 1992 in India with 23,452 employees. The company provides IT services, digital transformation, and business process management solutions.
Reasons to Buy this Report
- Market Size & Growth Validation : Quantified market data demonstrating China's eGRC market growing from $1,342.2M to $2,564.2M (2029) validates investment opportunities and supports strategic planning for market entry or expansion.
- Regulatory Landscape Intelligence : Comprehensive insights into China's evolving regulatory complexity and data protection requirements enable organizations to anticipate compliance demands and position eGRC solutions effectively.
- Competitive Positioning Strategy : Detailed China-specific market analysis provides competitive intelligence to identify market gaps, differentiation opportunities, and optimal positioning strategies within the high-growth Chinese eGRC sector.
- Investment Decision Support : Reliable forecasting data and growth trajectory analysis support informed investment decisions, resource allocation, and go-to-market strategies tailored to China's unique market dynamics.
- Digital Transformation Alignment : Understanding China's digital transformation initiatives and their correlation with eGRC adoption enables vendors to align solutions with enterprise modernization priorities and regulatory mandates.
Frequently asked questions
What is the current size of China's eGRC market?
China's eGRC market was valued at $1,342.2 million in 2024 and is expected to grow to $2,564.2 million by 2029.
What is the projected growth rate for China's eGRC market?
China's eGRC market is projected to grow at a compound annual growth rate (CAGR) of 13.8% from 2024 to 2029.
Which industries are driving eGRC adoption in China?
Financial services, technology, manufacturing, and multinational corporations in China are primary drivers of eGRC solution adoption due to regulatory and compliance requirements.
What regulatory factors are influencing China's eGRC market growth?
China's stricter data protection regulations, cybersecurity mandates, and internal control requirements are key factors accelerating eGRC market expansion.
How does China's eGRC market growth compare to global trends?
China's 13.8% CAGR slightly exceeds the global eGRC market CAGR of 13.4%, indicating stronger regional demand and regulatory momentum.
RESEARCH METHODOLOGY
Get the Full eGRC Market Report
Full forecast, segment splits, and company analysis for all eGRC Market.
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report