Canada Microencapsulation Market (2024-2029)
The Canada Microencapsulation Market was valued at $526.2 Million in 2024 and projected to reach to $750.3 Million by 2029, representing a compound annual growth rate of 7.4%. Canada's microencapsulation market is poised for measured expansion driven by increasing consumer demand for functional foods, clean-label products, and nutritional fortification.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Canada Microencapsulation Market Trends and Insights
- Valued at $526.2 million in 2024, Canada's market is projected to expand to $750.3 million by 2029, reflecting a compound annual growth rate of 7.4%.
- This growth trajectory demonstrates Canada's increasing adoption of microencapsulation technologies for flavor masking, nutrient protection, and functional ingredient delivery in food applications. The Canadian market benefits from strong regulatory frameworks, advanced food processing infrastructure, and rising consumer demand for fortified and functional foods.
- Canada's position as a major food exporter and processor drives investment in microencapsulation innovation.
- Between 2024 and 2029, Canada is expected to see accelerated adoption across dairy, beverage, and nutraceutical segments, supported by both domestic consumption trends and export-oriented manufacturing initiatives..
Key Market Statistics
- CAGR (2024-2029) 7.4% CAGR
- Market Size, 2024 ~USD 526.2 Million
- Forecast, 2029 ~USD 750.3 Million
- Country Canada
Canada Microencapsulation Market Overview
Market Valuation :
Canada's microencapsulation market reached $526.2 million in 2024, with projected growth to $750.3 million by 2029, representing a 7.4% CAGR specific to the Canadian market.
Growth Differential :
Canada's 7.4% CAGR trails the global average of 9.4%, indicating a more conservative but stable adoption rate within the North American food and beverage sector compared to international markets.
Key Applications :
Canadian food and beverage manufacturers are increasingly leveraging microencapsulation for flavor masking, nutrient protection, and extended shelf-life solutions in functional foods and dietary supplements.
Regional Position :
As part of North America's mature food technology landscape, Canada demonstrates steady demand from established processors seeking to enhance product formulations and meet consumer wellness trends.
Canada Microencapsulation Market Dynamics
- Canadian food manufacturers are investing in microencapsulation technologies to address flavor challenges in plant-based alternatives and probiotic formulations, aligning with regional health-conscious consumer preferences.
- The market benefits from Canada's strong regulatory framework and established food processing infrastructure, supporting innovation in encapsulation techniques for vitamins, minerals, and bioactive compounds.
- Growth will be sustained by collaborations between domestic food companies and technology providers, alongside rising adoption in the nutraceutical and fortified beverage segments throughout the forecast period..
Market Ecosystem
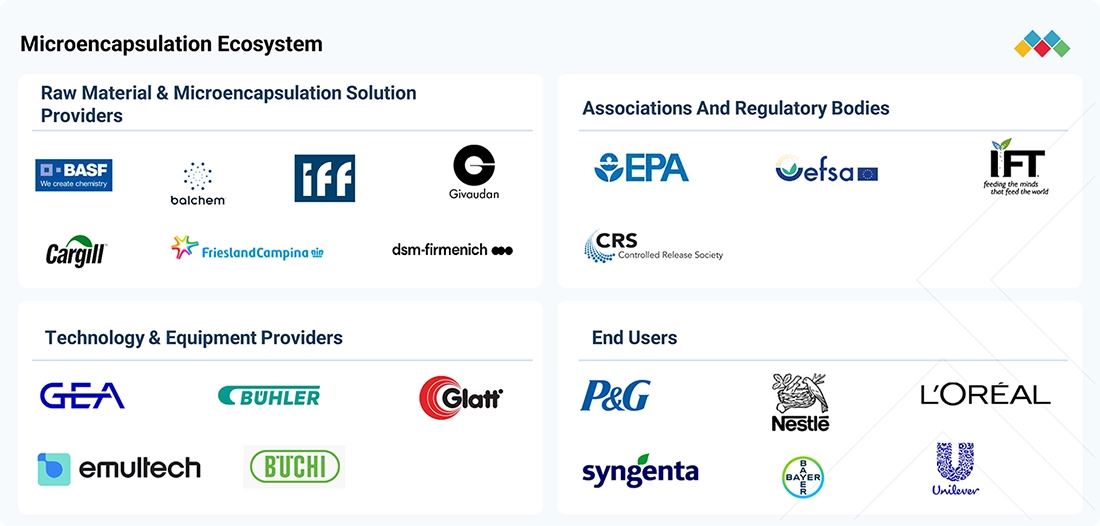
MICROENCAPSULATION MARKET TRENDS, GROWTH, AND FORECAST [LATEST]: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Uses perfume microcapsules in fabric-enhancer and laundry products, including products under brands such as Tide and Downy. The microcapsules deposit on fabrics during laundering and release fragrance when the fabric is subsequently rubbed or worn. | Provides long-lasting fragrance after washing, with controlled fragrance release during fabric use. P&G reported commercialization of laundry products containing functional perfume microcapsules across North America and Western Europe. |
 |
Has incorporated fragrance microcapsules into laundry and fabric-care formulations, where capsules are designed to remain on fabrics after washing and release fragrance through physical interaction with the fabric. | Supports fragrance retention and delayed release, extending the freshness experience beyond the washing process. |
 |
Uses microencapsulation in Demand CS insecticide, a commercial formulation containing microencapsulated lambda-cyhalothrin for professional pest management. | The microcapsules protect the active ingredient and release it over time, providing fast knockdown and long-lasting residual insect control. Demand CS can provide control for up to 90 days. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Key Takeaways
- Canada's microencapsulation market is valued at $526.2 million in 2024 and is forecast to reach $750.3 million by 2029.
- Canada is experiencing a 7.4% CAGR, driven by demand for functional foods and advanced food processing technologies.
- Canada's strong regulatory environment and export-focused food industry support sustained microencapsulation adoption.
- Canada's market growth is concentrated in dairy, beverages, and nutraceuticals, with expansion expected through 2029.
Microencapsulation Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | GAS (Core Material Form) |
| Forecast Period | 2024-2029 |
| Growth Rate | CAGR of 9.4% from 2024 to 2029 |
| Largest Segment | CORE (Core & Shell Material) |
| Market Size Base Year (Billions) | ~USD 15.36 (2024) |
| Revenue Forecast (Billions) | ~USD 24.07 (2029) |
| Segments Covered | Core Material, Subtypes, Core Material Form, Core & Shell Material, Shell Material, Technology, End-Use Industry |
Canada Microencapsulation Market Report Segmentation
7 segment dimensions are covered across the global market.
By Core Material
- Active Ingredients
- Agricultural Inputs
- Food & Beverage Ingredients
- Fragrances
- Other Core Materials
- Phase Change Materials
By Subtypes
- Additives
- Enzymes
- Essential Oils
- Prebiotics & Probiotics
- Vitamins & Minerals
By Core Material Form
- Gas
- Liquid
- Solid
By Core & Shell Material
- Core
- Shell
By Shell Material
- Carbohydrates
- Gums & Resins
- Lipids
- Polymers
- Proteins
By Technology
- Dripping Technologies
- Emulsion Technologies
- Other Technologies
- Spray Technologies
By End-Use Industry
- Agriculture
- Building & Construction
- Food & Beverage
- Household & Personal Care
- Other End-Use Industries
- Pharmaceuticals
- Textile
CANADA: MICROENCAPSULATION MARKET, BY END-USE INDUSTRY, 2024–2029
| Segment | 2024 | 2025 | 2026 | 2027 | 2028 | 2029 | CAGR (%) |
|---|---|---|---|---|---|---|---|
| AGRICULTURE | 51 | 55.5 | 59.8 | 65.1 | 71.8 | 77.5 | 8.7 |
| BUILDING & CONSTRUCTION | 22.4 | 23.7 | 24.7 | 26.1 | 27.8 | 29.1 | 5.3 |
| FOOD & BEVERAGE | 60.7 | 65.7 | 70.5 | 76.5 | 83.9 | 90.3 | 8.3 |
| HOUSEHOLD & PERSONAL CARE | 70.1 | 75.7 | 81.2 | 87.9 | 96.2 | 103.3 | 8.1 |
| OTHER END-USE INDUSTRIES | 10.2 | 10.6 | 10.9 | 11.4 | 12 | 12.3 | 3.7 |
| PHARMACEUTICALS | 283.5 | 303.2 | 321.5 | 344.5 | 373.4 | 396.8 | 7 |
| TEXTILE | 28.2 | 30.3 | 32.4 | 35 | 38.3 | 41 | 7.8 |
| TOTAL | 526.2 | 564.7 | 601.1 | 646.4 | 703.4 | 750.3 | 7.4 |
Target Audience
- Food & Beverage Manufacturers : Canadian food processors need market-specific data to evaluate microencapsulation adoption for product innovation, competitive differentiation, and meeting consumer demands for functional and fortified products.
- Ingredient & Technology Suppliers : Microencapsulation technology providers and ingredient suppliers require Canada market insights to identify growth opportunities, assess demand for encapsulation solutions, and develop targeted sales strategies.
- Investment & Private Equity Firms : Investors evaluating opportunities in Canada's food technology sector need reliable market sizing and growth projections to assess portfolio companies, identify acquisition targets, and evaluate market potential.
- Regulatory & Compliance Professionals : Quality assurance and regulatory teams need Canada-specific market context to understand approved applications, competitive formulations, and regulatory trends shaping microencapsulation adoption in Canadian food products.
- Strategic Consultants & Analysts : Business consultants and market analysts require granular Canada data to support client advisory work, competitive benchmarking, and strategic planning for food and beverage companies operating in the Canadian market.
Reasons to Buy this Report
- Canada-Specific Market Sizing : Access precise valuation data for Canada's microencapsulation market with detailed 2024 baseline ($526.2M) and 2029 forecasts ($750.3M), enabling accurate budget allocation and investment planning for Canadian operations.
- Competitive Landscape Intelligence : Understand Canada's unique market dynamics, growth rates (7.4% CAGR), and regional adoption patterns distinct from global trends, helping identify competitive advantages and market entry strategies specific to Canadian food manufacturers.
- Regulatory & Application Insights : Gain insights into Canada's regulatory environment and preferred microencapsulation applications in flavor masking, nutrient protection, and functional foods, supporting product development aligned with Canadian market requirements.
- Strategic Growth Opportunities : Identify high-potential segments within Canada's $224.1M growth opportunity (2024-2029), including plant-based alternatives, probiotics, and fortified beverages, to prioritize R&D and commercialization efforts.
- Stakeholder Decision Support : Equip executives, product managers, and investors with Canada-focused market data to support strategic decisions, partnership evaluations, and resource allocation for the North American food and beverage sector.
Frequently asked questions
What is the current size of Canada's microencapsulation market?
Canada's microencapsulation market was valued at $526.2 million in 2024 and is projected to grow to $750.3 million by 2029.
What is the growth rate of Canada's microencapsulation market?
Canada's microencapsulation market is growing at a compound annual growth rate (CAGR) of 7.4% from 2024 to 2029.
Which food and beverage segments drive Canada's microencapsulation demand?
Canada's primary segments include dairy products, functional beverages, and nutraceuticals, where microencapsulation enhances nutrient stability and flavor delivery.
What factors support microencapsulation growth in Canada?
Canada's growth is supported by strong regulatory frameworks, advanced food processing capabilities, rising functional food demand, and export-oriented manufacturing.
How does Canada's market compare to global microencapsulation trends?
Canada's 7.4% CAGR is slightly below the global average of 9.4%, reflecting a more mature but stable market with consistent demand from established food processors.
RESEARCH METHODOLOGY
This study employed two primary approaches to estimate the current size of the microencapsulation market. Exhaustive secondary research was carried out to collect information on shell material, core material, core material form, technology, end-use industry, functionality, and region for the market. The next step involved validating these findings, assumptions, and sizing with industry experts across the value chain through primary research. The top-down and bottom-up approaches were employed to estimate the complete market size. Thereafter, data triangulation was used to estimate the market size of segments and subsegments.
Secondary Research
This research study used extensive secondary sources—directories and databases such as Bloomberg Businessweek and Factiva—to identify and collect information for a technical, market-oriented, and commercial market study. In the secondary research process, sources such as annual reports, press releases and investor presentations of companies, white papers, microencapsulation-related journals, certified publications, articles from recognized authors, directories, and databases were referred to identify and collect information. Secondary research was mainly used to obtain key information about the industry’s supply chain, the pool of key players, and market classification and segmentation based on industry trends to the bottom-most level, regional markets, and key developments from market- and technology-oriented perspectives.
Primary Research
Extensive primary research was conducted after obtaining information regarding the microencapsulation market scenario through secondary research. Several primary interviews were conducted with market experts from the demand and supply sides. Primary data was collected through questionnaires, emails, and telephonic interviews. Supply-side sources included industry experts such as chief experience officers (CXOs); vice presidents (VPs); directors from business development, marketing, research, and development teams; and key executives from distributors and key opinion leaders.
Primary interviews were conducted to gather insights, including market statistics, revenue data from products and services, market breakdowns, market size estimations, market forecasting, and data triangulation. Primary research helped understand various trends related to core material, core material form, shell material type, technology, end-user industry, functionality, and region.
Stakeholders from the demand side, including pharmaceutical companies, food and beverage manufacturers, nutraceutical and dietary supplement companies, household and personal care manufacturers, agricultural input producers, and textile manufacturers, were interviewed to understand buyers’ perspectives on microencapsulation technologies, purchasing trends, formulation requirements, sourcing preferences, and the outlook for the microencapsulation market.
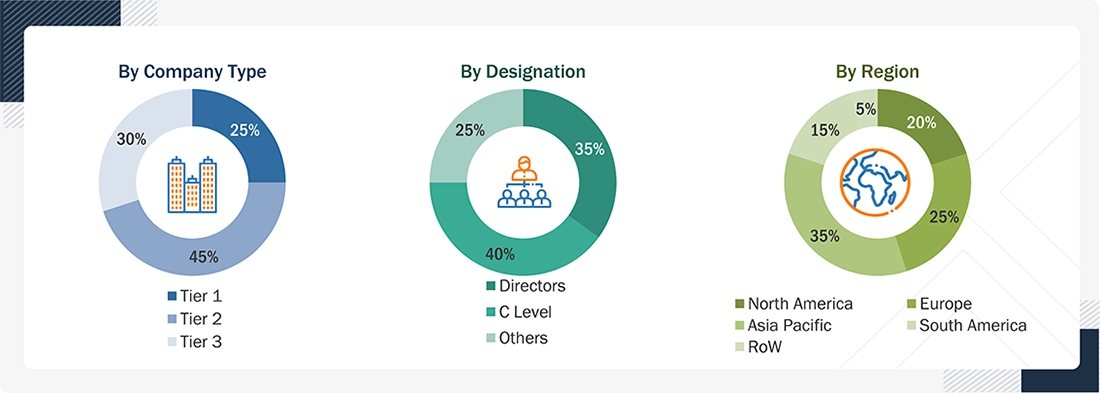
Notes:
- The three tiers of the companies are defined based on their total revenues in 2025, based on the availability of financial data.
- Tier 1: Revenue > USD 1 billion; Tier 2: USD 100 million ≤ Revenue ≤ USD 1 billion; Tier 3: Revenue < USD 100 million
- Others include product managers, R&D managers, technical managers, production managers, procurement managers, sales and marketing managers, business development managers, application specialists, and quality assurance managers.
|
COMPANY |
DESIGNATION |
|
BASF (Germany) |
Product Development Manager |
|
FrieslandCampina (Netherlands) |
Senior R&D Scientist |
|
DSM-Firmenich (Switzerland) |
Global Marketing Director |
|
GIVAUDAN (Switzerland) |
Head of Microencapsulation Technology |
|
International Flavors & Fragrances Inc. (US) |
Senior Research Scientist |
|
Sensient Technologies Corporation (US) |
Business Development Manager |
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
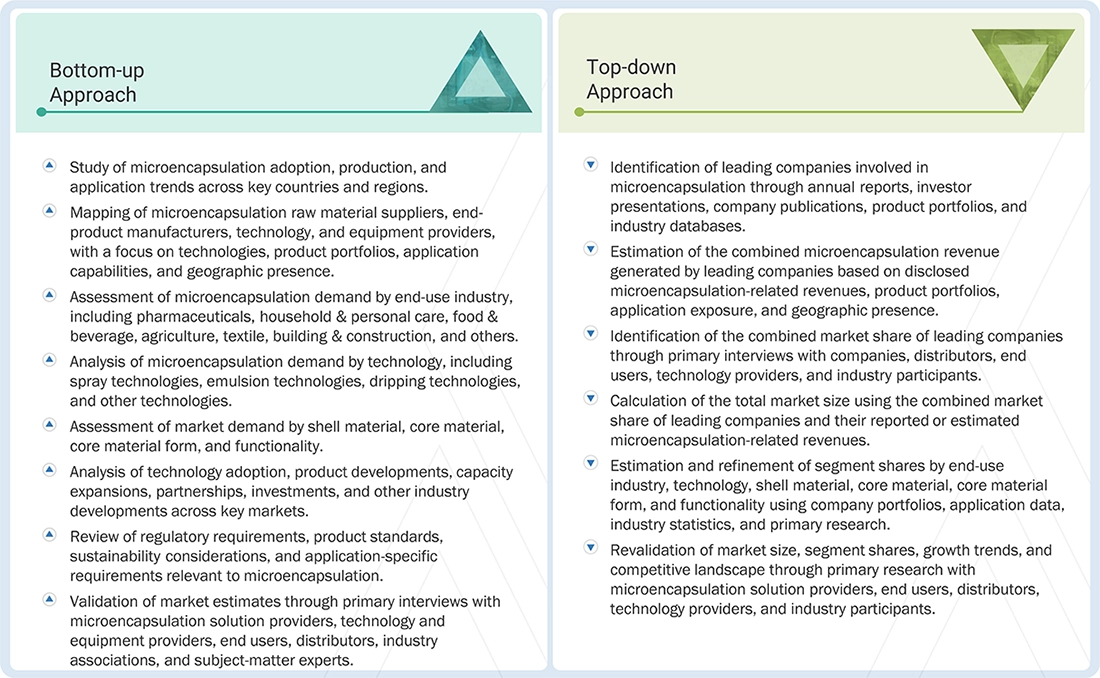
The top-down and bottom-up approaches were used to estimate and validate the total size of the microencapsulation market. These approaches were also used extensively to determine the size of various market subsegments.
The research methodology used to estimate the market size includes the following details:
- The key players in the industry and the overall market were identified through extensive secondary research.
- All shares, splits, and breakdowns were determined using secondary sources and verified through primary sources.
- All possible parameters that affect the market covered in this research study were accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain final quantitative and qualitative data.
- The research included the study of reports, reviews, and newsletters of top market players, along with extensive interviews for opinions from leaders, such as CEOs, directors, and marketing executives.
Microencapsulation Market: Bottom-up and Top-down Approaches
Data Triangulation
After determining the overall market size from the estimation process explained above, the total market was split into several segments and subsegments. The data triangulation procedure was employed, wherever applicable, to estimate the overall microencapsulation market and obtain precise statistics for all segments and subsegments. The data was triangulated by studying various factors and trends from the demand and supply sides. The market size was also validated using the top-down and bottom-up approaches.
Market Definition
According to the article “A Review On Microspheres,” published by R. B. Saudagar and Kanchan T. Mandlik in the International Journal of Pharma and Bio Sciences, “Microencapsulation is a process in which tiny particles or droplets are surrounded by a coating to give small capsules. In simple terms, a microcapsule is a small sphere with a uniform wall around it. The material inside the microcapsule is called the core, internal phase, or fill, while the wall is sometimes called the shell, coating, or membrane. Most microcapsules have diameters between a few micrometers and a few millimeters.”
Key Stakeholders
-
Food & Beverage Manufacturers
- Fortified food producers
- Functional beverage companies
- Dietary supplement manufacturers
-
Pharmaceutical Companies
- Generic drug manufacturers
- Specialty pharmaceutical firms
-
Cosmetic & Personal Care Brands
- Skincare and hair care product manufacturers
- Cosmetic companies
-
Nutraceutical Companies
- Health supplement brands
- Functional food producers
-
Agricultural Sector
- Fertilizer and pesticide manufacturers
- Seed treatment companies
-
Regulatory Bodies and Institutions
- US Food and Drug Administration (FDA)
- European Food Safety Authority (EFSA)
- Health Canada
- Food Safety and Standards Authority of India (FSSAI)
- World Health Organization (WHO)
- Codex Alimentarius Commission
- European Medicines Agency (EMA)
- National Institutes of Health (NIH)
- Institute of Food Technologists (IFT)
- American Chemical Society (ACS)
-
Distributors and Wholesalers
- Ingredient and equipment distributors
-
R&D Institutions
- Academic research organizations
- Private research labs
Report Objectives
- To determine and project the size of the microencapsulation market based on shell material, core material, core material form, technology, end-use industry, functionality, and region over the forecast period
- To identify key growth opportunities by analyzing the largest and fastest-growing segments across regions
- To provide detailed insights on factors influencing market growth, including drivers, restraints, opportunities, and challenges
- To evaluate market opportunities for stakeholders and present the competitive landscape of leading players
- To analyze micro-markets with respect to individual growth trends, future potential, and their contribution to the overall market
- To identify and profile key companies operating in the microencapsulation market
- To assess the competitive environment and highlight key strategies adopted by major players across regions
Available customizations:
Based on the provided market data, MarketsandMarkets offers customizations to meet company-specific scientific needs. The following customization options are available for the report:
PRODUCT ANALYSIS
- Product matrix, which gives a detailed comparison of the product portfolio of each company.
GEOGRAPHIC ANALYSIS
With the given market data, MarketsandMarkets offers customizations according to company-specific scientific needs.
- Further breakdown of Rest of Europe microencapsulation market by key country
- Further breakdown of Rest of Asia Pacific microencapsulation market by key country
- Further breakdown of Rest of South America microencapsulation market by key country
COMPANY INFORMATION
- Detailed analyses and profiling of additional market players (up to five)
Get the Full Microencapsulation Market Report
Full forecast, segment splits, and company analysis for all Microencapsulation Market.
- US Microencapsulation Market
- Mexico Microencapsulation Market
- Germany Microencapsulation Market
- UK Microencapsulation Market
- France Microencapsulation Market
- Italy Microencapsulation Market
- Spain Microencapsulation Market
- China Microencapsulation Market
- Japan Microencapsulation Market
- India Microencapsulation Market
- Brazil Microencapsulation Market
- Argentina Microencapsulation Market
- Rest Of Europe Microencapsulation Market
- Rest Of Asia Pacific Microencapsulation Market
- Rest Of South America Microencapsulation Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report