China More Electric Aircraft Market (2024-2029)
The China More Electric Aircraft Market was valued at $292.9 Million in 2024 and projected to reach to $418.5 Million by 2029, representing a compound annual growth rate of 7.4%. China's More Electric Aircraft Market is poised for sustained growth driven by the country's expanding aerospace industry and commitment to environmental sustainability.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
China More Electric Aircraft Market Trends and Insights
- China's aerospace sector is increasingly adopting more electric aircraft (MEA) technologies to enhance fuel efficiency, reduce emissions, and meet stringent environmental regulations.
- The growth trajectory reflects China's commitment to modernizing its commercial and regional aviation fleets while advancing domestic aircraft manufacturing capabilities. Driving China's market expansion are investments in next-generation aircraft platforms, government support for sustainable aviation initiatives, and rising demand from Chinese carriers for fuel-efficient solutions.
- China's position as a major aircraft operator and emerging aircraft manufacturer positions the country as a critical hub for MEA technology adoption.
- Between 2024 and 2029, China is expected to see accelerated integration of electrical systems across propulsion, hydraulics, and environmental control systems, supported by both domestic innovation and international partnerships within the aerospace supply chain..
Key Market Statistics
- CAGR (2024-2029) 7.4% CAGR
- Market Size, 2024 ~USD 292.9 Million
- Forecast, 2029 ~USD 418.5 Million
- Country China
China More Electric Aircraft Market Overview
Market Valuation Growth :
China's More Electric Aircraft Market is valued at USD 292.9 million in 2024 and is projected to grow to USD 418.5 million by 2029, demonstrating robust expansion in the aerospace sector.
Regulatory Compliance Driver :
Stringent environmental regulations in China are accelerating the adoption of MEA technologies, as manufacturers seek to reduce emissions and improve fuel efficiency to meet government standards.
Domestic Aviation Expansion :
China's rapidly growing commercial aviation sector and increasing domestic aircraft production capabilities are creating significant demand for more electric aircraft systems and components.
Technology Modernization :
Chinese aerospace manufacturers are investing heavily in MEA technologies to enhance operational efficiency, reduce maintenance costs, and compete in the global aviation market.
China More Electric Aircraft Market Dynamics
- The 7.4% CAGR reflects increasing investments in advanced aircraft technologies and the modernization of domestic aviation fleets.
- Government initiatives promoting clean energy and reduced carbon emissions are accelerating MEA adoption among Chinese manufacturers and operators. The market will benefit from China's growing commercial aviation sector, rising passenger demand, and the development of indigenous aircraft programs.
- Strategic partnerships between domestic aerospace companies and international technology providers will further enhance MEA capabilities.
- By 2029, China is expected to establish itself as a significant hub for more electric aircraft manufacturing and innovation in the Asia-Pacific region..
Market Ecosystem
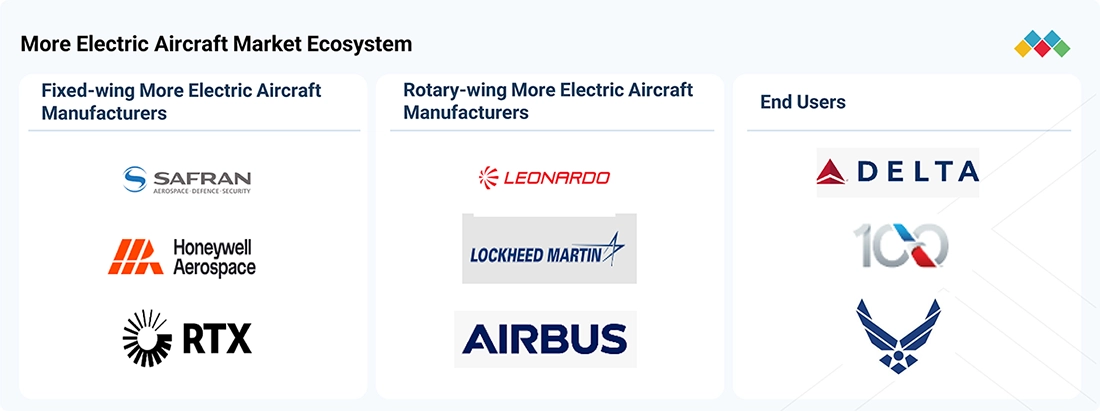
MORE ELECTRIC AIRCRAFT MARKET SIZE, SHARE & GROWTH: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Safran Electrical & Power develops electrical power generation, conversion and distribution systems for more-electric commercial and military aircraft. Its portfolio includes starter-generators, generators, power management systems, electrical distribution equipment, and wiring systems designed to increase onboard electrical power availability while replacing selected hydraulic and pneumatic functions. | Enables higher onboard electrical power availability | Reduces dependence on hydraulic and pneumatic systems | Supports weight and fuel-efficiency improvements | Enables intelligent electrical power distribution | Supports higher electrical loads on next-generation aircraft |
 |
Honeywell Aerospace provides aircraft electrical power generation and management systems, including generators, auxiliary power units, power distribution equipment, and high-power turbogenerators. Its technologies support more-electric and hybrid-electric aircraft architectures by supplying increased electrical power for avionics, environmental control, actuation, and other onboard systems. | Provides high-density electrical power generation | Supports increased aircraft electrical loads | Enables electrification of secondary aircraft systems | Improves power-management efficiency | Supports more-electric and hybrid-electric aircraft architectures |
 |
Collins Aerospace (RTX) develops aircraft electrical generation, conversion and distribution technologies for commercial and military platforms. Its portfolio includes variable-frequency generators, high-voltage DC systems, solid-state power distribution, and advanced electric power architectures. Collins is also developing high-voltage systems through programs such as HECATE to support next-generation more-electric and hybrid-electric aircraft. | Enables high-voltage aircraft electrical architectures | Supports greater electrical content per aircraft | Reduces system weight through advanced power distribution | Enables intelligent load management and fault isolation | Supports future hybrid-electric and more-electric aircraft programs |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Airport Systems
- Antennas
- Sensors
- Aeronautical Information Management (AIM)
- Digital Signage
- Face Recognition
- SYSTRA LTD.
- Thales group
- Idaho Strategic Resources, Inc.
- HONEYWELL INTERNATIONAL INC.
- Leidos Holdings, Inc.
Aviation
- Narrow Body Aircraft
- Wide Body Aircraft
- Military Helicopters
- Special Mission Aircraft
- Fighter Aircraft
- HONEYWELL INTERNATIONAL INC.
- COLLINS AEROSPACE
- Thales group
- Safran group
- HEICO Corporation
Defence Platforms And Systems
- Sensors
- Unmanned Ground Vehicles (UGV)
- Fighter Aircraft
- Special Mission Aircraft
- Antennas
- BAE Systems plc
- Thales group
- LOCKHEED MARTIN CORPORATION
- Northrop Grumman Corporation
- L3Harris Technologies, Inc.
Key Takeaways
- China's More Electric Aircraft Market is valued at USD 292.9 million in 2024 and is forecast to grow to USD 418.5 million by 2029 at a 7.4% CAGR.
- China's aerospace modernization initiatives and environmental regulations are driving adoption of MEA technologies across commercial and regional aircraft fleets.
- China's emerging position as an aircraft manufacturer creates significant opportunities for domestic MEA component suppliers and system integrators.
- Government support for sustainable aviation and fuel efficiency improvements positions China as a key growth market for electrical aircraft systems through 2029.
More Electric Aircraft Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | ROTARY-WING (Platform) |
| Forecast Period | 2024–2029 |
| Growth Rate | CAGR of 7.6% from 2024 to 2029 |
| Largest Segment | FIXED-WING (Platform) |
| Market Size Base Year (Billions) | ~USD 5.55 (2024) |
| Revenue Forecast (Billions) | ~USD 8.01 (2029) |
| Segments Covered | End User, Application, Platform, System, Type, Component |
China More Electric Aircraft Market Report Segmentation
6 segment dimensions are covered across the global market.
By End User
- Civil
- Military
By Application
- Energy Storage
- Power Conversion
- Power Distribution
- Power Generation
By Platform
- Fighter Jets
- Fixed-Wing
- Fixed–Wing
- Narrow-Body Aircraft
- Regional Aircraft
- Rotary-Wing
- Rotary–Wing
- Wide-Body Aircraft
By System
- Aircraft System
- Aircraft Systems
- Airframe Systems
- Propulsion Systems
By Type
- Accessory Drive Systems
- Busbars
- Cabin Interior Systems
- Connectors & Connector Accessories
- Electric
- Electrical Backup Hydraulic Actuators (Ebha)
- Electro-Hydrostatic Actuators (Eha)
- Electro-Mechanical Actuators (Ema)
- Environmental Control Systems
- Flight Control System
- Flight Control Systems
- Fuel Management Systems
- Hybrid Electric
- Inverters
- Landing Gear Systems
- Power Converters
- Power Management Systems
- Rectifiers
- Thrust Reverser Systems
- Wires & Cables
By Component
- Actuators
- Auxiliary Power Units (Apu)
- Distribution Devices
- Electric Pumps
- Generators
- Power Electroincs
- Power Electronics
- Power Sources
- Starter Generators
- Valves
- Vscf Generators
CHINA: MORE ELECTRIC AIRCRAFT MARKET, BY END USER, 2024–2029
| Segment | 2024 | 2025 | 2026 | 2027 | 2028 | 2029 | CAGR (%) |
|---|---|---|---|---|---|---|---|
| CIVIL | 276.6 | 294.7 | 320.6 | 359.3 | 371.6 | 395.8 | 7.4 |
| MILITARY | 16.3 | 17.2 | 18.5 | 20.6 | 21.3 | 22.7 | 6.9 |
| TOTAL | 292.9 | 311.8 | 339.1 | 380 | 392.9 | 418.5 | 7.4 |
Target Audience
- Aerospace Manufacturers : Chinese and international aircraft manufacturers need detailed market insights to develop MEA products, optimize designs for Chinese regulations, and capture growing domestic demand.
- Component & Systems Suppliers : Suppliers of electrical systems, power distribution, and avionics require China-specific data to identify OEM partnerships, forecast demand, and align production with market growth.
- Investment & Private Equity Firms : Investors evaluating opportunities in China's aerospace sector need validated market sizing and growth projections to assess portfolio companies and identify acquisition targets.
- Government & Policy Bodies : Chinese aviation authorities and policy makers require market intelligence to inform industrial policy, environmental standards, and strategic aerospace development initiatives.
- Consulting & Strategy Firms : Management consultants advising aerospace clients need China-specific market data to develop go-to-market strategies, competitive analyses, and long-term business planning.
Key Companies in the China More Electric Aircraft Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| ARROW ELECTRONICS, INC | United States | Public Company | Semiconductor products and related services,Interconnect, passive, and electromechanical (IP&E) components,Computing and memory products, |
| NOLATO | Sweden | Public Company | Medical devices and components (catheters, breathing bags, silicone parts),Primary pharma packaging and drug-delivery plastics,Labware and TreffLab consumables, |
| ROCKWELL COLLINS INC | United States | Private Company | Commercial Systems (avionics and cabin management),Interior Systems (seating, galleys, cabin equipment),Government Systems (avionics, EW, targeting, navigation), |
| AVNET | United States | Public Company | Semiconductors,Interconnect, Passive, and Electromechanical (IP&E) Components,Embedded Solutions and Boards, |
| CYIENT | India | Public Company | Digital, Engineering & Technology,Design Led Manufacturing,Others (Networks, Operations, and Specialized Platforms), |
| SAFRAN S.A. | France | Public Company | Aerospace Propulsion,Aircraft Equipment, Defense and Aerosystems,Aircraft Interiors, |
| HONEYWELL INTERNATIONAL, INC. | United States | Public Company | Industrial Automation,Building Automation,Energy and Sustainability Solutions (UOP and related), |
| RTX | United States | Public Company | Collins Aerospace (avionics, interiors, mission systems, aftermarket),Pratt & Whitney (commercial and military engines, APU, MRO),Raytheon (sensors, effectors, mission software, space), |
| GENERAL ELECTRIC | United States | Public Company | Commercial Engines & Services,Defense & Propulsion Technologies, |
| PARKER HANNIFIN CORPORATION | United States | Public Company | Industrial motion and control systems (hydraulic, pneumatic, electromechanical),Filtration, fluid conveyance, and thermal management,Sealing, adhesives, and EMI shielding, |
| BAE SYSTEMS PLC | United Kingdom | Public Company | Air (combat aircraft, future combat air systems, support),Electronic Systems (EW, avionics, sensors, space electronics),Maritime (submarines, shipbuilding, support), |
| BOMBARDIER INC. | Canada | Public Company | New business aircraft,Aftermarket services (parts, service centers, smart services),Training and technical publications, |
| EMBRAER S.A. | Brazil | Public Company | Commercial Aviation (E-Jets/E2 family),Executive Aviation,Defense & Security, |
| LIEBHERR | Switzerland | Private Company | Earthmoving and Mining Equipment,Mobile, Crawler, and Tower Cranes,Material Handling and Maritime Cranes, |
| AMETEK, INC. | United States | Public Company | Process and analytical instruments (oil & gas, petrochemical, pharma, semiconductor, automation, F&B),Aerospace and defense sensors, embedded computing, power, and MRO,Power quality, metering, programmable power, EMC test equipment, |
| NABTESCO CORPORATION | Japan | Public Company | Precision reduction gears and motion-control components for industrial robots,Hydraulic equipment for construction and mobile machinery,Railway vehicle brake systems and door operators, |
| MOOG INC. | United States | Public Company | Military Aircraft,Commercial Aircraft,Space and Defense, |
| ASTRONICS CORPORATION | United States | Public Company | Aerospace – Lighting & Safety Systems,Aerospace – Electrical Power Generation & Distribution,Aerospace – Structures, Avionics & Certification Services, |
| ROLLS-ROYCE PLC | United Kingdom | Public Company | Civil Aerospace engines & services,Defence aero, naval & nuclear power,Power Systems (mtu power & propulsion), |
| EATON | Ireland | Public Company | Electrical components, power distribution, and power quality,Aerospace systems and components,Hydraulics and industrial systems, |
ARROW ELECTRONICS, INC
Arrow Electronics, Inc. is a publicly traded American electronics distributor founded in 1935, employing 22,230 people. The company serves as a major supplier of electronic components and services to customers worldwide.
NOLATO
Nolato is a Swedish public company established in 1938 with 5,607 employees, operating in the manufacturing and materials processing sectors.
ROCKWELL COLLINS INC
Rockwell Collins Inc. is a privately held American aerospace and defense company founded in 1933, employing 31,200 people in the design and manufacture of avionics and communication systems.
AVNET
Avnet is a publicly traded American technology distributor founded in 1921, with 14,869 employees providing IT solutions and supply chain services globally.
CYIENT
Cyient is an Indian public company founded in 1991 with 12,049 employees, offering engineering, design, and technology services across multiple industries.
SAFRAN S.A.
Safran S.A. is a French multinational public company founded in 1896 with 103,710 employees, specializing in aerospace, defense, and security technologies.
HONEYWELL INTERNATIONAL, INC.
Honeywell International, Inc. is a publicly traded American conglomerate founded in 1885 with 101,000 employees, operating across aerospace, building technologies, performance materials, and safety solutions.
RTX
RTX is a publicly traded American aerospace and defense company founded in 1934 with 180,000 employees, providing advanced technologies and systems for commercial and military applications.
GENERAL ELECTRIC
General Electric is a publicly traded American multinational conglomerate founded in 1892 with 57,000 employees, operating across power, renewable energy, aviation, and healthcare sectors.
PARKER HANNIFIN CORPORATION
Parker Hannifin Corporation is a publicly traded American manufacturer founded in 1917 with 57,950 employees, specializing in motion and control technologies for industrial and aerospace applications.
BAE SYSTEMS PLC
BAE Systems PLC is a publicly traded British multinational defense company founded in 1979 with 111,400 employees, providing advanced defense and security solutions globally.
BOMBARDIER INC.
Bombardier Inc. is a publicly traded Canadian company founded in 1902 with 18,000 employees, manufacturing business jets, commercial aircraft, and rail transportation equipment.
EMBRAER S.A.
Embraer S.A. is a publicly traded Brazilian aerospace company founded in 1969 with 21,122 employees, specializing in the design, development, and manufacture of commercial and military aircraft.
LIEBHERR
Liebherr is a privately held Swiss company founded in 1949 with 54,609 employees, manufacturing construction equipment, mining equipment, and aerospace components.
AMETEK, INC.
AMETEK, Inc. is a publicly traded American manufacturer founded in 1930 with 22,500 employees, producing electronic instruments and electromechanical devices for industrial and aerospace markets.
NABTESCO CORPORATION
Nabtesco Corporation is a publicly traded Japanese company founded in 2003 with 8,472 employees, specializing in precision equipment and control systems for aerospace and industrial applications.
MOOG INC.
Moog Inc. is a publicly traded American company founded in 1951 with 13,500 employees, designing and manufacturing precision motion and control systems for aerospace and defense industries.
ASTRONICS CORPORATION
Astronics Corporation is a publicly traded American company founded in 1968 with 2,700 employees, providing advanced technologies and systems for the aerospace and defense sectors.
ROLLS-ROYCE PLC
Rolls-Royce PLC is a publicly traded British company founded in 1884 with 43,162 employees, specializing in the design and manufacture of gas turbines and propulsion systems for aerospace and defense.
EATON
Eaton is a publicly traded company headquartered in Ireland and founded in 1911 with 97,303 employees, providing power management solutions and diversified industrial products globally.
Reasons to Buy this Report
- Market Size & Growth Validation : Obtain precise valuation data for China's MEA market (USD 292.9M in 2024) with verified 7.4% CAGR forecasts through 2029 to support investment decisions and business planning.
- Competitive Intelligence : Identify key Chinese aerospace manufacturers, technology providers, and market players adopting MEA solutions to benchmark competitive positioning and partnership opportunities.
- Regulatory & Policy Insights : Understand China-specific environmental regulations and government initiatives driving MEA adoption, enabling compliant product development and market entry strategies.
- Demand Forecasting : Access detailed projections for China's MEA market through 2029 to optimize supply chain planning, production capacity, and resource allocation for the region.
- Strategic Market Entry : Leverage China-focused market analysis to identify high-growth segments, emerging opportunities, and optimal timing for market entry or expansion in the aerospace sector.
Frequently asked questions
What is the current market size of More Electric Aircraft in China?
China's More Electric Aircraft Market was valued at USD 292.9 million in 2024 and is expected to grow at a 7.4% CAGR through 2029.
What is the projected market size for More Electric Aircraft in China by 2029?
China's More Electric Aircraft Market is projected to reach USD 418.5 million by 2029, representing significant growth from the 2024 baseline.
What factors are driving growth in China's More Electric Aircraft Market?
Key drivers include China's aerospace modernization efforts, environmental regulations, fuel efficiency demands from Chinese carriers, and government support for sustainable aviation technologies.
How does China's MEA market compare to global trends?
China's 7.4% CAGR is slightly below the global average of 7.6%, reflecting China's unique market dynamics and domestic aircraft manufacturing focus.
What role does China's aircraft manufacturing play in the MEA market?
China's emerging position as an aircraft manufacturer creates opportunities for domestic suppliers and system integrators to develop and integrate more electric aircraft technologies.
RESEARCH METHODOLOGY
The study involved four key activities to estimate the current size of the more electric aircraft market. Extensive secondary research was undertaken to collect information on the market, aircraft deliveries, fleet composition, aircraft electrical architectures, installed electrical systems, supplier contracts, airline and military procurement programs, and adjacent aerospace electrical systems markets. The findings, assumptions, and preliminary market estimates were validated through expert inputs across the value chain. A demand-side analysis was conducted to determine the overall market size. Finally, data triangulation was used to estimate the size of individual segments and subsegments within the more electric aircraft market
Secondary Research
During the secondary research phase, a wide range of sources was reviewed to identify and gather relevant information for the study. These sources included government procurement databases and budget documents; aircraft OEM annual reports, delivery databases, order books, production-rate guidance, investor presentations, product brochures, press releases, and contract announcements; electrical system and component supplier publications; airline fleet and annual reports; military procurement documents; GAMA, ICAO, IATA, FAA, EASA, CAAC, DGCA, SIPRI, and other aviation databases; technical white papers, journals, and certified publications; as well as articles from recognized authors, industry experts, and databases.
Primary Research
Primary research was structured after the collection of initial market information through secondary sources. Interviews and expert discussions were used to validate product positioning, electrical system content per aircraft, pricing, fitment rates, aircraft production and delivery trends, retrofit and replacement activity, procurement patterns, technology adoption, and market shares. Respondents represented both the demand and supply sides across key countries in North America, Europe, Asia Pacific, the Middle East, Latin America, and Africa. Primary information was gathered through questionnaires, email interactions, and telephonic or virtual interviews.
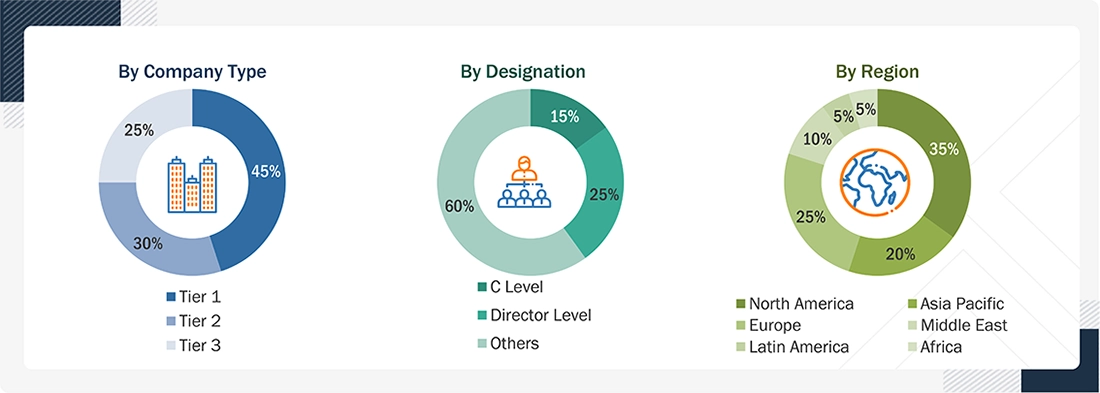
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
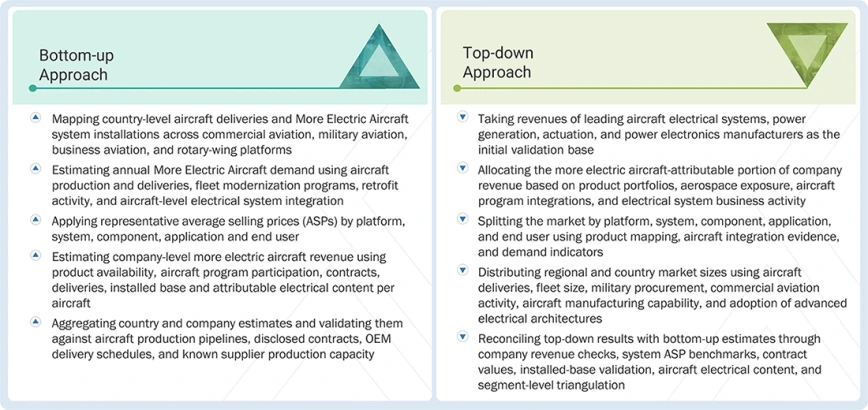
Top-down and bottom-up approaches were used to estimate and validate the size of the more electric aircraft market. The research methodology used to estimate the size of the market included the following details:
- Key players in the More Electric Aircraft market were identified through secondary research, and their market shares were determined through a combination of primary and secondary research. This included a review of annual and financial reports, aerospace electrical system revenues, aircraft program contracts, platform integration programs, supplier selections, product portfolios, and interviews with industry stakeholders.
- All percentage shares, splits, and breakdowns were derived using secondary sources and validated against supplier portfolios, procurement evidence, country demand, and expert inputs.
- All major parameters affecting the More Electric Aircraft market were considered in detail, including commercial and military aircraft deliveries, business jet and helicopter production, aircraft fleet modernization, electrical system content per aircraft, aircraft electrical generation requirements, retrofit and replacement activity, aircraft production rates, supplier contracts, backlog, technological developments, and increasing adoption of electrically driven aircraft systems. The resulting quantitative and qualitative data were consolidated and cross-validated for the final market model. This data was consolidated, enhanced with detailed input, analyzed by MarketsandMarkets, and presented in this report.
More Electric Aircraft Market: Top-Down and Bottom-Up Approach
Data Triangulation
After estimating the overall market size, the market was categorized into multiple segments and subsegments. The data triangulation and market breakdown procedures were applied, wherever relevant, to complete the market engineering process and derive estimated values for each segment and subsegment. The data was triangulated by assessing key factors and trends across both demand-side and supply-side perspectives. In addition, the market estimates were cross-validated using top-down and bottom-up approaches, company revenues, aircraft production and deliveries, electrical system content per aircraft, supplier contracts, product pricing, aircraft order backlog, military procurement programs, installed fleet, retrofit activity, and country-level aviation demand.
Market Definition
The more electric aircraft market includes electrical systems, subsystems, and associated components used to replace, reduce, or optimize conventionally hydraulic, pneumatic, and mechanically powered secondary aircraft functions. The market includes electrical power generation, power conversion, power distribution and management, electrically driven actuation, electrical environmental control, electric engine starting, electric braking, electrically driven pumps, electric ice protection, electrical wiring and interconnect systems, energy storage and emergency power, and associated thermal and electrical power management equipment integrated into fixed-wing aircraft and rotorcraft. The market primarily covers non-propulsive aircraft electrification.
Key Stakeholders
- Commercial Aircraft OEMs
- Military Aircraft and Rotorcraft OEMs
- Business and General Aviation Aircraft Manufacturers
- Aircraft Electrical Power Generation System Manufacturers
- Power Conversion and Power Electronics Manufacturers
- Electrical Power Distribution and Management System Suppliers
- Electromechanical and Electro-hydrostatic Actuation System Manufacturers
- Electric Motor and Motor Controller Suppliers
- Environmental Control System Manufacturers
- Aircraft Braking and Landing System Suppliers
- Aircraft Pump and Utility Actuation Suppliers
- Energy Storage and Battery System Manufacturers
- Electrical Wiring, Connector, and EWIS Suppliers
- Airlines and Aircraft Operators
- Defense Ministries, Air Forces, and Government Procurement Agencies
- MRO, Retrofit, and Aircraft Upgrade Providers
- Aircraft Leasing Companies
- Regulatory and Civil Aviation Authorities
- Aerospace Research Organizations and Technology Developers
Report Objectives
- To define, describe, and forecast the more electric aircraft market based on platform, system, component, application, end user, and region in terms of value
- To forecast the size of various segments of the market across North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America in terms of value
- To identify and analyze drivers, restraints, opportunities, and challenges influencing the growth of the market
- To identify industry trends, market trends, procurement trends, and technology trends currently prevailing in the market
- To provide an overview of the regulatory and airspace landscape relevant to more electric aircraft deployment across regions
- To analyze micro markets with respect to individual growth trends, prospects, and their contribution to the overall market
- To analyze opportunities in the market for stakeholders by identifying key market trends
- To profile key market players and comprehensively analyze their market shares and core competencies
- To evaluate the degree of competition in the market by analyzing recent developments, such as contracts, agreements, partnerships, product launches, integrations, investments, and acquisitions
- To identify the financial position, key products, aircraft programs, technology capabilities, and unique selling points of leading companies in the market
- To provide a detailed competitive landscape of the market, along with market share analysis and revenue analysis of key players
Available customizations:
MarketsandMarkets offers the following customizations for this market report:
- Additional country-level analysis of the more electric aircraft market
- Profiling of other market players (up to 10)
Product Analysis
- Product matrix, which provides a detailed comparison of the product portfolios of each company in the more electric aircraft market
Get the Full More Electric Aircraft Market Report
Full forecast, segment splits, and company analysis for all More Electric Aircraft Market.
- Canada More Electric Aircraft Market
- US More Electric Aircraft Market
- UK More Electric Aircraft Market
- France More Electric Aircraft Market
- Germany More Electric Aircraft Market
- Russia More Electric Aircraft Market
- Italy More Electric Aircraft Market
- India More Electric Aircraft Market
- Japan More Electric Aircraft Market
- South Korea More Electric Aircraft Market
- Australia More Electric Aircraft Market
- Brazil More Electric Aircraft Market
- Mexico More Electric Aircraft Market
- UAE More Electric Aircraft Market
- Saudi Arabia More Electric Aircraft Market
- Israel More Electric Aircraft Market
- South Africa More Electric Aircraft Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report