Spain Self-driving Cars Market (2024-2029)
The Spain Self-driving Cars Market was valued at $478 Million in 2024 and projected to reach to $409 Million by 2029, representing a compound annual growth rate of -5.9%. Spain's self-driving cars market faces significant headwinds through 2029, with declining valuations reflecting broader European adoption challenges.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Spain Self-driving Cars Market Trends and Insights
- This downturn in Spain reflects broader challenges in autonomous vehicle adoption, including regulatory uncertainty, infrastructure limitations, and consumer hesitancy across the European market.
- Spain's automotive sector faces headwinds as the transition to fully autonomous technologies encounters delays in deployment timelines and investment commitments. The forecast period through 2029 indicates Spain will continue to struggle with self-driving car market development, with declining valuations suggesting reduced commercial viability and slower-than-expected technology rollouts.
- Spain's position within Europe's autonomous vehicle landscape remains constrained by factors including limited testing corridors, fragmented regulatory frameworks, and competition from more advanced markets.
- Market participants in Spain must navigate these structural challenges while preparing for potential recovery phases as technology maturation and regulatory clarity eventually emerge..
Key Market Statistics
- CAGR (2024-2029) -5.9%
- Market Size, 2024 ~USD 478 Million
- Forecast, 2029 ~USD 409 Million
- Country Spain
Spain Self-driving Cars Market Overview
Market Contraction :
Spain's self-driving cars market is declining at -5.9% CAGR, contracting from $478.0 million in 2024 to $409.0 million by 2029, significantly underperforming the global growth rate of 6.8%.
Regulatory Headwinds :
Spain faces stringent EU regulatory frameworks and fragmented national policies that slow autonomous vehicle deployment, creating uncertainty for manufacturers and technology providers entering the Spanish market.
Infrastructure Gaps :
Limited digital infrastructure, inconsistent road connectivity standards, and inadequate 5G coverage across Spain hinder the deployment of fully autonomous vehicle systems required for market growth.
Consumer Adoption Barriers :
Spanish consumers demonstrate low confidence in autonomous technology due to safety concerns, limited real-world testing visibility, and preference for traditional driving, dampening market demand and investment.
Spain Self-driving Cars Market Dynamics
- Regulatory uncertainty, combined with infrastructure limitations and consumer hesitancy, creates a challenging environment for autonomous vehicle deployment.
- However, potential EU regulatory harmonization and increased investment in digital infrastructure could provide recovery opportunities beyond 2029. Market participants must navigate Spain's complex regulatory landscape while building consumer trust through pilot programs and transparent safety data.
- Strategic partnerships with local stakeholders and alignment with EU-wide autonomous vehicle initiatives will be critical for companies seeking to stabilize market position and capitalize on long-term growth potential as technology maturity and regulatory clarity improve..
Market Ecosystem
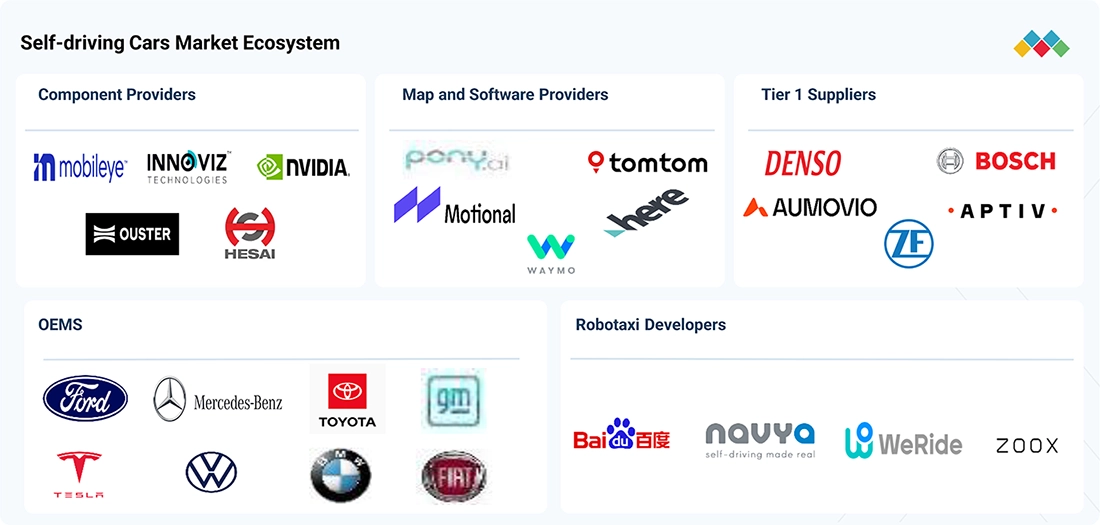
SELF-DRIVING CARS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Integration of Level 2 and Level 3 advanced driver assistance and automated driving technologies across passenger vehicles, supported by sensor fusion, automated control systems, and software-based vehicle functions. | Improves driving safety and convenience, reduces driver workload, and supports the gradual adoption of automated driving features. Software and system integration capabilities can also enable future upgrades across vehicle platforms. |
 |
Deployment of advanced driver assistance systems, including adaptive cruise control, lane-keeping assistance, automated parking, and highway driving assistance, across selected vehicle models. | Enhances driver assistance, improves comfort in highway and congested traffic conditions, and supports the standardization of software-enabled driving functions across vehicle platforms. |
 |
Integration of intelligent driving assistance, sensor-based perception, and automated parking functions into electric passenger vehicles, supported by vehicle electronics and software integration. | Improves driving convenience, strengthens safety assistance, and expands access to intelligent driving features across electric vehicle segments. Greater integration of hardware and software supports scalable feature deployment. |
 |
Implementation of Level 2 advanced driver assistance and selected hands-free driving capabilities, including highway assistance, adaptive cruise control, and lane-centering functions across eligible vehicle models. | Reduces driver workload during long-distance travel, improves driving comfort, and enables differentiated technology offerings across vehicle brands. Software integration supports the expansion of driver assistance capabilities across multiple vehicle platforms. |
 |
Deployment of Highway Driving Assist, adaptive cruise control, lane-following assistance, and remote smart parking functions across selected passenger vehicles, with continued development of higher-level automated driving technologies. | Improves driver convenience and highway safety assistance, simplifies parking in constrained spaces, and supports broader adoption of automated driving technologies across vehicle categories. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Key Takeaways
- Spain's self-driving cars market will contract from $478.0M (2024) to $409.0M (2029) at a -5.9% CAGR, indicating significant market headwinds.
- Regulatory fragmentation and infrastructure gaps are limiting autonomous vehicle deployment across Spain.
- Spain faces competitive disadvantages compared to leading European autonomous vehicle markets with more mature ecosystems.
- Market recovery in Spain depends on regulatory harmonization, technology standardization, and increased investment in testing infrastructure.
Self-driving Cars Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | L5 (Level Of Autonomy) |
| Forecast Period | 2024-2029 |
| Growth Rate | CAGR of 6.8% from 2024 to 2029 |
| Largest Segment | PERSONAL MOBILITY (Mobility Type) |
| Segments Covered | Level Of Autonomy, Component, Mobility Type, Vehicle Class |
Spain Self-driving Cars Market Report Segmentation
4 segment dimensions are covered across the global market.
By Level Of Autonomy
- L1
- L2
- L3
- L4
- L5
By Component
- Camera
- Lidar
- Radar
- Ultrasonic Sensor
By Mobility Type
- Personal Mobility
- Shared Mobility
By Vehicle Class
- A&B
- C&D
- E&F
Target Audience
- Automotive OEMs : Manufacturers need Spain-specific market data to assess viability of autonomous vehicle launches, optimize R&D investment, and determine go-to-market timing in a declining market.
- Technology & Software Providers : AV tech companies require detailed Spain market analysis to identify partnership opportunities, evaluate customer demand, and strategize localization efforts amid regulatory complexity.
- Investment & Private Equity Firms : Investors need comprehensive Spain market forecasts and risk analysis to evaluate portfolio opportunities, assess exit strategies, and make informed funding decisions in autonomous vehicle ventures.
- Government & Policy Makers : Spanish regulatory bodies and transport ministries require market intelligence to develop supportive policies, infrastructure investments, and incentive programs to reverse market contraction.
- Mobility & Fleet Operators : Fleet management companies need Spain market insights to evaluate autonomous vehicle adoption timelines, assess ROI potential, and plan fleet modernization strategies for the Spanish market.
Reasons to Buy this Report
- Identify Market Decline Drivers : Understand the specific regulatory, infrastructure, and consumer factors causing Spain's -5.9% CAGR contraction to inform strategic market entry or exit decisions.
- Competitive Positioning Strategy : Analyze Spain's underperformance versus global 6.8% growth to identify competitive gaps and opportunities for differentiation in a contracting market segment.
- Risk Assessment & Mitigation : Evaluate regulatory uncertainty, infrastructure limitations, and adoption barriers specific to Spain to develop robust risk management and contingency planning frameworks.
- Investment Decision Support : Access detailed market sizing and forecasts for Spain to justify capital allocation decisions, partnership strategies, and resource prioritization in the autonomous vehicle sector.
- Regulatory & Policy Insights : Gain clarity on Spain's fragmented regulatory environment and EU compliance requirements to navigate market entry, licensing, and operational compliance effectively.
Frequently asked questions
What is the current size of Spain's self-driving cars market?
Spain's self-driving cars market was valued at $478.0 million in 2024, according to verified market data.
What is the forecast for Spain's self-driving cars market by 2029?
Spain's self-driving cars market is projected to reach $409.0 million by 2029, representing a decline from 2024 levels.
Why is Spain's self-driving cars market declining?
Spain's market contraction is driven by regulatory uncertainty, limited testing infrastructure, slower technology adoption rates, and competition from more advanced European markets.
What is the CAGR for Spain's self-driving cars market?
Spain's self-driving cars market has a negative CAGR of -5.9% from 2024 to 2029.
How does Spain's market compare to the global self-driving cars market?
While the global self-driving cars market grows at 6.8% CAGR, Spain experiences a -5.9% decline, indicating the country lags significantly behind global trends.
RESEARCH METHODOLOGY
The research study used extensive secondary sources, such as company annual reports/presentations, industry association publications, magazine articles, directories, technical handbooks, World Economic Outlook, trade websites, technical articles, and databases, to identify and collect information on the self-driving cars market. Primary sources, including experts from related industries, OEMs, and suppliers, were interviewed to obtain and verify critical information and assess growth prospects and market estimates.
Secondary Research
Secondary sources for this research study included corporate filings, such as annual reports, investor presentations, and financial statements; trade, business, and professional associations; whitepapers and self-driving car and ADAS-related journals; certified publications; articles by recognized authors; directories; and databases. Secondary data was collected and analyzed to determine the overall market size, further validated by primary research.
Primary Research
After understanding the self-driving cars market scenario through secondary research, extensive primary research was conducted. Primary interviews were conducted with market experts from both demand and supply sides across North America, Europe, and Asia Pacific. Approximately 35% of interviews were conducted from the demand side, while 65% of primary interviews were conducted from the supply side. Primary data were collected through questionnaires, emails, and telephone interviews.
In the canvassing of primary data, various departments within organizations, such as sales and operations, were covered to provide a holistic viewpoint in this report. Primary sources from the supply side included various industry experts, such as CXOs, vice presidents, directors from business development, marketing, product development/innovation teams, and related key executives from various key companies. Various system integrators, industry associations, independent consultants’/industry veterans, and key opinion leaders were also interviewed.
Breakdown of Primary Interviews
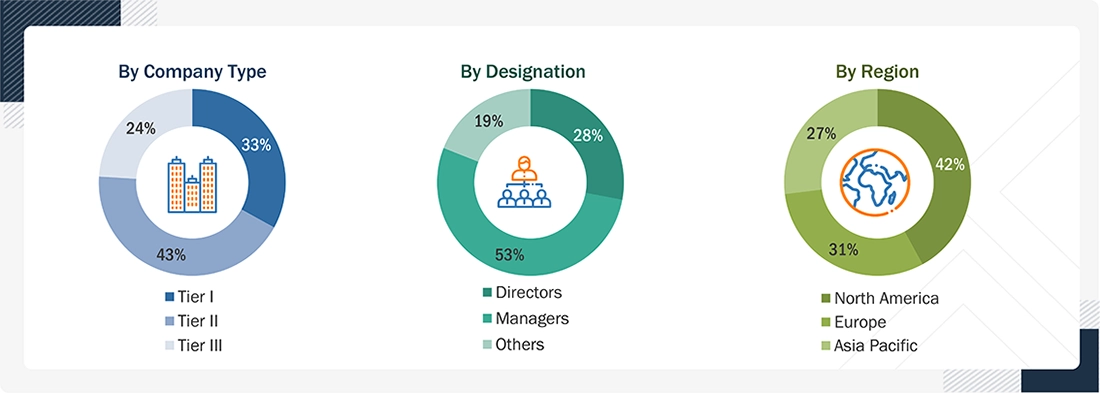
Note: Others include purchase and sales managers, marketing managers, and product managers.
Company tiers are based on the value chain; the company's revenue is not considered.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
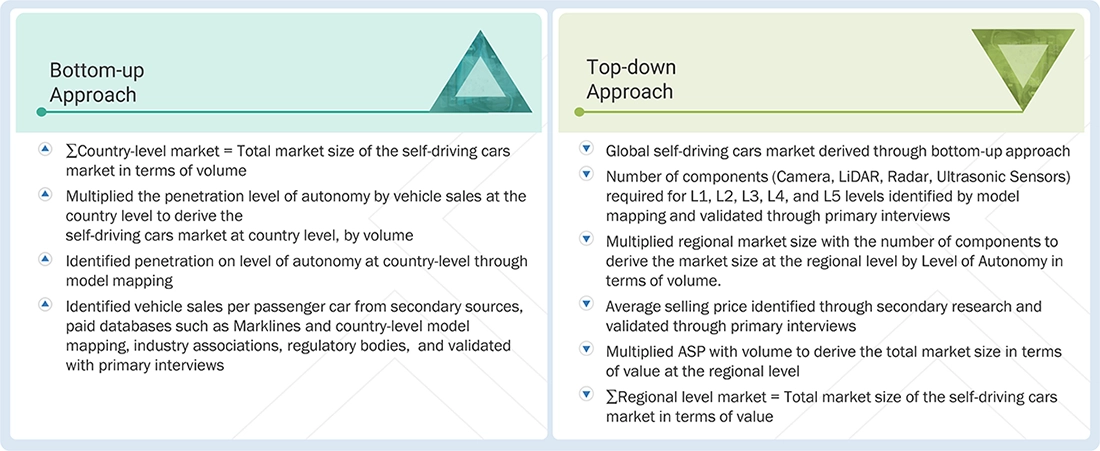
Bottom-up approach
The bottom-up approach was used to estimate and validate the size of the self-driving cars market. In this approach, vehicle sales statistics for each vehicle class were considered at the country and regional levels. The penetration of the level of autonomy for each passenger car at the country level was identified through model mapping to determine the market size of self-driving cars in terms of volume. Then, the penetration of each level of autonomy in passenger cars for all countries was applied to obtain the volume of the self-driving cars market.
Extensive secondary and primary research was conducted to understand the global market scenario for ADAS features with respect to the level of autonomy used in the automotive industry. Several primary interviews were conducted with key opinion leaders related to self-driving car development, including OEMs, Tier 1 suppliers, and applications. Qualitative aspects such as drivers, restraints, opportunities, and challenges were considered while calculating and forecasting the market size.
Top-down approach
The top-down approach was used to determine the size of the self-driving cars market for the component segment. Although the total market size in value (USD million) was derived using the bottom-up approach, the component segment was derived using the top-down approach. For instance, the self-driving cars market for the component segment was derived using the top-down approach to estimate the subsegments. Mapping was done at the regional level to understand the contribution by component. The market size was derived at the regional level in terms of value. The total value of the self-driving cars market was multiplied by the cost breakdown percentage of each component at the regional level.
Self-Driving Cars Market: Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size of the global market through the methodology mentioned above, this market was split into several segments and subsegments. The data triangulation and market breakdown procedures were employed to complete the overall market engineering process and arrive at the exact market value data for the key segments and sub-segments, wherever applicable. The extrapolated market data was triangulated by studying various macro indicators and regional trends from both the demand and supply-side participants.
Market Definition
Self-driving cars are technologies capable of performing dynamic driving tasks, with or without human supervision. The California DMV defines autonomous mode as when the technology manages driving operations independently. At the same time, SAE Level 5 autonomy represents vehicles capable of moving under all conditions without human intervention, even with a user in the driver's seat.
Key Stakeholders
- ADAS Integrators
- ADAS Solution Suppliers
- Associations, Forums, and Alliances related to Autonomous Vehicles
- Automotive Component Manufacturers
- Automotive Industry Associations, Government Authorities, and Research Organizations
- Automotive OEMs
- Automotive Sensor Manufacturers
- Automotive SoC and ECU Manufacturers
- Automotive Software and Platform Providers
- Autonomous Driving Platform Providers
- Autonomous Vehicle Manufacturers
- Country-specific Automotive Associations
- European Automobile Manufacturers Association (ACEA)
- Government and Research Organizations
- National Highway Traffic Safety Administration (NHTSA)
- Transport Authorities
- Vehicle Safety Regulatory Bodies
Report Objectives
- To analyze and forecast the self-driving cars market in terms of volume (thousand units) and value (USD million) from 2026 to 2035
-
To segment the market by level of autonomy, component type, mobility type, vehicle class, region, EV type, and autonomous driving system
- To segment and forecast the market by level of autonomy (semi-autonomous (L1, L2, and L3), and autonomous (L4 and L5))
- To segment and forecast the market by component type (camera, LiDAR, radar, ultrasonic sensors, infrared sensors, GNSS & IMU, SOC, and others)
- To segment and forecast the market by mobility type (personal mobility and shared mobility)
- To segment and forecast the market by vehicle class (A&B, C&D, and E&F)
- To forecast the market by region [North America, Europe, and Asia Pacific]
- To segment and forecast the market by autonomous driving system (perception & sensing, compute & AI, localization & mapping, planning & decision making, vehicle control, safety & redundancy)
- To segment and forecast the market by EV type (BEV, PHEV, and FCEV)
- To identify and analyze key drivers, challenges, restraints, and opportunities influencing market growth
- To strategically analyze the market for individual growth trends, prospects, and contributions to the total market
-
To study the following with respect to the market
- Pricing Analysis
- Investment and Funding Scenario
- Value Chain Analysis
- Ecosystem Analysis
- Technology Analysis
- Trade Analysis
- Case Study Analysis
- Patent Analysis
- Regulatory Landscape
- Key Stakeholders and Buying Criteria
- Key Conferences and Events
- To strategically profile the key players and comprehensively analyze their market share and core competencies
- To analyze the impact of AI on the market
- To track and analyze competitive developments such as deals, product launches/developments, expansions, and other activities undertaken by the key industry participants
Available customizations:
Along with the market data, MarketsandMarkets offers customizations in accordance with a company’s specific needs.
- self-driving cars Market, by Level of Autonomy, at country level
- self-driving cars Market, by EV type, at country level
Company Information
-
Profiling of additional market players (up to five)
Get the Full Self-driving Cars Market Report
Full forecast, segment splits, and company analysis for all Self-driving Cars Market.
- China Self-driving Cars Market
- India Self-driving Cars Market
- Japan Self-driving Cars Market
- South Korea Self-driving Cars Market
- Germany Self-driving Cars Market
- France Self-driving Cars Market
- Italy Self-driving Cars Market
- UK Self-driving Cars Market
- Canada Self-driving Cars Market
- US Self-driving Cars Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report