Canada Sugar Substitutes Market (2024-2029)
The Canada Sugar Substitutes Market was valued at $1435.3 Million in 2024 and projected to reach to $1814.4 Million by 2029, representing a compound annual growth rate of 4.8%. Canada's sugar substitutes market is positioned for consistent growth through 2029, driven by increasing health consciousness among consumers and government initiatives promoting reduced sugar consumption.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Canada Sugar Substitutes Market Trends and Insights
- This 4.8% compound annual growth rate reflects Canada's increasing consumer demand for healthier food and beverage alternatives driven by rising obesity awareness and diabetes prevalence.
- Canada's regulatory environment and strong retail infrastructure support the adoption of artificial and natural sweeteners across multiple product categories. The Canadian market benefits from a health-conscious population and stringent food safety standards that encourage innovation in sugar substitute formulations.
- Canada's beverage and confectionery sectors are primary drivers, with manufacturers reformulating products to meet consumer preferences for reduced-sugar options.
- By 2029, Canada is expected to solidify its position as a key market for sugar substitutes in North America, with continued investment in R&D and product diversification..
Key Market Statistics
- CAGR (2024-2029) 4.8% CAGR
- Market Size, 2024 ~USD 1435.3 Million
- Forecast, 2029 ~USD 1814.4 Million
- Country Canada
Canada Sugar Substitutes Market Overview
Market Valuation :
Canada's sugar substitutes market is valued at $1,435.3 million in 2024, with projected growth to $1,814.4 million by 2029, representing a steady 4.8% CAGR.
Health-Driven Demand :
Rising obesity rates and diabetes prevalence across Canada are driving consumer preference for healthier food and beverage alternatives, fueling market expansion.
Regulatory Advantage :
Canada's supportive regulatory environment and clear labeling requirements create favorable conditions for sugar substitute manufacturers and product innovation.
Retail Infrastructure :
Strong retail distribution networks across Canada, including major grocery chains and e-commerce platforms, enable widespread accessibility of sugar substitute products.
Canada Sugar Substitutes Market Dynamics
- The market benefits from Canada's mature retail infrastructure and strong e-commerce adoption, enabling manufacturers to reach diverse consumer segments across urban and rural areas.
- Product innovation in natural and plant-based sweeteners is gaining traction as consumers seek cleaner label alternatives.
- The 4.8% CAGR reflects a balanced market with established players and emerging brands competing for share in the premium and mainstream segments..
Market Ecosystem
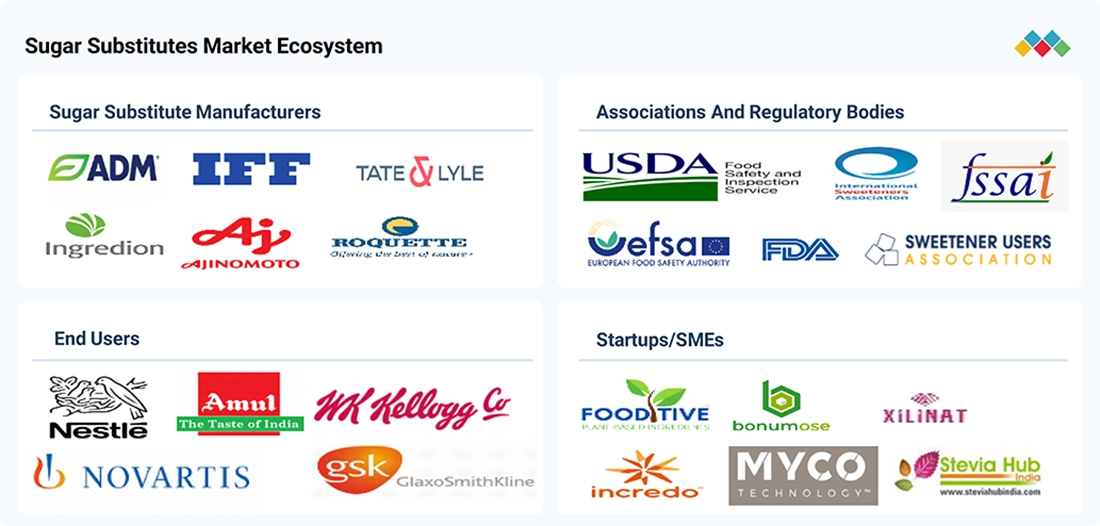
SUGAR SUBSTITUTES MARKET TRENDS, GROWTH, AND FORECAST [LATEST]: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
IFF applies taste-modulation technologies and flavor expertise to help manufacturers reduce sugar while maintaining desirable sweetness, flavor balance, and overall sensory quality in food and beverage products. | Helps minimize taste trade-offs associated with sugar reduction, improves consumer acceptance, and supports the development of differentiated reduced-sugar formulations. |
 |
ADM offers sweetening solutions that include stevia, monk fruit, and other sweetener systems. These ingredients can be incorporated into beverages, dairy, snacks, and other food products to support sugar reduction and calorie management. | Enables manufacturers to reformulate products for reduced-sugar and low-calorie positioning, diversify sweetener options, and address changing consumer preferences. |
 |
Ingredion provides sugar-reduction solutions through its stevia-based sweeteners, including PURECIRCLE ingredients, alongside specialty sweeteners and formulation expertise. These solutions serve beverages, dairy, confectionery, and other food applications. | Supports sugar reduction, helps improve sweetness and formulation performance, and enables manufacturers to develop products that meet clean-label and reduced-calorie requirements. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Fandb Additives
- Dairy Products
- Bakery Products
- Polyglycerol Esters
- Microorganism
- Carbohydrates
- AZELIS HOLDINGS SA
- Archer-Daniels-Midland Company
- Amway
- UNILEVER PLC
- DuPont de Nemours, Inc.
Fandb Ingredients
- Dairy Products
- Bakery Products
- Microorganism
- Polydextrose
- Carbohydrates
- AZELIS HOLDINGS SA
- Archer-Daniels-Midland Company
- Kerry Group plc
- Amway
- DSM FIRMMENICH
Key Takeaways
- Canada's sugar substitutes market is valued at $1,435.3 million in 2024 and will reach $1,814.4 million by 2029, growing at a 4.8% CAGR.
- Health-conscious Canadian consumers and rising diabetes awareness are primary drivers of sugar substitute adoption across beverages and confectionery products.
- Canada's stringent food safety regulations and strong retail infrastructure create favorable conditions for innovation in natural and artificial sweetener formulations.
- The Canadian market is positioned as a key growth region in North America, with sustained demand for reduced-sugar product reformulations through 2029.
Sugar Substitutes Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | STEVIA (Subtype) |
| Forecast Period | 2024-2029 |
| Growth Rate | CAGR of 4.9% from 2024 to 2029 |
| Largest Segment | DRY (Form) |
| Market Size Base Year (Billions) | ~USD 23.54 (2024) |
| Revenue Forecast (Billions) | ~USD 29.9 (2029) |
| Segments Covered | Type, Subtype, Application, Subapplication, Form, Source |
Canada Sugar Substitutes Market Report Segmentation
6 segment dimensions are covered across the global market.
By Type
- High-Fructose Corn Syrup
- High-Intensity Sweeteners
- Low-Intensity Sweeteners
By Subtype
- Ace-K
- Allulose
- Aspartame
- Cyclamate
- D-Tagatose
- Erythritol
- Gels
- Granules
- Maltitol
- Mannitol
- Monk Fruit Extracts
- Other Artificial High-Intensity Sweeteners
- Other Dry Forms
- Other Low-Intensity Sweeteners
- Other Natural High-Intensity Sweeteners
- Powder
- Saccharin
- Sorbitol
- Stevia
- Sucralose
- Syrups
- Xylitol
By Application
- Beverages
- Food
- Food Products
- Health & Personal Care Products
- Other Applications
- Pharmaceuticals
By Subapplication
- Alcoholic Beverages
- Bakery Products
- Carbonated Drinks
- Confectionery Products
- Dairy Products
- Flavored Alcoholic Beverages
- Fruit Drinks & Juices
- Other Beverage Applications
- Other Beverages
- Other Food Applications
- Plant-Based Beverages
- Powdered Drinks
- Sweet Spreads
- Tabletop Sweeteners
By Form
- Crystals
- Dry
- Liquid
- Powder
By Source
- Artificial
- Natural
CANADA: SUGAR SUBSTITUTES MARKET, BY APPLICATION, 2024–2029
| Segment | 2024 | 2025 | 2026 | 2027 | 2028 | 2029 | CAGR (%) |
|---|---|---|---|---|---|---|---|
| BEVERAGES | 618.6 | 649 | 682.1 | 718.3 | 757.8 | 800.9 | 5.3 |
| FOOD | 544.1 | 566.4 | 590.8 | 617.3 | 646.4 | 678 | 4.5 |
| HEALTH & PERSONAL CARE PRODUCTS | 225.3 | 234.1 | 243.6 | 254.1 | 265.6 | 278 | 4.3 |
| OTHER APPLICATIONS | 5.5 | 5.6 | 5.8 | 6 | 6.2 | 6.4 | 3.4 |
| PHARMACEUTICALS | 41.9 | 43.4 | 45 | 46.8 | 48.8 | 50.9 | 4 |
| TOTAL | 1435.3 | 1498.4 | 1567.3 | 1642.6 | 1724.7 | 1814.4 | 4.8 |
Target Audience
- Food & Beverage Manufacturers : Manufacturers need Canada-specific market data to develop product formulations, pricing strategies, and distribution plans aligned with local consumer preferences and regulatory requirements.
- Retail & Distribution Companies : Retailers require detailed market insights to optimize shelf space allocation, negotiate supplier contracts, and identify high-growth product categories within Canada's sugar substitutes segment.
- Investment & Private Equity Firms : Investors need comprehensive Canada market analysis to evaluate acquisition targets, assess growth potential, and make informed capital allocation decisions in the food additives sector.
- Marketing & Brand Strategy Teams : Marketing professionals require Canada market intelligence to develop targeted campaigns, understand consumer messaging preferences, and position brands effectively against competitors.
- Government & Policy Makers : Policymakers need market data to inform health initiatives, evaluate regulatory frameworks, and understand the economic impact of sugar reduction policies on Canada's food industry.
Reasons to Buy this Report
- Canada-Specific Market Sizing : Access precise valuation data for Canada's sugar substitutes market with verified 2024 baseline ($1.44B) and 2029 forecasts, enabling accurate business planning and investment decisions.
- Competitive Landscape Intelligence : Understand market dynamics specific to Canada's regulatory environment, retail structure, and consumer preferences to identify competitive advantages and market entry opportunities.
- Growth Trajectory Analysis : Leverage Canada's 4.8% CAGR data to benchmark performance, forecast revenue potential, and allocate resources effectively across product categories and distribution channels.
- Consumer Trend Insights : Gain actionable insights into Canadian consumer health consciousness, obesity awareness, and diabetes prevalence driving demand for sugar substitutes in key demographic segments.
- Strategic Expansion Planning : Use Canada market data to develop go-to-market strategies, identify high-potential regions, and optimize product portfolios for the Canadian food and beverage sector.
Frequently asked questions
What is the current size of Canada's sugar substitutes market?
Canada's sugar substitutes market was valued at $1,435.3 million in 2024 and is projected to grow to $1,814.4 million by 2029.
What is the growth rate of Canada's sugar substitutes market?
Canada's sugar substitutes market is growing at a compound annual growth rate (CAGR) of 4.8% from 2024 to 2029.
What are the main drivers of growth in Canada's sugar substitutes market?
Key drivers include rising health consciousness among Canadian consumers, increasing diabetes prevalence, demand for reduced-sugar beverages and confectionery, and stringent food safety regulations that encourage product reformulation.
Which product categories dominate Canada's sugar substitutes market?
Beverages and confectionery products are the primary categories driving Canada's sugar substitutes market, with manufacturers reformulating to meet consumer preferences for healthier alternatives.
How does Canada's regulatory environment impact the sugar substitutes market?
Canada's stringent food safety standards and clear labeling requirements create a favorable environment for innovation and consumer trust in sugar substitute products, supporting market expansion.
RESEARCH METHODOLOGY
This study involved two major approaches in estimating the current size of the sugar substitutes market. Exhaustive secondary research was conducted to collect information on the market, peer, and parent markets. The next step involved validating these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. After that, market breakdown and data triangulation were used to estimate the market size of segments and subsegments.
Secondary Research
This research study involved the extensive use of secondary sources—directories and databases such as Bloomberg Businessweek and Factiva—to identify and collect information useful for a technical, market-oriented, and commercial study of the market.
In the secondary research process, various sources such as annual reports, press releases & investor presentations of companies, white papers, food journals, certified publications, articles from recognized authors, directories, and databases were referred to to identify and collect information.
Secondary research was mainly used to obtain key information about the industry’s supply chain, the total pool of key players, and market classification and segmentation as per the industry trends to the bottom-most level, regional markets, and key developments from both market- and technology-oriented perspectives.
Primary Research
Extensive primary research was conducted after obtaining information regarding the sugar substitutes market scenario through secondary research. Several primary interviews were conducted with market experts from both the demand and supply sides across major countries of North America, Europe, Asia Pacific, South America, and the Rest of the World. Primary data were collected through questionnaires, emails, and telephonic interviews. The primary sources from the supply side included various industry experts, such as Chief Experience Officers (CXOs), Vice Presidents (VPs), Directors from business development, marketing, research, and development teams, and related key executives from distributors and key opinion leaders. Primary interviews were conducted to gather insights such as market statistics, data on revenue collected from the products and services, market breakdowns, market size estimations, market forecasting, and data triangulation. Primary research also helped in understanding the various trends related to sugar substitutes by type, manufacturing technology, application, form, source, and region. Stakeholders from the demand side, such as food and beverage companies and health and personal care companies that use sugar substitutes, were interviewed to understand the buyer’s perspective on the suppliers, products, and their current usage of sugar substitutes and the outlook of their business, which will affect the overall market.
Following is the breakup of the primary study:
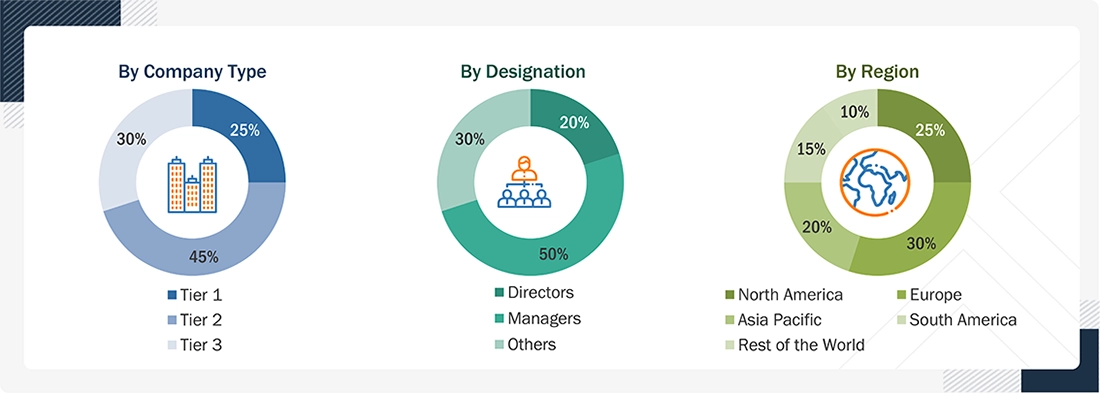
Note: The three tiers of the companies are defined based on their total revenues in 2024 or 2025, based on the availability of financial data: Tier 1: Revenue >USD 1 billion; Tier 2: USD 100 million ≤ revenue ≤ USD 1 billion; Tier 3: Revenue USD 100 million.
To know about the assumptions considered for the study, download the pdf brochure
|
COMPANY |
DESIGNATION |
|
Cargill, Incorporated (US) |
General Manager |
|
ADM (US) |
Sales Manager |
|
Ingredion (US) |
Manager |
|
International Flavors & Fragrances Inc. (US) |
Head of Processing Department |
|
Tate & Lyle (UK) |
Marketing Manager |
|
Ajinomoto Co. Inc. (Japan) |
Sales Executive |
Market Size Estimation
- Both the top-down and bottom-up approaches were used to estimate and validate the total size of the sugar substitutes market. These approaches were also used extensively to determine the size of various subsegments in the market. The research methodology used to estimate the market size includes the following details:
- The key players in the industry and the overall market were identified through extensive secondary research.
- All shares, splits, and breakdowns were determined using secondary sources and verified through primary sources.
- All possible parameters that affect the market covered in this research study were accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain final quantitative and qualitative data.
- The research included the study of reports, reviews, and newsletters of top market players, along with extensive interviews for opinions from leaders, such as CEOs, directors, and marketing executives.
Sugar Substitutes Market : Top-Down and Bottom-Up Approach
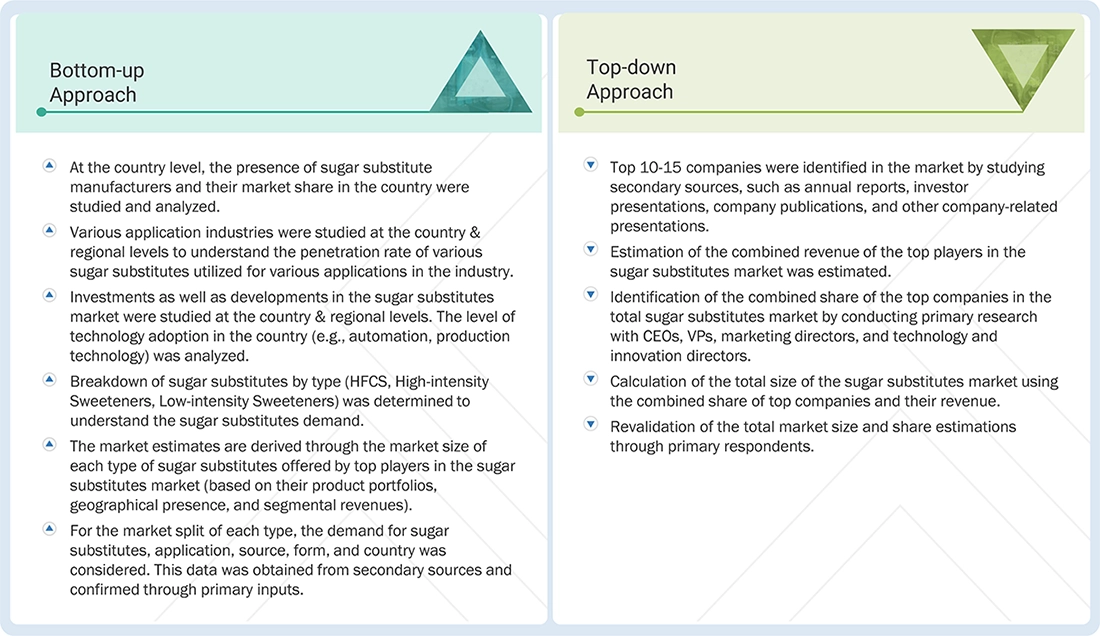
Source: MarketsandMarkets Analysis
Data Triangulation
After arriving at the overall market size from the estimation process explained above, the total market was split into several segments and subsegments. The data triangulation and market breakdown procedures were employed, wherever applicable, to estimate the overall sugar substitutes market and arrive at the exact statistics for all segments and subsegments. The data were triangulated by studying various factors and trends from the demand and supply sides. The market size was also validated using both the top-down and bottom-up approaches.
Market Definition
As defined by the FDA, “Sugar substitutes refer to substances that have little to no calories or other nutrients.” Sugar substitutes are substances used instead of sweeteners with sugar or sugar alcohol. They may also be called artificial sweeteners, non-nutritive sweeteners (NNS), and non-caloric sweeteners. Sugar substitutes can be defined as a food additive that duplicates the effect of sugar in taste, but usually with less food energy.
Key Stakeholders
- Raw material suppliers
-
Regulatory bodies, which include the following:
- Food and Drug Administration (FDA)
- European Food Safety Authority (EFSA)
- US Department of Agriculture (USDA)
- Food Standards Australia New Zealand (FSANZ)
- Health Canada – Food Directorate
- China National Center for Food Safety Risk Assessment (CFSA)
- World Health Organization (WHO)
- Government agencies and NGOs
-
End users, which include the following:
- Food & beverage manufacturers/suppliers
- Health & personal care product manufacturers/suppliers
- Retailers
- Commercial Research & Development (R&D) institutions and financial institutions
- Importers and exporters of sugar substitutes
- Traders, distributors, and suppliers
- Research organizations
- Trade associations and industry bodies
Report Objectives
- To determine and project the size of the sugar substitutes market with respect to the type, manufacturing technology, application, form, source, and region in terms of value over five years, ranging from 2026 to 2031
- To identify the attractive opportunities in the market by determining the largest and fastest-growing segments across regions
- To provide detailed information about the key factors influencing market growth (drivers, restraints, opportunities, and challenges)
- To analyze the opportunities in the market for stakeholders and provide details of the competitive landscape for market leaders
- To analyze the micro-markets with respect to individual growth trends, prospects, and their contribution to the total market
- To identify and profile the key players in the market
- To understand the competitive landscape and identify the major growth strategies adopted by players across the key regions
Customization Options
With the given market data, MarketsandMarkets offers customizations according to company-specific scientific needs.
The following customization options are available for the report:
Product Analysis
- Product Matrix, which gives a detailed comparison of the product portfolio of each company.
Geographic Analysis
With the given market data, MarketsandMarkets offers customizations according to company-specific scientific needs.
- Further breakdown of the Rest of Europe sugar substitutes market into key countries.
- Further breakdown of the Rest of Asia Pacific sugar substitutes market into key countries.
- Further breakdown of the Rest of South America sugar substitutes market into key countries.
Company Information
Detailed analyses and profiling of additional market players (up to five)
Get the Full Sugar Substitutes Market Report
Full forecast, segment splits, and company analysis for all Sugar Substitutes Market.
- US Sugar Substitutes Market
- Mexico Sugar Substitutes Market
- Germany Sugar Substitutes Market
- UK Sugar Substitutes Market
- France Sugar Substitutes Market
- Italy Sugar Substitutes Market
- Spain Sugar Substitutes Market
- China Sugar Substitutes Market
- India Sugar Substitutes Market
- Japan Sugar Substitutes Market
- Brazil Sugar Substitutes Market
- Argentina Sugar Substitutes Market
- Rest Of Europe Sugar Substitutes Market
- Rest Of Asia Pacific Sugar Substitutes Market
- Rest Of South America Sugar Substitutes Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report