Latin America Urology Devices Market (2025-2030)

The Latin America Urology Devices Market was valued at $1847.6 Million in 2025 and projected to reach to $2183.6 Million by 2030, representing a compound annual growth rate of CAGR 3.4%. The Latin America urology devices market is positioned for moderate but consistent growth through 2030, supported by increasing prevalence of urological disorders, expanding geriatric populations, and improving healthcare infrastructure across the region.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Latin America Urology Devices Market Trends and Insights
- Latin America's urology devices sector is driven by increasing prevalence of urological conditions, aging populations, and rising healthcare expenditure across the region.
- In Latin America, expanding access to advanced diagnostic and therapeutic technologies, coupled with improving reimbursement frameworks, is supporting steady market expansion through 2030. Latin America's urology devices market reflects moderate but consistent growth compared to global trends, with regional variations in adoption rates and healthcare infrastructure maturity.
- Key markets within Latin America, including Brazil and Mexico, are experiencing incremental demand for minimally invasive urological procedures and diagnostic equipment.
- Latin America's market trajectory through 2030 is underpinned by demographic shifts, increased awareness of urological health, and gradual modernization of healthcare facilities across the region..
Key Market Statistics
- CAGR (2025-2030) CAGR 3.4%
- Market Size, 2025 ~USD 1847.6 Million
- Forecast, 2030 ~USD 2183.6 Million
- Geography Latin America
Latin America Urology Devices Market Overview
Regional Market Size & Growth :
Latin America's urology devices market is valued at USD 1,847.6 million in 2025, with projected growth to USD 2,183.6 million by 2030, representing a CAGR of 3.4%, reflecting steady expansion driven by healthcare infrastructure improvements.
Aging Population Dynamics :
Latin America faces a rapidly aging demographic, increasing the prevalence of age-related urological conditions such as benign prostatic hyperplasia, urinary incontinence, and kidney disorders, driving sustained demand for specialized urology devices.
Rising Healthcare Expenditure :
Growing healthcare budgets across Latin American countries, coupled with increased insurance coverage and government health initiatives, are expanding patient access to advanced urological treatments and diagnostic devices.
Brazil & Mexico Market Leadership :
Brazil (USD 2,042.1 million) and Mexico (USD 1,049.3 million) dominate the Latin American urology devices market, accounting for the majority of regional demand and representing key growth opportunities for device manufacturers.
Latin America Urology Devices Market Dynamics
- Brazil and Mexico serve as primary growth engines, with rising healthcare spending and enhanced patient awareness driving adoption of advanced diagnostic and therapeutic devices. Market expansion will be facilitated by growing private healthcare sectors, increasing medical tourism, and government initiatives to improve urological care accessibility.
- However, regional growth remains tempered compared to global markets due to economic constraints, regulatory complexities, and varying healthcare system maturity across Latin American countries.
- Strategic partnerships and localized product offerings will be critical for manufacturers seeking to capture market share..
Market Ecosystem
urology-devices-market: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Provides advanced dialysis systems, urological disposables, and minimally invasive solutions for the treatment of chronic kidney disease and urinary disorders in hospitals, clinics, and dialysis centers worldwide. | Enables reliable kidney disease devices, improves patient outcomes in acute and chronic kidney failure cases, supports safety standards, and optimizes workflow efficiency for healthcare providers and patients. |
 |
Offers a comprehensive portfolio of urology and pelvic health solutions, including stone management devices, endourology systems, BPH therapies, and minimally invasive technologies used in both diagnostic and therapeutic urology procedures. | Enhances precision during diagnosis and treatment, reduces procedure times with innovative tools, improves patient safety and comfort, and supports versatility across a wide range of urological interventions. |
 |
Manufactures catheters, dilators, retrieval baskets, guidewires, and diagnostic solutions utilized throughout the urinary tract for minimally invasive interventions in kidney stones, strictures, and urinary retention, providing critical support for clinicians. | Ensures accurate device placement, lowers risk of complications, supports repeatable outcomes, complies with international safety guidelines, and improves overall throughput in endoscopic and catheter-based urologic procedures. |
 |
Supplies a broad selection of urological catheters, nephrostomy sets, irrigation systems, and surgical urology instruments, with a focus on single-use and sterile solutions to minimize infection risks across both hospital and outpatient environments. | Improves sterility and patient safety, reduces healthcare-acquired infections, meets strict regulatory requirements, simplifies post-procedural care, and enhances workflow in busy hospital and home care settings. |
 |
Specializes in high-definition endoscopy equipment, resectoscopes, laser lithotripsy devices, and visualization systems for urological diagnostics and minimally invasive surgeries, trusted globally in clinical and operating environments. | Delivers clear visualization and precise surgical access, assists in rapid and accurate diagnosis, enables more minimally invasive urologic surgery, lowers recovery times, and sets benchmarks for innovation in urology imaging and care. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Medical Devices
- Polymerase Chain Reaction (PCR)
- Magnetic Resonance Imaging (MRI)
- Disposable Autoinjectors
- Pulse Oximeters
- Blood Pressure Monitors
- Medtronic plc
- Abbott Laboratories
- Stryker Corporation
- Becton, Dickinson and Company
- CONMED Corporation
Key Takeaways
- Latin America's urology devices market is valued at USD 1,847.6 million in 2025 and will reach USD 2,183.6 million by 2030.
- Latin America is experiencing a 3.4% CAGR, reflecting steady but moderate growth driven by aging demographics and improved healthcare access.
- Latin America's market growth is supported by rising prevalence of urological conditions and increasing adoption of minimally invasive procedures.
- Latin America's regional variations in healthcare infrastructure and reimbursement policies influence device adoption rates and market penetration.
Urology Devices Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | URINARY INCONTINENCE (UI) (Application) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 6% from 2025 to 2030 |
| Largest Segment | HOSPITALS (End User) |
| Market Size Base Year (Billions) | ~USD 34.57 (2025) |
| Revenue Forecast (Billions) | ~USD 46.26 (2030) |
| Segments Covered | Product, Type, Application, End User |
Latin America Urology Devices Market Report Segmentation
4 segment dimensions are covered across the global market.
By Product
- Consumables & Accessories
- Instruments
By Type
- Biopsy Devices
- Catheters
- Cystoscopes
- Dialysis Consumables
- Dialysis Devices
- Dilator Sets & Urethral Access Sheaths
- Drainage Bags
- Endoscopes
- Endoscopy Fluid Management Systems
- Endovision & Imaging Systems
- External Catheters
- Guidewires
- Hemodialysis Devices
- Indwelling/ Foley Catheters
- Insufflators
- Intermittent Catheters
- Laparoscopes
- Laser & Lithotripsy Devices
- Nephroscopes
- Other Consumables & Accessories
- Other Instruments
- Peritoneal Dialysis Devices
- Resectoscopes
- Retrieval Devices & Extractors
- Robotic Systems
- Stents And Implants
- Surgical Dissectors, Forceps & Needle Holders
- Tubes & Distal Attachments
- Ureteroscopes
- Urodynamic Systems
By Application
- Benign Prostatic Hyperplasia (Bph)
- Erectile Dysfunction
- Kidney Diseases
- Other Applications
- Pelvic Organ Prolapse
- Urinary Incontinence (Ui)
- Urinary Stones
- Urological Cancer
By End User
- Ambulatory Surgery Centers
- Clinics
- Dialysis Centers
- Home Care Settings
- Hospitals
Target Audience
- Medical Device Manufacturers : Urology device manufacturers need Latin America market intelligence to identify growth opportunities, assess competitive landscapes in Brazil and Mexico, and develop localized product strategies for regional expansion.
- Healthcare Investors & PE Firms : Investment professionals require detailed market sizing and growth forecasts for Latin America's urology sector to evaluate acquisition targets, portfolio companies, and capital allocation decisions in the healthcare devices space.
- Hospital & Healthcare Systems : Latin American hospital networks and healthcare providers need market data to optimize procurement strategies, budget planning for urology departments, and identify emerging device technologies for patient care improvement.
- Regulatory & Market Access Consultants : Consultants supporting device companies in Latin America require regional market insights to navigate regulatory pathways, reimbursement landscapes, and market entry strategies specific to individual countries.
- Healthcare Policy & Government Agencies : Latin American health ministries and policy makers need market intelligence to inform healthcare infrastructure investments, procurement policies, and strategic planning for urological care accessibility and quality.
Key Companies in the Latin America Urology Devices Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| SIEMENS HEALTHINEERS | Germany | Public Company | Imaging,Diagnostics,Varian (Oncology), |
| NOVANTA, INC | United States | Public Company | Precision Medicine and Manufacturing (lasers, beam steering, robotic motion, end-of-arm tooling, spindles),Medical Solutions (insufflators, pumps, disposables, imaging, RFID, light engines, OR integration), |
| LUMENIS LTD | Israel | Private Company | Surgical,Ophthalmic,Aesthetic, |
| MERIT MEDICAL | United States | Public Company | Cardiovascular (cardiac and peripheral intervention, access, hemostasis, fluid and hemodynamic management),Oncology and Spine (soft tissue biopsy, vertebral augmentation, RFA, bone biopsy),Endoscopy (gastroenterology and pulmonary, including stents, cryoballoon, dilators, kits), |
| FRESENIUS MEDICAL CARE AG & CO. KGAA | Germany | Public Company | Care Delivery (dialysis clinics and services),Dialysis equipment and disposables,Renal pharmaceuticals and ancillary services, |
| BOSTON SCIENTIFIC CORPORATION | United States | Public Company | Cardiovascular (structural heart, CRM, electrophysiology, peripheral interventions),MedSurg – Endoscopy (GI, pancreaticobiliary, infection prevention, single-use scopes),MedSurg – Urology and Pelvic Health, |
| B. BRAUN MELSUNGEN AG | Germany | Private Company | Infusion therapy and smart infusion management,Sterile processing, OR supply, and surgical asset management,Standard and customized procedure kits, |
| BECTON, DICKINSON AND COMPANY | United States | Public Company | Medical Essentials (med-surg disposables, injection, vascular access, sharps),Connected Care (infusion, medication management, pharmacy automation, informatics),BioPharma Systems (prefillable drug delivery systems), |
| OLYMPUS CORPORATION | Japan | Public Company | Gastrointestinal Solutions,Surgical Endoscopes & Integrated OR,Urology Solutions, |
| CARDINAL HEALTH | United States | Public Company | Branded Pharmaceutical Distribution,Generic and OTC Pharmaceutical Distribution,Specialty Pharmaceutical and Manufacturer Services, |
| INTUITIVE SURGICAL | United States | Public Company | da Vinci systems (capital),da Vinci instruments, accessories, and stapling/energy,Ion endoluminal system and accessories, |
| COLOPLAST A/S | Denmark | Public Company | Ostomy Care (SenSura Mio, SenSura, Brava),Continence Care (SpeediCath, Conveen, Peristeen),Advanced Wound Dressings and Biologics (Biatain, Comfeel), |
| STRYKER | United States | Public Company | Orthopaedics (hips, knees, shoulders, ankle, trauma and extremities, Mako Shoulder-linked implants),MedSurg equipment and patient handling (surgical equipment, patient and caregiver safety, emergency and ICU disposables),Neurotechnology and stroke care (navigation, endoscopy, stroke and venous thromboembolism treatment, brain and skull procedures), |
| TELEFLEX INCORPORATED | United States | Public Company | Vascular and Emergency Medicine (Arrow, EZ-IO, FAST1, QuikClot),Interventional (coronary, structural heart, peripheral, closure, OnControl),Surgical (Weck, MiniLap, Pleur-Evac, Deknatel, KMedic, Pilling, Titan SGS), |
| CONVATEC GROUP PLC | United Kingdom | Public Company | Advanced Wound Care,Ostomy Care,Continence Care, |
| MEDTRONIC PLC | Ireland | Public Company | Cardiovascular Portfolio,Neuroscience Portfolio,Medical Surgical Portfolio (incl. Diabetes), |
SIEMENS HEALTHINEERS
Siemens Healthineers is a German public company founded in 1896 with 72,369 employees, operating in the healthcare technology sector.
NOVANTA, INC
Novanta, Inc. is a United States-based public company founded in 1968 with 3,000 employees.
LUMENIS LTD
Lumenis Ltd. is an Israeli private company founded in 1991 with 954 employees.
MERIT MEDICAL
Merit Medical is a United States-based public company founded in 1987 with 7,500 employees.
FRESENIUS MEDICAL CARE AG & CO. KGAA
Fresenius Medical Care AG & Co. KGaA is a German public company founded in 1996 with 108,165 employees, operating as a major healthcare provider.
BOSTON SCIENTIFIC CORPORATION
Boston Scientific Corporation is a United States-based public company founded in 1979 with 59,000 employees, specializing in medical devices.
B. BRAUN MELSUNGEN AG
B. Braun Melsungen AG is a German private company founded in 1839 with 61,583 employees, operating in the medical and pharmaceutical sectors.
BECTON, DICKINSON AND COMPANY
Becton, Dickinson and Company is a United States-based public company founded in 1897 with 72,000 employees, specializing in medical technology and diagnostics.
OLYMPUS CORPORATION
Olympus Corporation is a Japanese public company founded in 1919 with 28,138 employees, operating in imaging and medical technology.
CARDINAL HEALTH
Cardinal Health is a United States-based public company founded in 1979 with 55,392 employees, operating as a healthcare services and products distributor.
INTUITIVE SURGICAL
Intuitive Surgical is a United States-based public company founded in 1995 with 17,021 employees, specializing in robotic surgical systems.
COLOPLAST A/S
Coloplast A/S is a Danish public company founded in 1954 with 17,083 employees, specializing in medical devices and healthcare products.
STRYKER
Stryker is a United States-based public company founded in 1941 with 56,000 employees, operating in medical technology and surgical equipment.
TELEFLEX INCORPORATED
Teleflex Incorporated is a United States-based public company founded in 1943 with 15,500 employees, specializing in medical devices.
CONVATEC GROUP PLC
ConvaTec Group PLC is a United Kingdom-based public company founded in 1978 with 10,910 employees, operating in medical technology and healthcare products.
MEDTRONIC PLC
Medtronic PLC is an Ireland-based public company founded in 1949 with 95,000 employees, operating as a global leader in medical technology.
Countries within Latin America - compare and drill down
| Country | 2025 size (native) |
|---|---|
| Brazil | USD 2042.1 Million |
| Mexico | USD 1049.3 Million |
| Rest Of Latin America | USD 1150 Million |
Country market size visualization
Reasons to Buy this Report
- Country-Level Market Segmentation : Access detailed market sizing for Brazil and Mexico, the two largest urology device markets in Latin America, enabling targeted market entry and resource allocation strategies specific to each country's healthcare landscape.
- Growth Trajectory Insights : Understand the 3.4% CAGR trajectory through 2030 with forecasted market expansion from USD 1,847.6M to USD 2,183.6M, providing clear visibility into regional growth opportunities and investment timelines.
- Demographic & Healthcare Trends : Leverage analysis of aging populations, rising healthcare expenditure, and increasing prevalence of urological conditions across Latin America to identify high-potential patient segments and market expansion opportunities.
- Competitive Positioning Strategy : Benchmark your urology device portfolio against regional market dynamics and identify gaps in Latin American healthcare infrastructure, enabling strategic product development and market penetration planning.
- Regulatory & Market Entry Guidance : Gain insights into Latin American healthcare systems, regulatory environments, and market maturity levels across countries to develop compliant, region-specific commercialization strategies and partnership approaches.
Frequently asked questions
What is the current size of the urology devices market in Latin America?
The Latin America urology devices market is estimated at USD 1,847.6 million in 2025.
What is the projected market size for urology devices in Latin America by 2030?
Latin America's urology devices market is projected to reach USD 2,183.6 million by 2030.
What is the CAGR for the urology devices market in Latin America?
Latin America's urology devices market is growing at a CAGR of 3.4% from 2025 to 2030.
What factors are driving growth in Latin America's urology devices market?
Latin America's market growth is driven by aging populations, increasing prevalence of urological conditions, rising healthcare expenditure, and expanding access to advanced diagnostic and therapeutic technologies.
Which countries represent the largest markets for urology devices in Latin America?
Brazil and Mexico are among the key markets within Latin America experiencing significant demand for urology devices and minimally invasive urological procedures.
RESEARCH METHODOLOGY
This research study extensively used secondary sources, directories, and databases to identify and collect valuable information to analyze the global urology devices market. In-depth interviews were conducted with various primary respondents, including key industry participants, subject-matter experts (SMEs), C-level executives of key market players, and industry consultants, to obtain and verify critical qualitative & quantitative information and assess the growth prospects in the market. The global market size estimated through secondary research was then triangulated with inputs from primary research to arrive at the final market size.
Secondary Research
Secondary research was used primarily to identify & collect information for the extensive, technical, market-oriented, and commercial study. The secondary sources used for this study include annual reports, SEC filings, investor presentations, World Health Organization (WHO), US Food and Drug Administration (US FDA), National Center for Biotechnology Information (NCBI), Health Canada, European Medicines Agency (EMA), and Centers for Disease Control and Prevention (CDC). These sources also obtained key information about major players, market classification, and segmentation according to industry trends, regional/country-level markets, market developments, and technology perspectives.
Primary Research
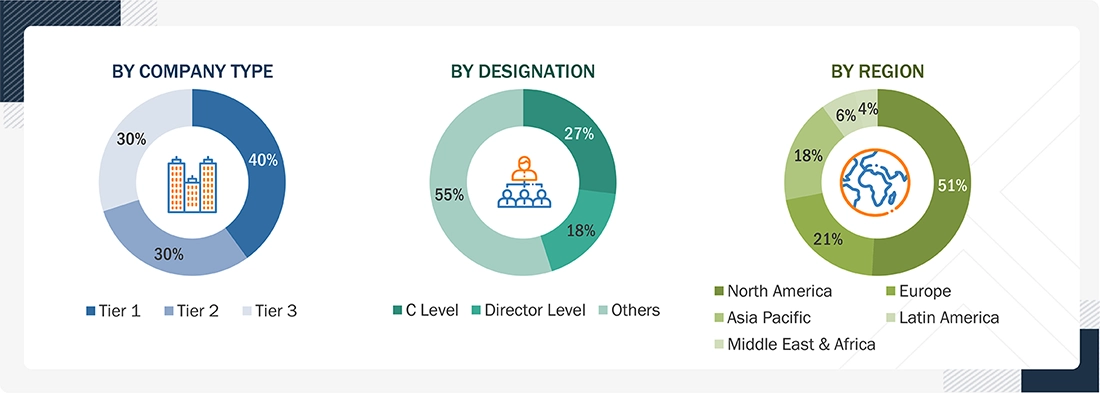
In-depth interviews were conducted with various primary respondents, including key industry participants, subject-matter experts (SMEs), C-level executives of key market players, and industry consultants, to obtain and verify the critical qualitative & quantitative information and assess the prospects of the market. Various primary sources from both the supply & demand sides of the market were interviewed to obtain qualitative and quantitative information. The following is a breakdown of the primary respondents:
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
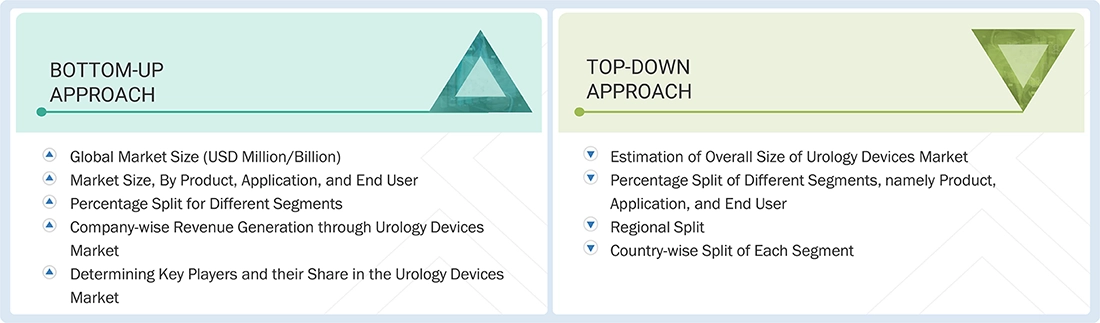
Both top-down and bottom-up approaches were used to estimate and validate the total size of the urology devices market. These methods were also used extensively to estimate the size of various subsegments in the market. The research methodology used to estimate the market size includes the following:
Urology Devices Market : Top-Down and Bottom-Up Approach
Data Triangulation
The total market was split into several segments and subsegments after arriving at the overall market size from the estimation process. Where applicable, data triangulation and market breakdown procedures were employed to complete the overall market engineering process and arrive at the exact statistics for all segments and subsegments. The data was triangulated by studying various factors and trends from both the demand and supply sides.
Market Definition
Urology is a medical specialty that deals with the physiology, diseases, and disorders of the human urinary tract and male reproductive organs. Urology devices comprise various types of equipment used during the diagnosis, surgery, and treatment of urological diseases, such as chronic kidney diseases, renal failure, urinary stones, benign prostate hyperplasia (BPH), pelvic organ prolapse (POP), prostate cancer, kidney cancer, bladder cancer, and erectile dysfunction.
Key Stakeholders
- Manufacturers and Distributors of Urology Devices
- Hospitals and ASCs
- Academic Research Institutes
- Urology Clinics
- Urology Device Service Providers
- Venture Capitalists and Investors
- Clinical Research Organizations (CROs)
Report Objectives
- To define, describe, and forecast the urology devices market by product, application, end user, and region
- To forecast the size of the urology devices market with respect to five regional segments, namely, North America, Europe, the Asia Pacific, Latin America, and the Middle East & Africa
- To provide detailed information regarding the major factors influencing market growth (drivers, restraints, opportunities, and challenges)
- To analyze the micromarkets with respect to individual growth trends, prospects, and contributions to the overall urology devices market
- To analyze the opportunities in the market for stakeholders and provide details of the competitive landscape for market leaders
- To profile the key players in the urology devices market and comprehensively analyze their market shares and core competencies in terms of market developments and growth strategies
- To track and analyze competitive developments such as product launches, product approvals, mergers, agreements, collaborations, partnerships, expansions, and acquisitions in the urology devices market
- To benchmark players within the urology devices market using the Company Evaluation Matrix framework, which analyzes market players on various parameters within the broad categories of business strategy, market share, and product offerings
To track and analyze competitive developments such as acquisitions, product launches, expansions, agreements, collaborations, and partnerships in the urology devices market
Customization Options
With the given market data, MarketsandMarkets offers customizations per the company’s specific needs. The following customization options are available for this report:
Portfolio Assessment
- Product Matrix gives a detailed comparison of the product portfolios of the top five companies.
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Geographical Analysis
- A further breakdown of the Rest of Europe’s urology devices market into countries
- A further breakdown of the Rest of Asia Pacific’s urology devices market into countries
- A further breakdown of Latin America’s urology devices market into countries
Get the Full Urology Devices Market Report
Full forecast, segment splits, and company analysis for all Urology Devices Market.
- US Urology Devices Market
- Canada Urology Devices Market
- Germany Urology Devices Market
- UK Urology Devices Market
- France Urology Devices Market
- Italy Urology Devices Market
- Spain Urology Devices Market
- China Urology Devices Market
- Japan Urology Devices Market
- India Urology Devices Market
- Brazil Urology Devices Market
- Mexico Urology Devices Market
- Rest Of Europe Urology Devices Market
- Rest Of Asia Pacific Urology Devices Market
- Rest Of Latin America Urology Devices Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
