Green Data Center Market

Green Data Center Market by Infrastructure (Renewable Power Generator, Energy Effective Power Distribution, Power Backup & Energy Storage, Green Air Cooling, Green Liquid Cooling), Software (DCIM, Building Management, Compliance) - Global Forecast to 2031




OVERVIEW
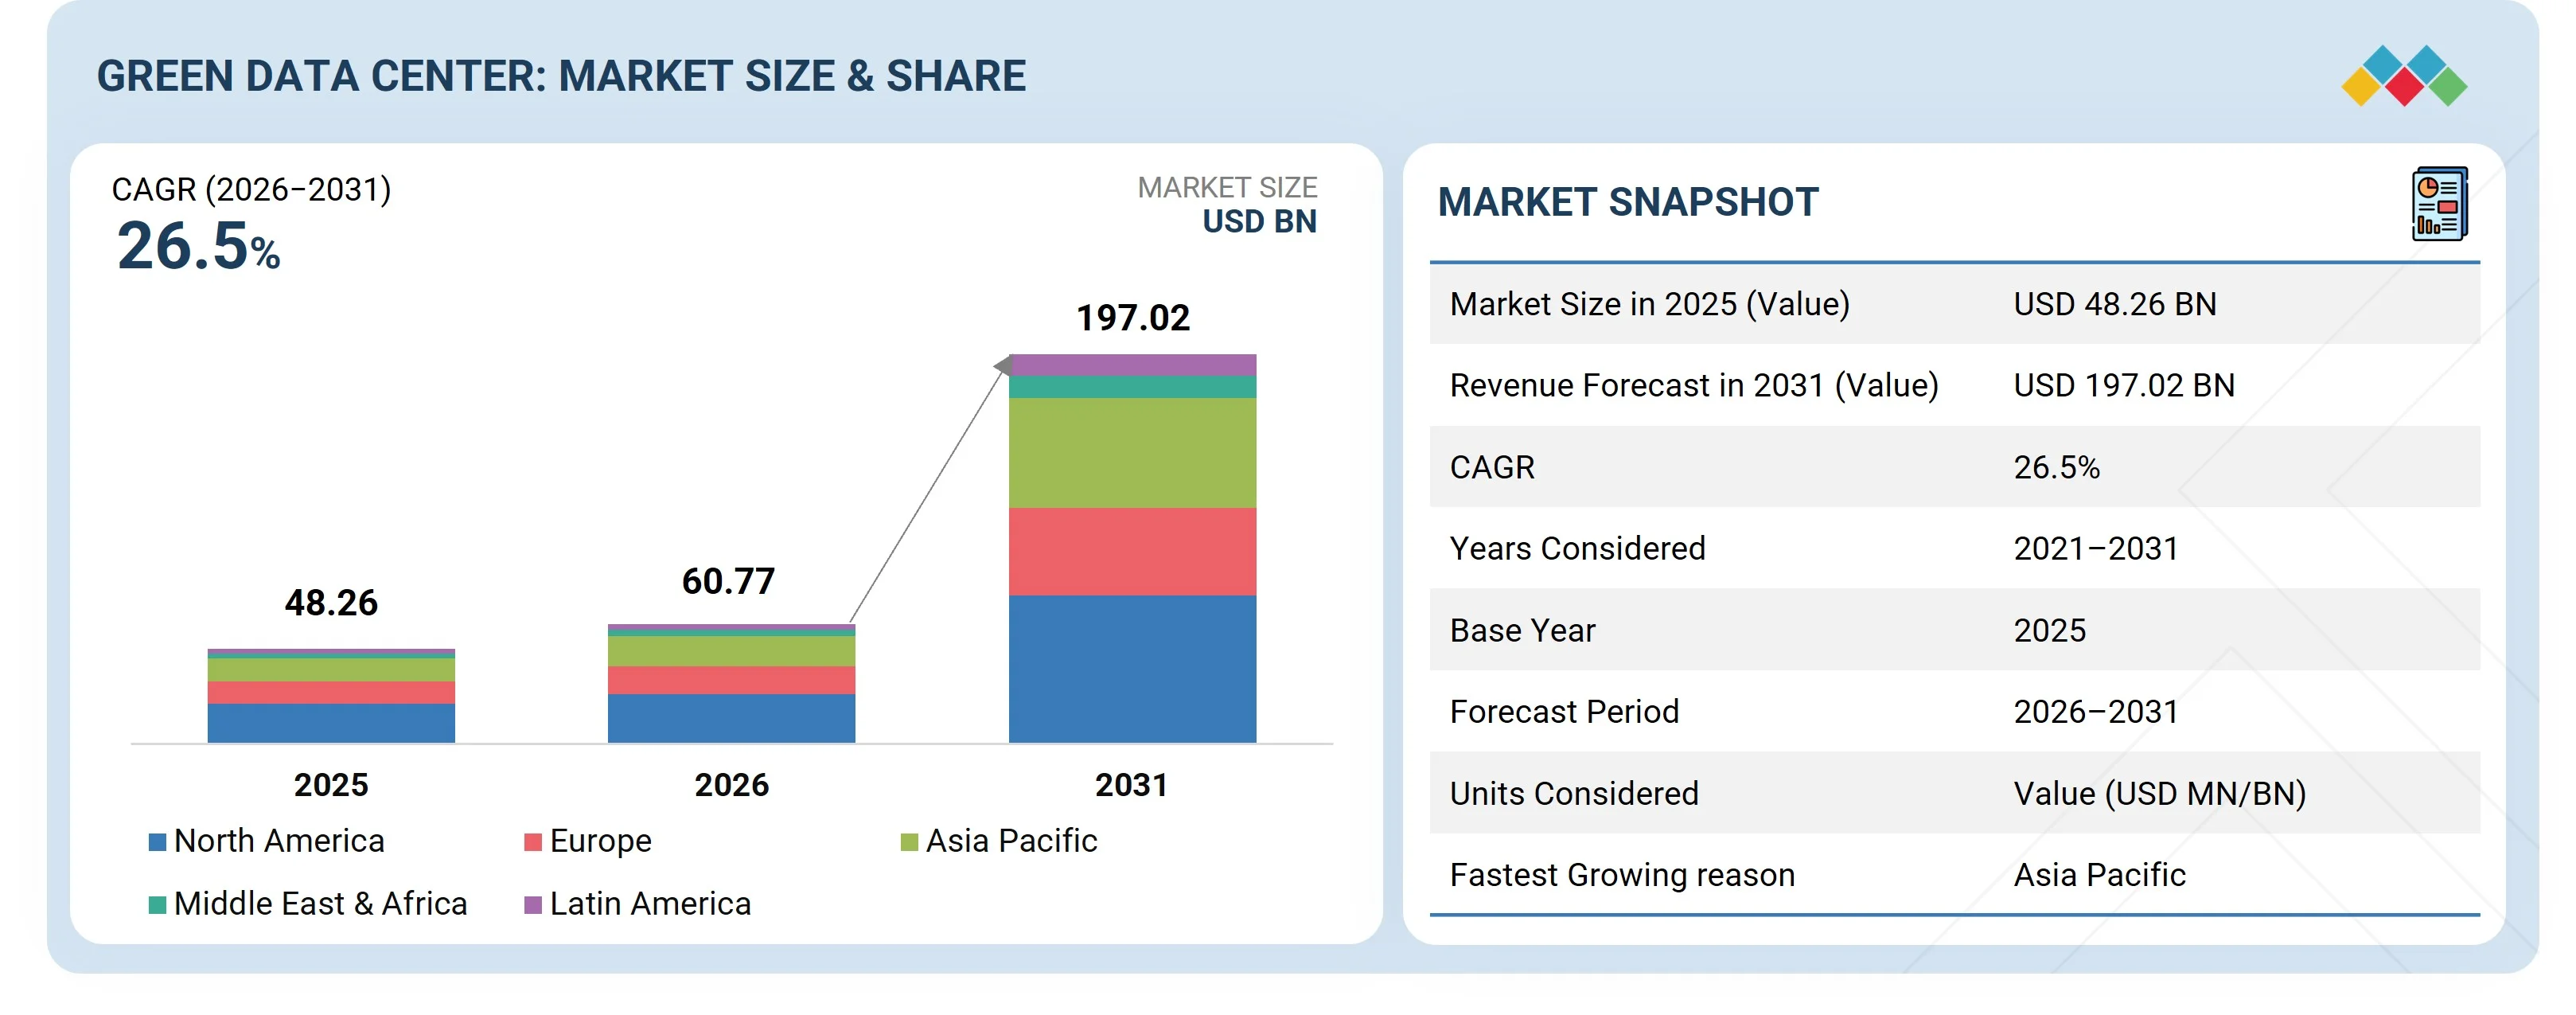
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The green data center market is projected to reach USD 197.02 billion by 2031 from USD 60.77 billion in 2026, at a CAGR of 26.5%. The global market is gaining momentum as data center operators and enterprises respond to rising energy costs, increasingly stringent sustainability regulations, and growing commitments to reduce carbon emissions. The adoption of advanced cooling technologies, renewable energy integration, and energy-efficient power management systems is enabling operators to optimize energy consumption and operating costs while progressing toward environmental objectives. Growing ESG requirements, government initiatives, and sustainability targets are further supporting the adoption of green data center infrastructure among enterprises seeking to improve regulatory compliance and operational efficiency. By combining energy efficiency, resource optimization, and operational resilience, green data centers are becoming an increasingly important component of sustainable digital infrastructure.
Green Data Center Market Size and Forecast:
- 2026 Market Size: USD 60.77 Billion
- 2031 Forecasted Market Size: USD 197.02 Billion
- Growth Rate (2026-2031): CAGR of 26.5%
- Years Considered: 2021–2031
Key Market Trends and Insights
- Key Trends: Rising adoption of energy-efficient infrastructure, renewable energy, liquid cooling, and sustainable data center operations.
-
Fastest Growing Segment: The software segment is the fastest-growing component of the Green Data Center Market, projected to expand at a 30.4% CAGR from 2025 to 2030.
- Trending Opportunities: Energy-efficient cooling, renewable power, liquid cooling, AI-driven energy optimization, and sustainable data center infrastructure.
- Driving Factors: Rising AI workloads, energy costs, net-zero mandates, renewable energy adoption, and demand for energy-efficient cooling systems.
KEY TAKEAWAYS
-
BY REGIONNorth America is estimated to dominate the market with the highest value of USD 25.12 billion by 2026.
-
BY COMPONENTThe infrastructure segment is expected to hold the largest market value of USD 39.31 billion by 2026.
-
BY SOFTWAREThe building management software is projected to grow at the highest CAGR of 32.1% during the forecast period.
-
BY DATA CENTER TYPECloud and hyperscale data centers are expected to dominate the market during the forecast period.
-
BY ENTERPRISE DATA CENTERRetail and e-commerce enterprises are projected to grow at the highest CAGR during the forecast period.
-
COMPETITIVE LANDSCAPE - Key PlayersSchneider Electric, Vertiv, Eaton, Daikin, and ABB are entering into agreements and collaborations to meet the growing demand for sustainable data center solutions, such as efficient PDUs, AI-based energy monitoring, and green cooling infrastructure.
-
COMPETITIVE LANDSCAPE - SMEsZutacore, Inc., Submer, MIDAS Immersion Cooling (MIDAS), Green Revolution Cooling (GRC), Nortek Data Center Cooling, ASETEK, Inc., and Packet Power have distinguished themselves among startups and SMEs by securing strong footholds in the global green data center market.
The global green data center market is gaining traction as data center operators and enterprises increasingly prioritize energy efficiency and sustainability in response to rising energy costs, stringent environmental regulations, and growing corporate commitments to carbon reduction.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
This section highlights the key trends and market disruptions shaping the green data center ecosystem, with a focus on how revenue opportunities are evolving through the adoption of emerging technologies and new sustainability-driven use cases. It examines the changing priorities of key customer segments, including hyperscale and cloud service providers, colocation and data center operators, and government and public-sector organizations. The analysis links these strategic priorities to measurable business outcomes such as energy-efficient and sustainable cooling infrastructure, reduced PUE, lower carbon emissions, improved resource efficiency, and enhanced corporate sustainability performance and brand reputation.
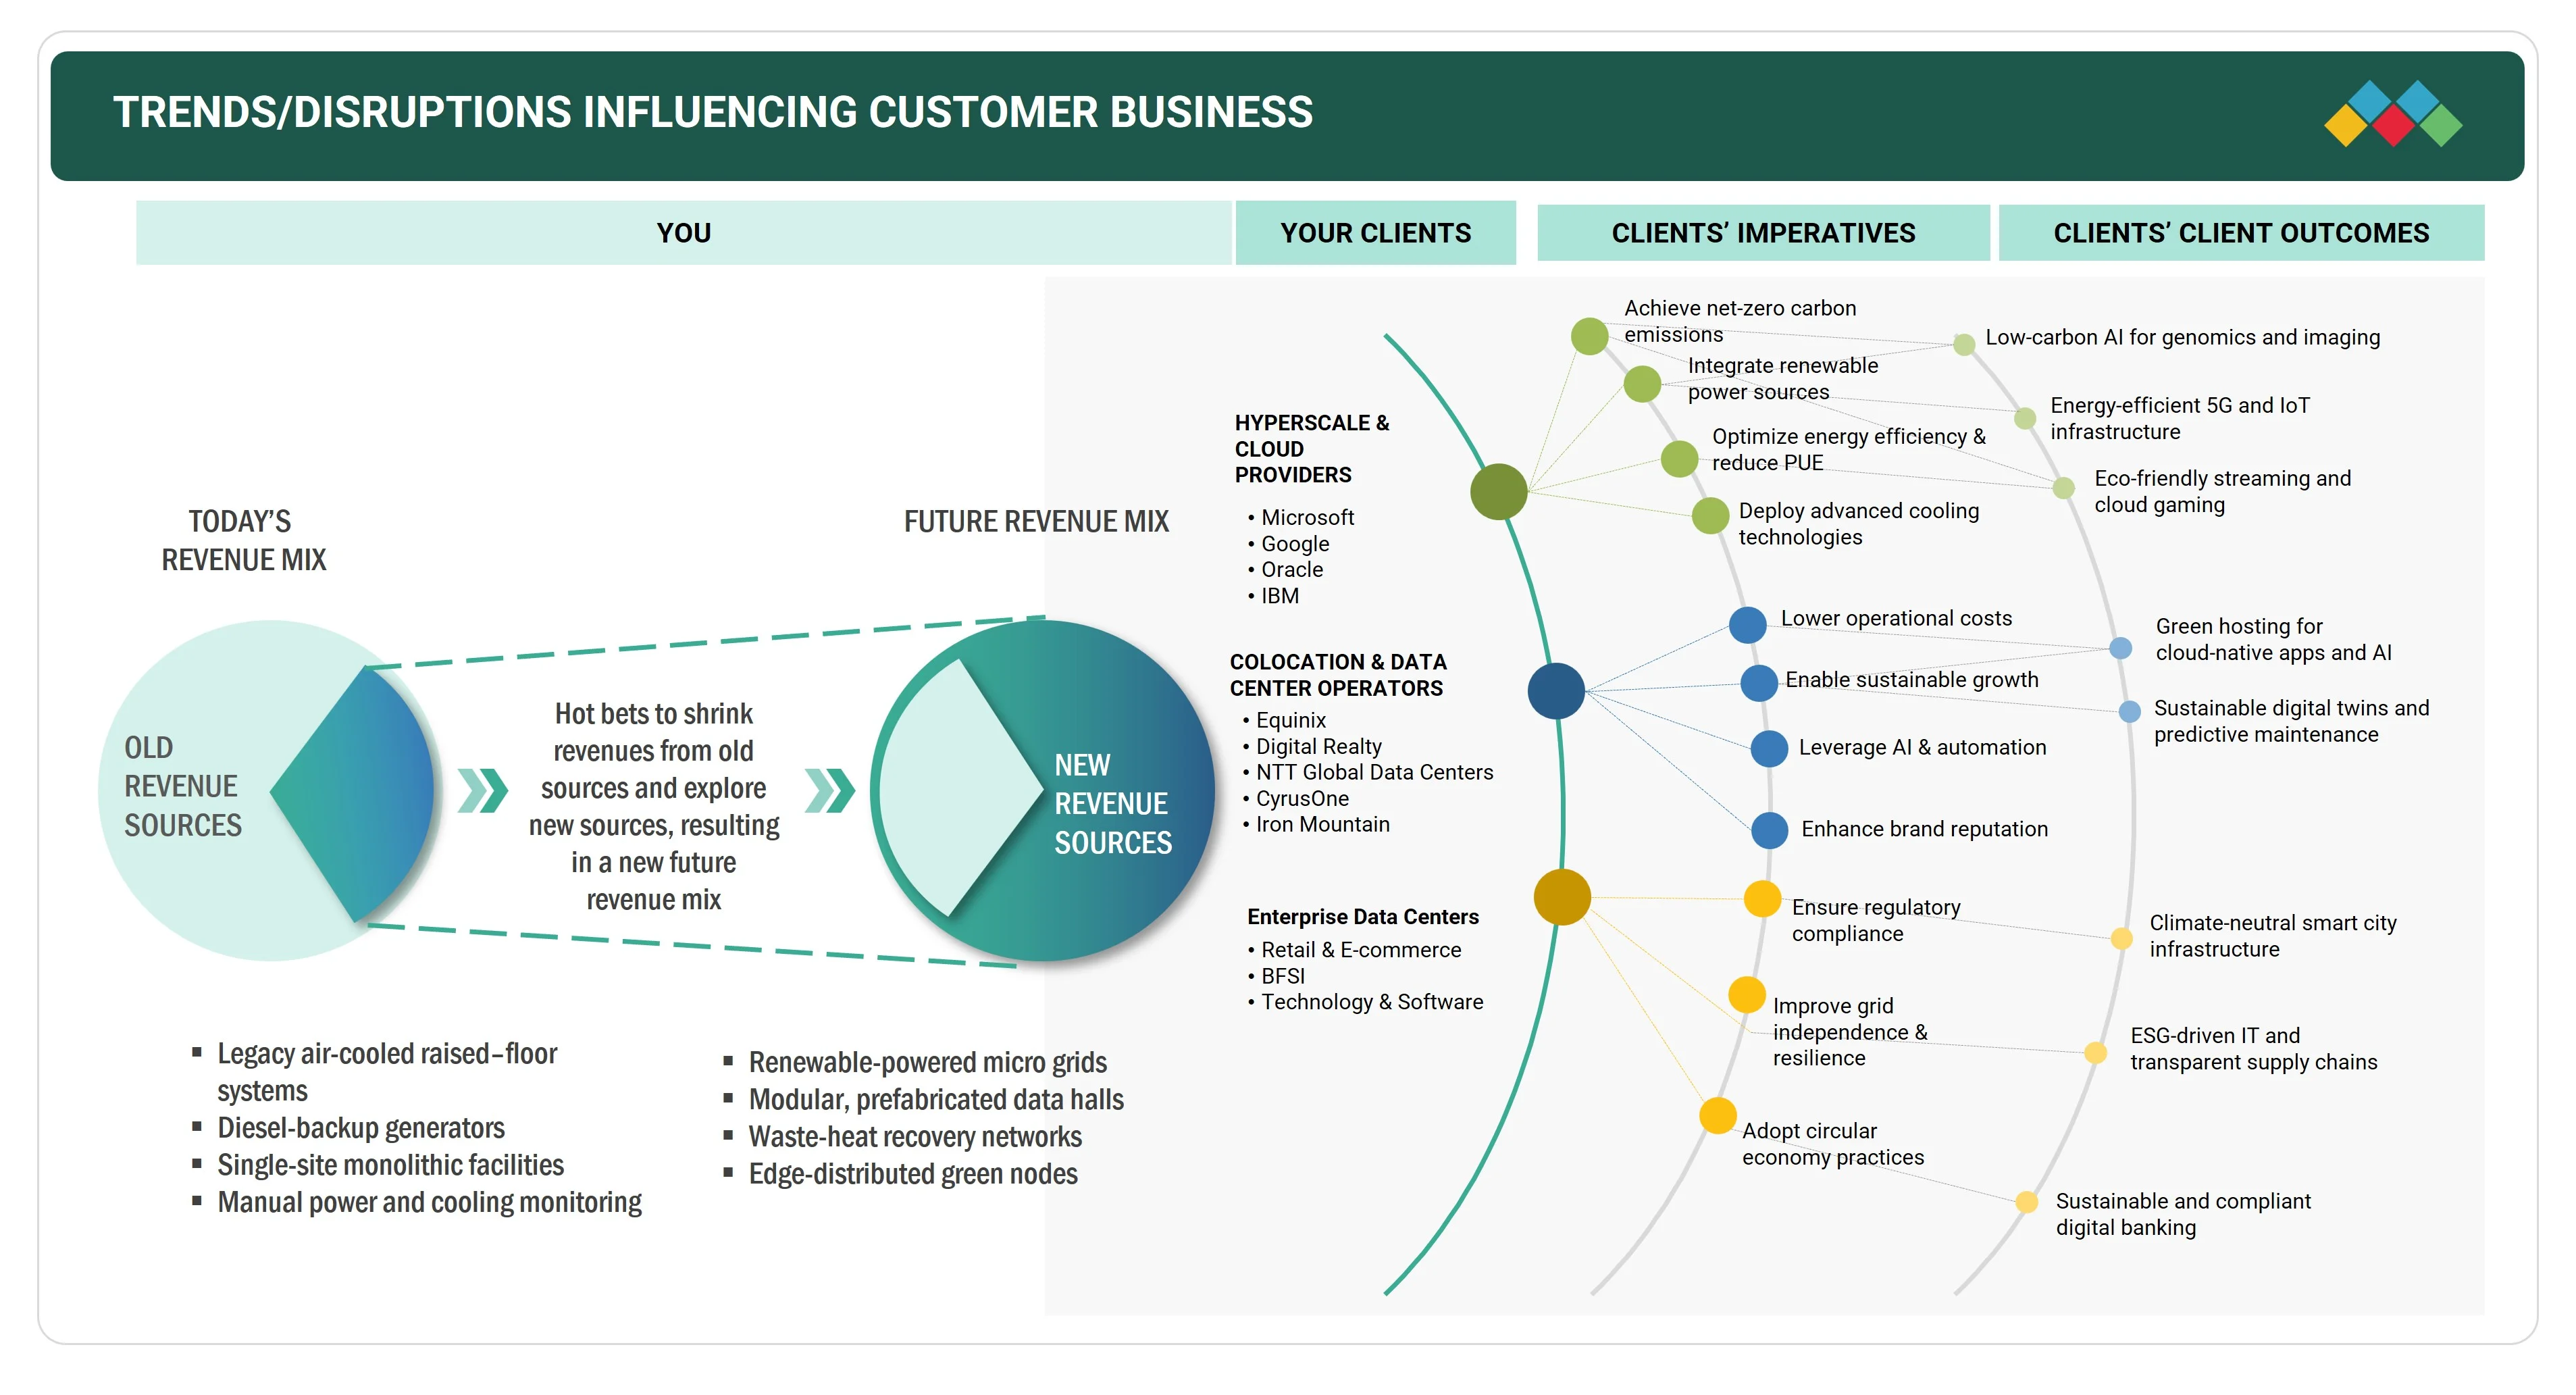
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
AI workloads to drive adoption of green data center solutions

-
Net-zero mandates to accelerate renewable-powered facilities


Level
-
Limited renewable availability to restrict large-scale deployments

-
High upfront CAPEX to slow green data center adoption


Level
-
Prefabricated green modules to accelerate facility deployment

-
Circular IT asset management to expand service scope


Level
-
Regional policy fragmentation to complicate vendor compliance

-
Supply chain gaps to limit access to eco-friendly components

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: AI workloads to drive adoption of green data center solutions
Rising AI workloads are accelerating the adoption of green data centers, as high-density computing environments require more efficient and sustainable power and cooling solutions. Operators are increasingly deploying advanced liquid cooling technologies and AI-optimized energy management systems to reduce energy consumption while maintaining performance. Schneider Electric’s December 2024 collaboration with NVIDIA on liquid-cooled AI data center reference designs demonstrates how sustainable infrastructure innovations can support scalability, energy efficiency, and the deployment of AI-ready facilities.
Restraint: High upfront CAPEX to slow green data center adoption
High upfront CAPEX remains a significant restraint in the green data center market, as the deployment of sustainable infrastructure often requires substantial investment in technologies such as liquid cooling, renewable energy systems, energy-efficient power equipment, and low-carbon construction materials. These investments can increase initial project costs compared with conventional infrastructure, particularly for facilities requiring extensive retrofits or high-density AI capabilities. Consequently, enterprises and data center operators are increasingly evaluating modular, scalable, and phased deployment models that can distribute capital requirements over time while improving the economic feasibility of green infrastructure adoption.
Opportunity: Prefabricated green modules to accelerate facility deployment
Prefabricated green modules present a strong opportunity in the green data center market by enabling faster deployment, predictable efficiency, and lower environmental impact. Schneider Electric’s June 2025 EcoStruxure Pod Data Center highlights this shift, offering liquid-cooled, renewable-ready infrastructure with reduced deployment time and improved PUE. Modular builds allow vendors to deliver scalable, standardized solutions while generating recurring revenues through bundled services and upgrades.
Challenge: Regional policy fragmentation to complicate vendor compliance
Policy fragmentation poses a critical challenge for the green data center market, with energy, emissions, and reporting requirements differing sharply across regions. The EU’s November 2024 directives mandate detailed metrics, while US rules remain fragmented at the state level, driving compliance complexity and cost. Vendors must adopt adaptive frameworks, flexible reporting tools, and proactive monitoring to ensure sustainable, risk-free growth.
GREEN DATA CENTER MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Greenergy and A-Kaabel drive green data center growth with Vertiv rack PDUs | Seamless scaling from 4-6 kW racks to over 10 kW, improved energy efficiency with PUE reduced to 1.4, enhanced uptime performance surpassing 99.982% |
 |
Siemens supports BMO Financial Group with white space cooling optimization (WSCO) | Achieved 55% reduction in CRAH fan energy consumption, reduced the number of continuously operating CRAH units by 64%, improved thermal control & stability |
|
|
Siemens delivers AI-powered optimization at Greenergy Data Centers, Estonia | Improved cooling efficiency by 30%, achieved a PUE below 1.2, enabled AI-based predictive cooling, and reduced carbon footprint by reusing waste heat for office heating |
 |
Green Revolution Cooling enables green supercomputing at Texas Advanced Computing Center (TACC) with immersion cooling | Achieved a PUE of 1.1, significantly improving energy efficiency, reduced carbon footprint by up to 40%, enabled reliable cooling of 280W CPUs |
 |
Rittal lowers carbon footprint at Scottish Qualifications Authority (SQA) Data Centers | Reduced energy consumption and carbon footprint, freed up floor space by shifting to rack-mounted UPS and in-row cooling, enabled higher system reliability with N+1 redundancy in both cooling and UPS |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
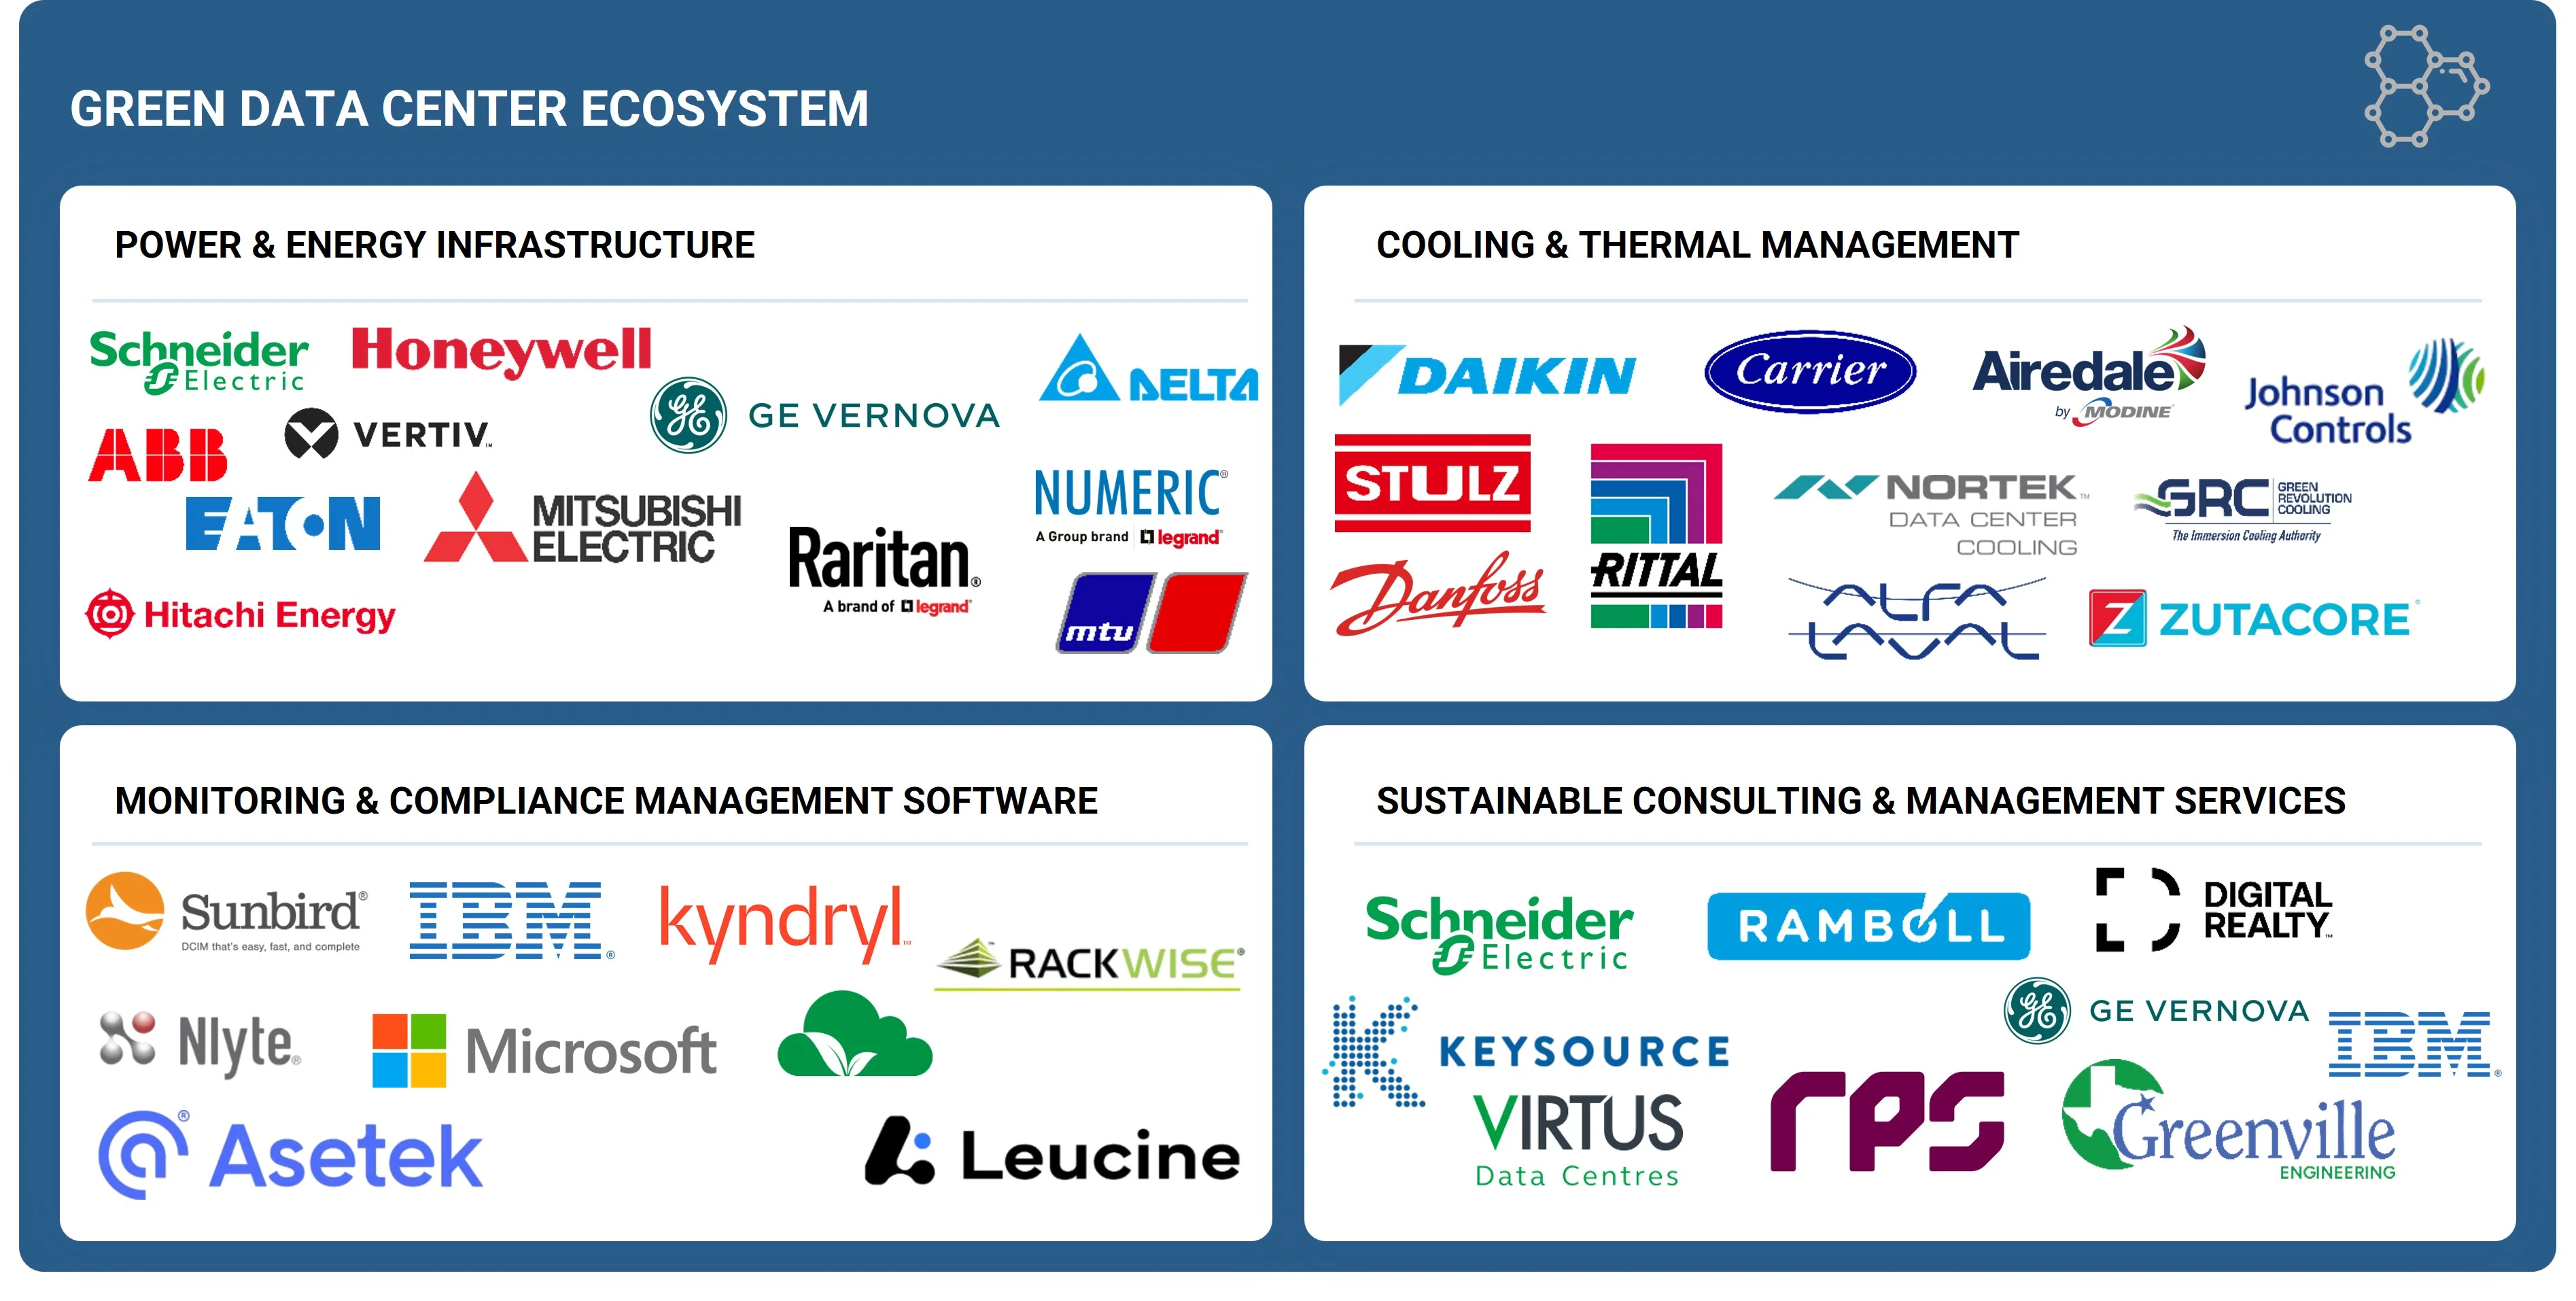
The green data center market ecosystem comprises four key pillars: power and energy infrastructure, cooling and thermal management, monitoring and compliance software, and sustainable consulting services. Together, these pillars provide energy-efficient electrical systems, advanced thermal management solutions, real-time sustainability and ESG monitoring, and strategic advisory support. This integrated ecosystem enables organizations to design, deploy, operate, and optimize energy-efficient, resilient, and net-zero-ready data centers, while supporting continuous improvements in resource utilization, emissions reduction, regulatory compliance, and overall operational sustainability.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Green Data Center Market, By Component
Infrastructure is expected to account for the largest market share in the green data center market, creating significant opportunities for vendors and solution providers to develop and deploy energy-efficient and sustainable infrastructure systems. The integration of renewable energy sources, modular UPS systems, energy-efficient PDUs, and advanced green cooling technologies enables data center operators to reduce energy consumption, operating costs, and carbon emissions. At the same time, advanced cooling systems, intelligent airflow management, and thermal monitoring solutions can improve equipment reliability and optimize cooling performance. These technologies collectively support operators in enhancing energy efficiency, reducing environmental impact, and improving the overall sustainability and resilience of data center infrastructure.
Green Data Center Market, By Data Center Size & Capacity
Large and hyperscale data centers (50 MW and above) are expected to account for the largest market share in the green data center market, serving as critical infrastructure for cloud platforms, AI workloads, and large-scale digital applications. The high power and cooling requirements of these facilities are driving demand for energy-efficient and sustainable infrastructure solutions. Vendors and solution providers can capitalize on opportunities by offering modular high-efficiency power systems, scalable liquid and hybrid cooling technologies, renewable energy integration, and monitoring platforms that provide real-time visibility into energy consumption and emissions. Strategic partnerships with hyperscale operators, renewable energy providers, and technology companies can further support the deployment of sustainable infrastructure while enabling reliable, high-performance operations at scale.
Green Data Center Market, By Data Center Type
Cloud and hyperscale data centers are expected to account for the largest market share in the green data center market, driving the transition toward more sustainable and energy-efficient digital infrastructure. These facilities are increasingly adopting renewable energy, advanced cooling technologies, and high-efficiency power systems to support large-scale computing requirements while reducing energy consumption and environmental impact. Vendors and solution providers can capitalize on this demand by offering modular, scalable, and energy-efficient infrastructure solutions, along with intelligent monitoring and energy management technologies. Strategic partnerships with cloud and hyperscale operators, renewable energy providers, and technology companies can further accelerate the deployment of low-carbon, resilient, and sustainable data center infrastructure across global markets.
Green Data Center Market, By Enterprise Data Center
BFSI will hold the largest market share in enterprise data centers, as the sector requires secure, reliable, and sustainable infrastructure to manage transactions, payments, and risk systems. Green data centers enable BFSI institutions to lower power use with efficient servers, virtualization, and advanced cooling, while ensuring compliance, data privacy, and ESG alignment. Vendors and solution providers gain opportunities to deliver scalable, energy-efficient, and compliant solutions that support financial sector digital transformation.
REGION
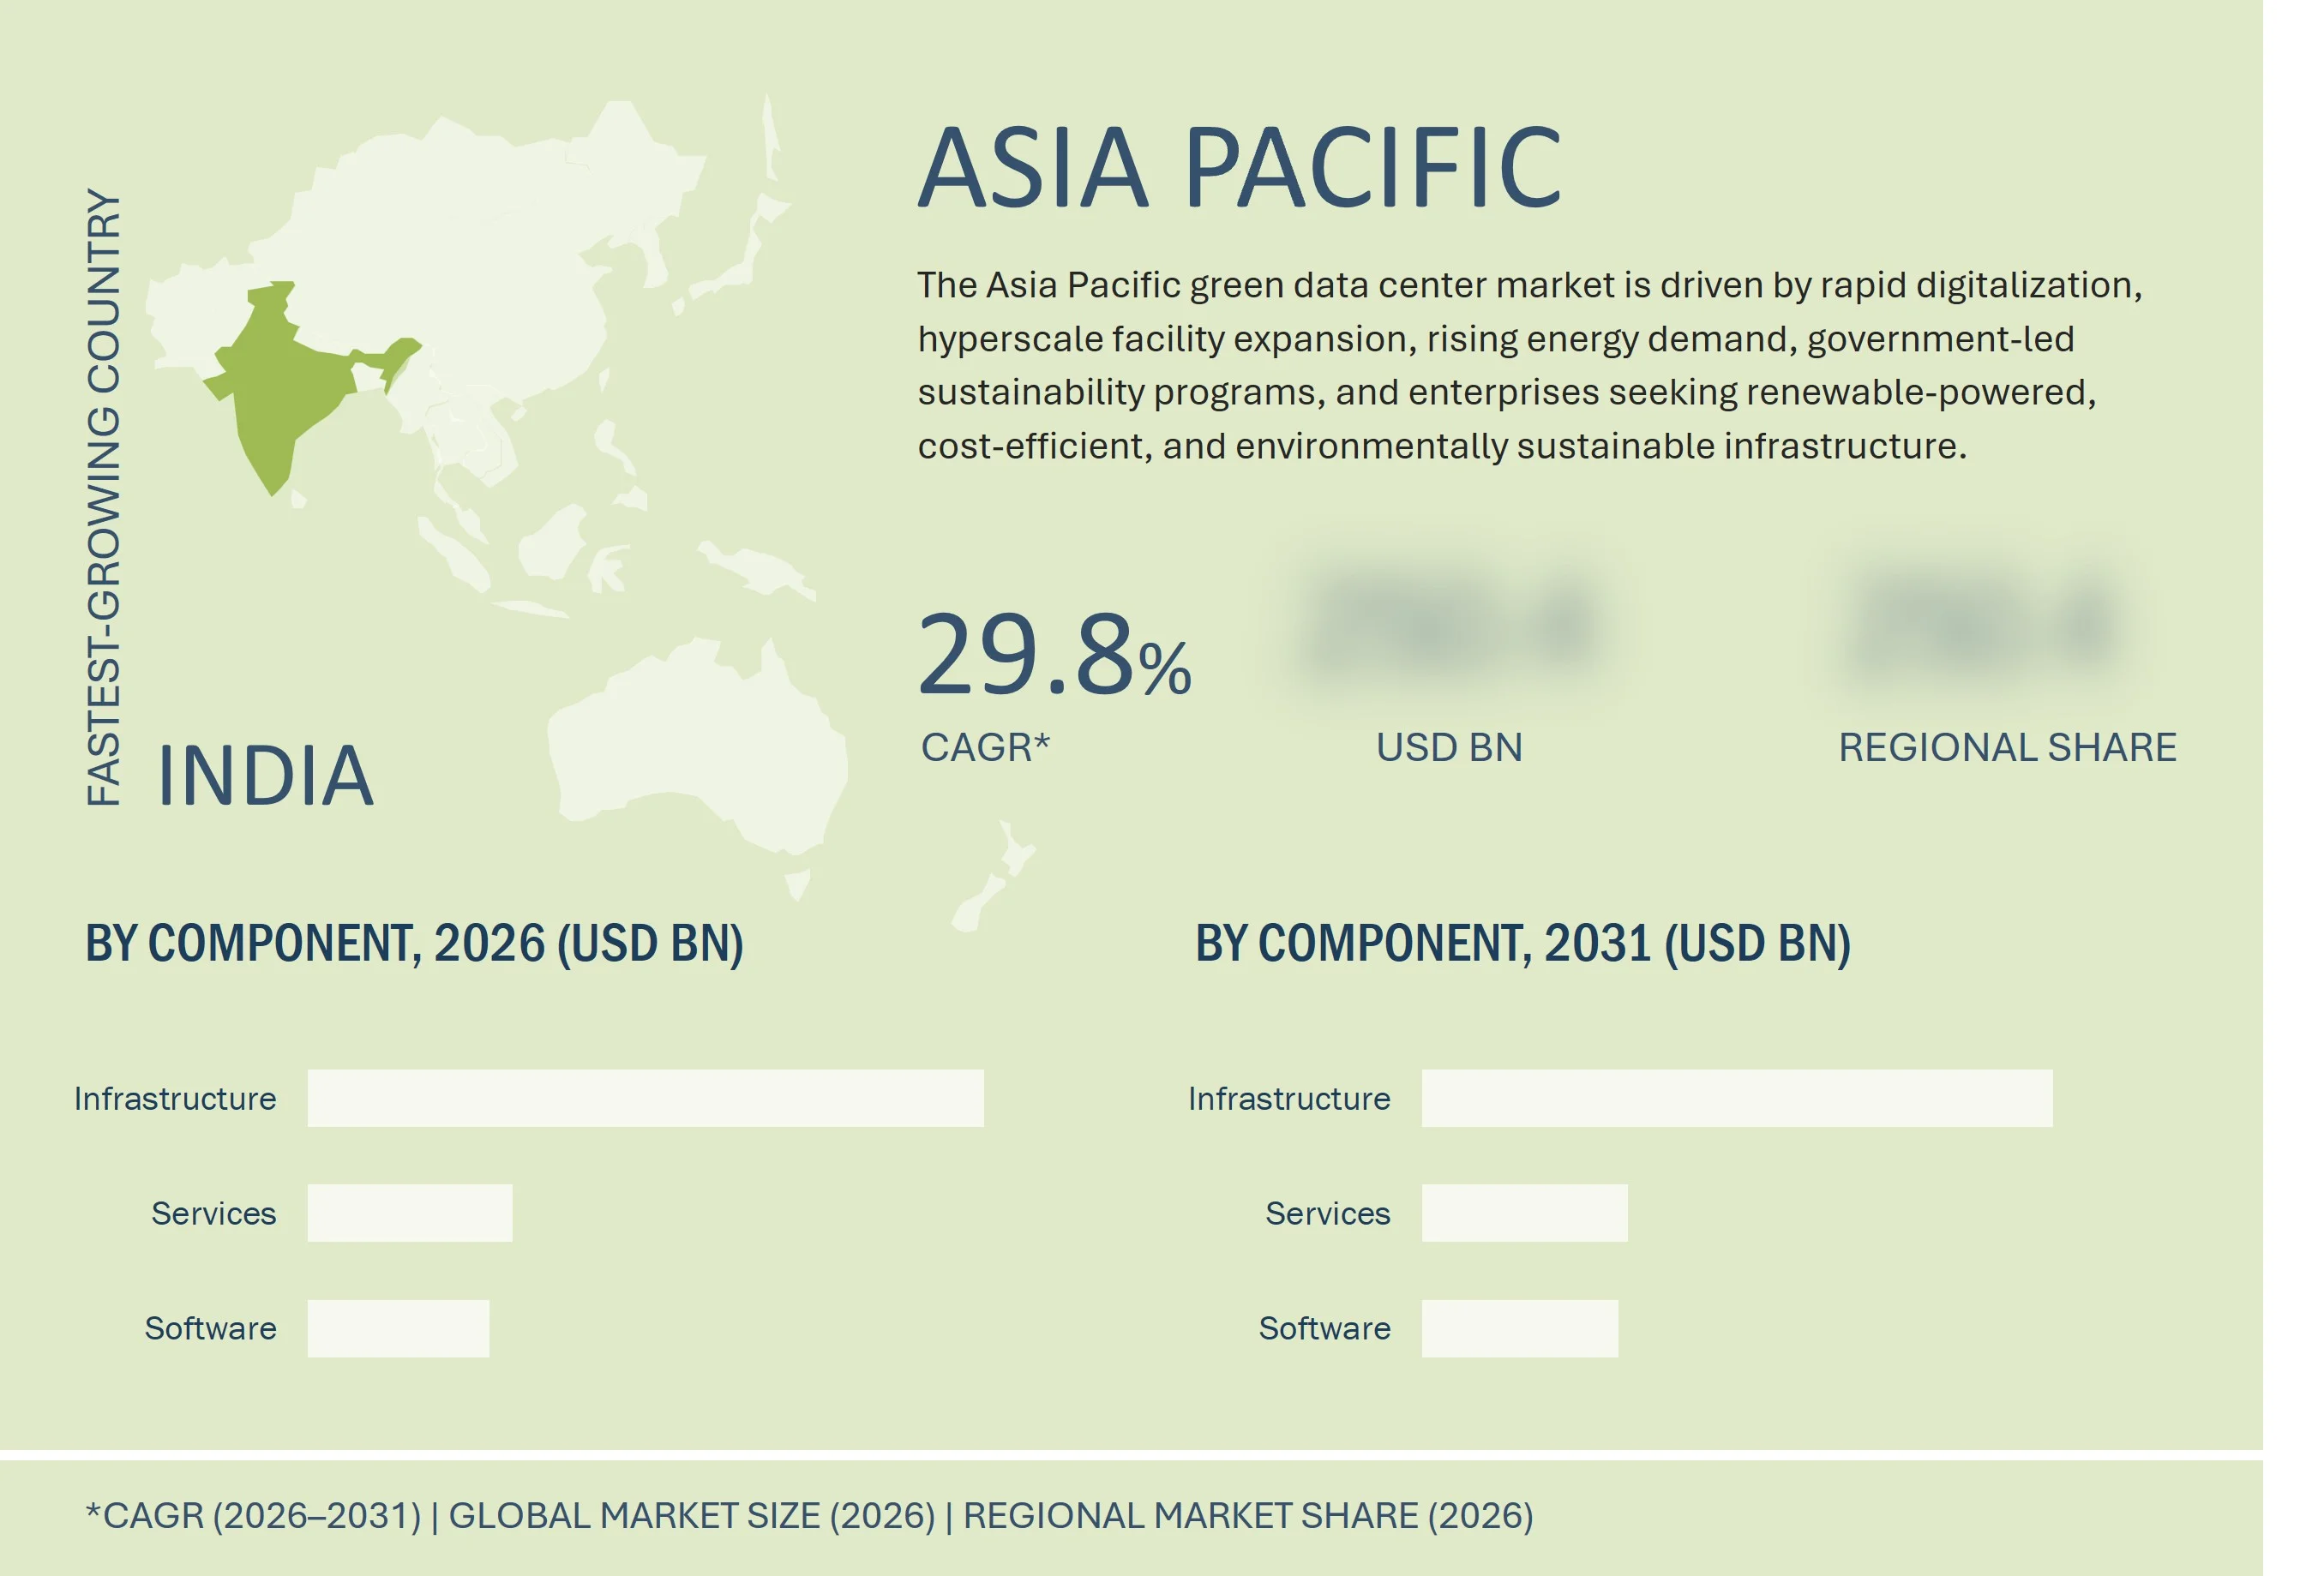
Asia Pacific to be the fastest-growing region in the global green data center market during the forecast period
Asia Pacific is expected to register the highest CAGR during the green data center market forecast period. The region is rapidly emerging as a key hub for green data center development, supported by growing sustainability mandates, rising digital workloads, and increasing demand for energy-efficient infrastructure. Data center operators are increasingly adopting modular power systems, advanced cooling technologies, and AI-enabled energy monitoring solutions to optimize energy consumption and improve operational efficiency. At the same time, the growing deployment of renewable energy sources, including solar, wind, and hydropower, is helping operators reduce carbon emissions and improve the sustainability of data center operations. The adoption of liquid cooling, heat recovery, and energy reuse technologies is further supporting efficient operations across diverse climatic conditions and densely populated urban markets. These developments are creating significant opportunities for vendors to provide scalable, energy-efficient, and low-carbon data center solutions across the Asia Pacific region.
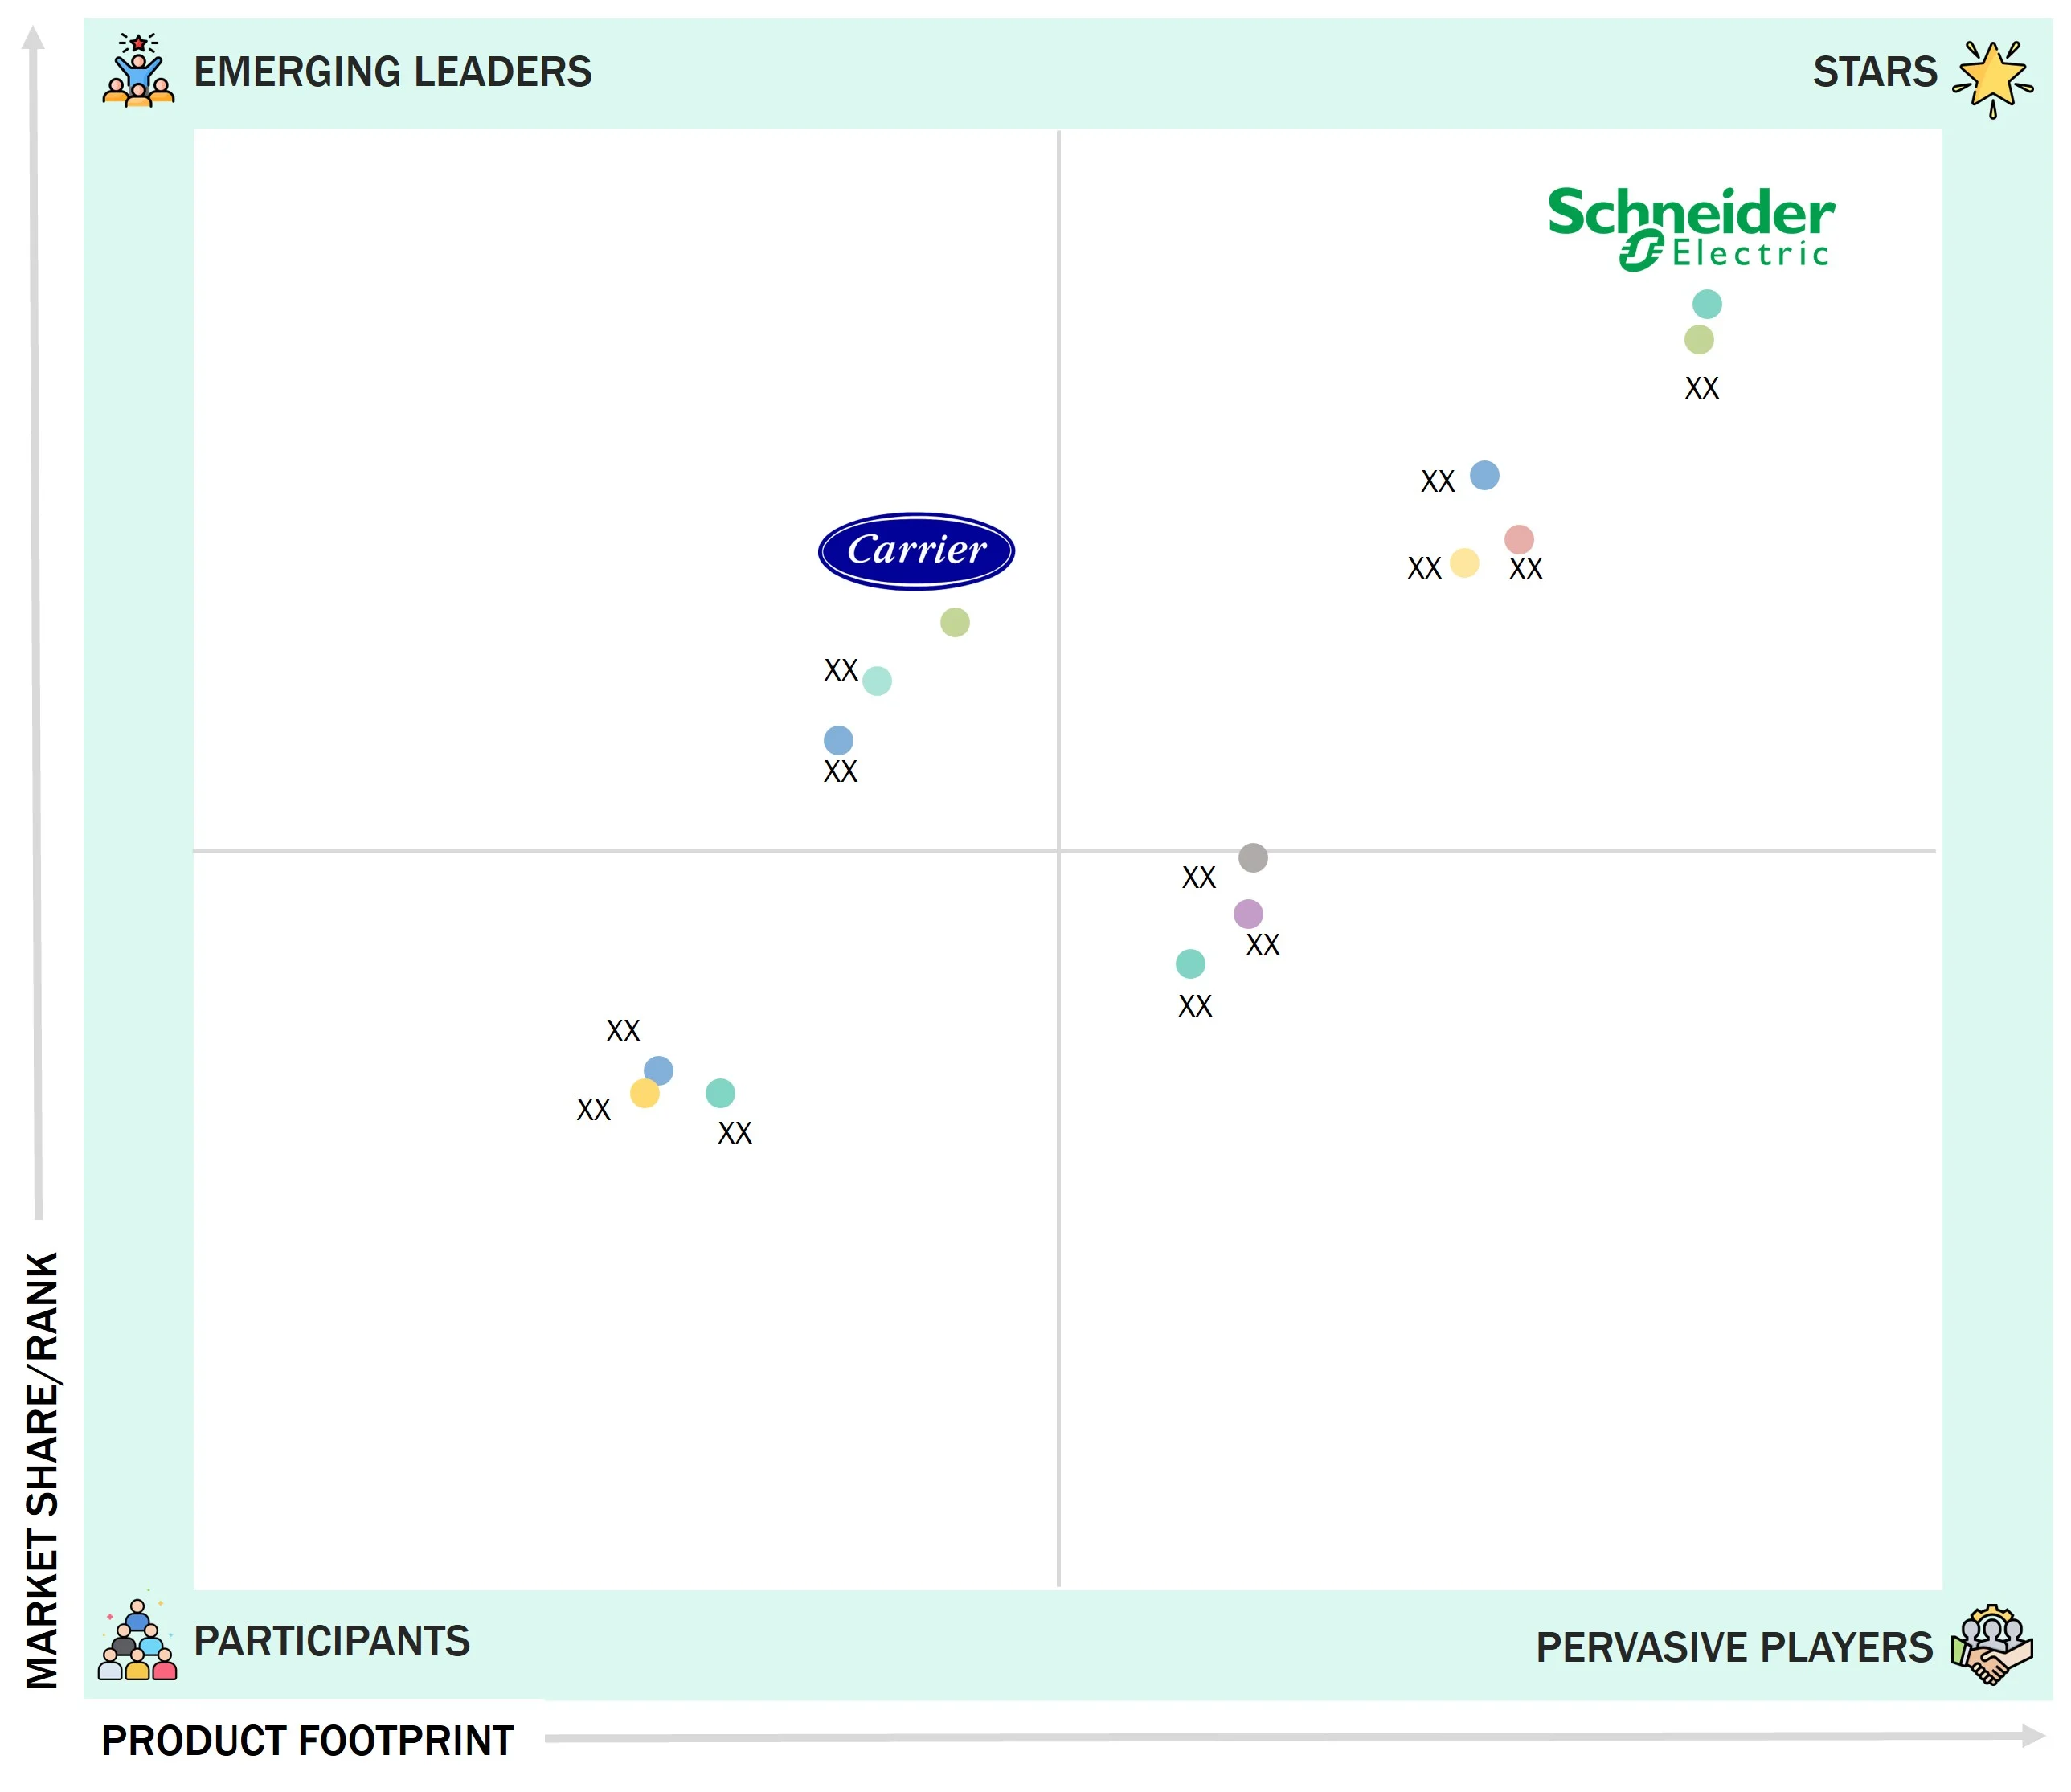
GREEN DATA CENTER MARKET: COMPANY EVALUATION MATRIX
In the green data center market matrix, Schneider Electric (Star) demonstrates a strong market position supported by its comprehensive portfolio covering power infrastructure, cooling systems, and digital energy management solutions, enabling broad adoption across enterprise and hyperscale data center environments. Carrier (Emerging Leader) is strengthening its market position through the development of innovative and energy-efficient cooling solutions designed to support sustainable data center operations. While Schneider Electric benefits from established global scale and a broad technology portfolio, Carrier is expanding its presence and capabilities in sustainable cooling solutions, positioning it progressively closer to the leaders’ quadrant.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Schneider Electric (France)
- Vertiv (US)
- Eaton (Ireland)
- Daikin (Japan)
- ABB (Switzerland)
- Delta Electronics (Taiwan)
- Carrier (US)
- Siemens (Germany)
- GE Vernova (US)
- Stulz GmbH (Germany)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 48.26 Billion |
| Market Size in 2026 (Value) | USD 60.77 Billion |
| Market Forecast in 2031 (value) | USD 197.02 Billion |
| Growth Rate | CAGR of 26.5% from 2026 to 2031 |
| Years Considered | 2021–2031 |
| Base Year | 2025 |
| Forecast Period | 2026–2031 |
| Units Considered | Value (USD Million) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Regions Covered | North America, Europe, Asia Pacific, Middle East & Africa, Latin America |
WHAT IS IN IT FOR YOU: GREEN DATA CENTER MARKET REPORT CONTENT GUIDE
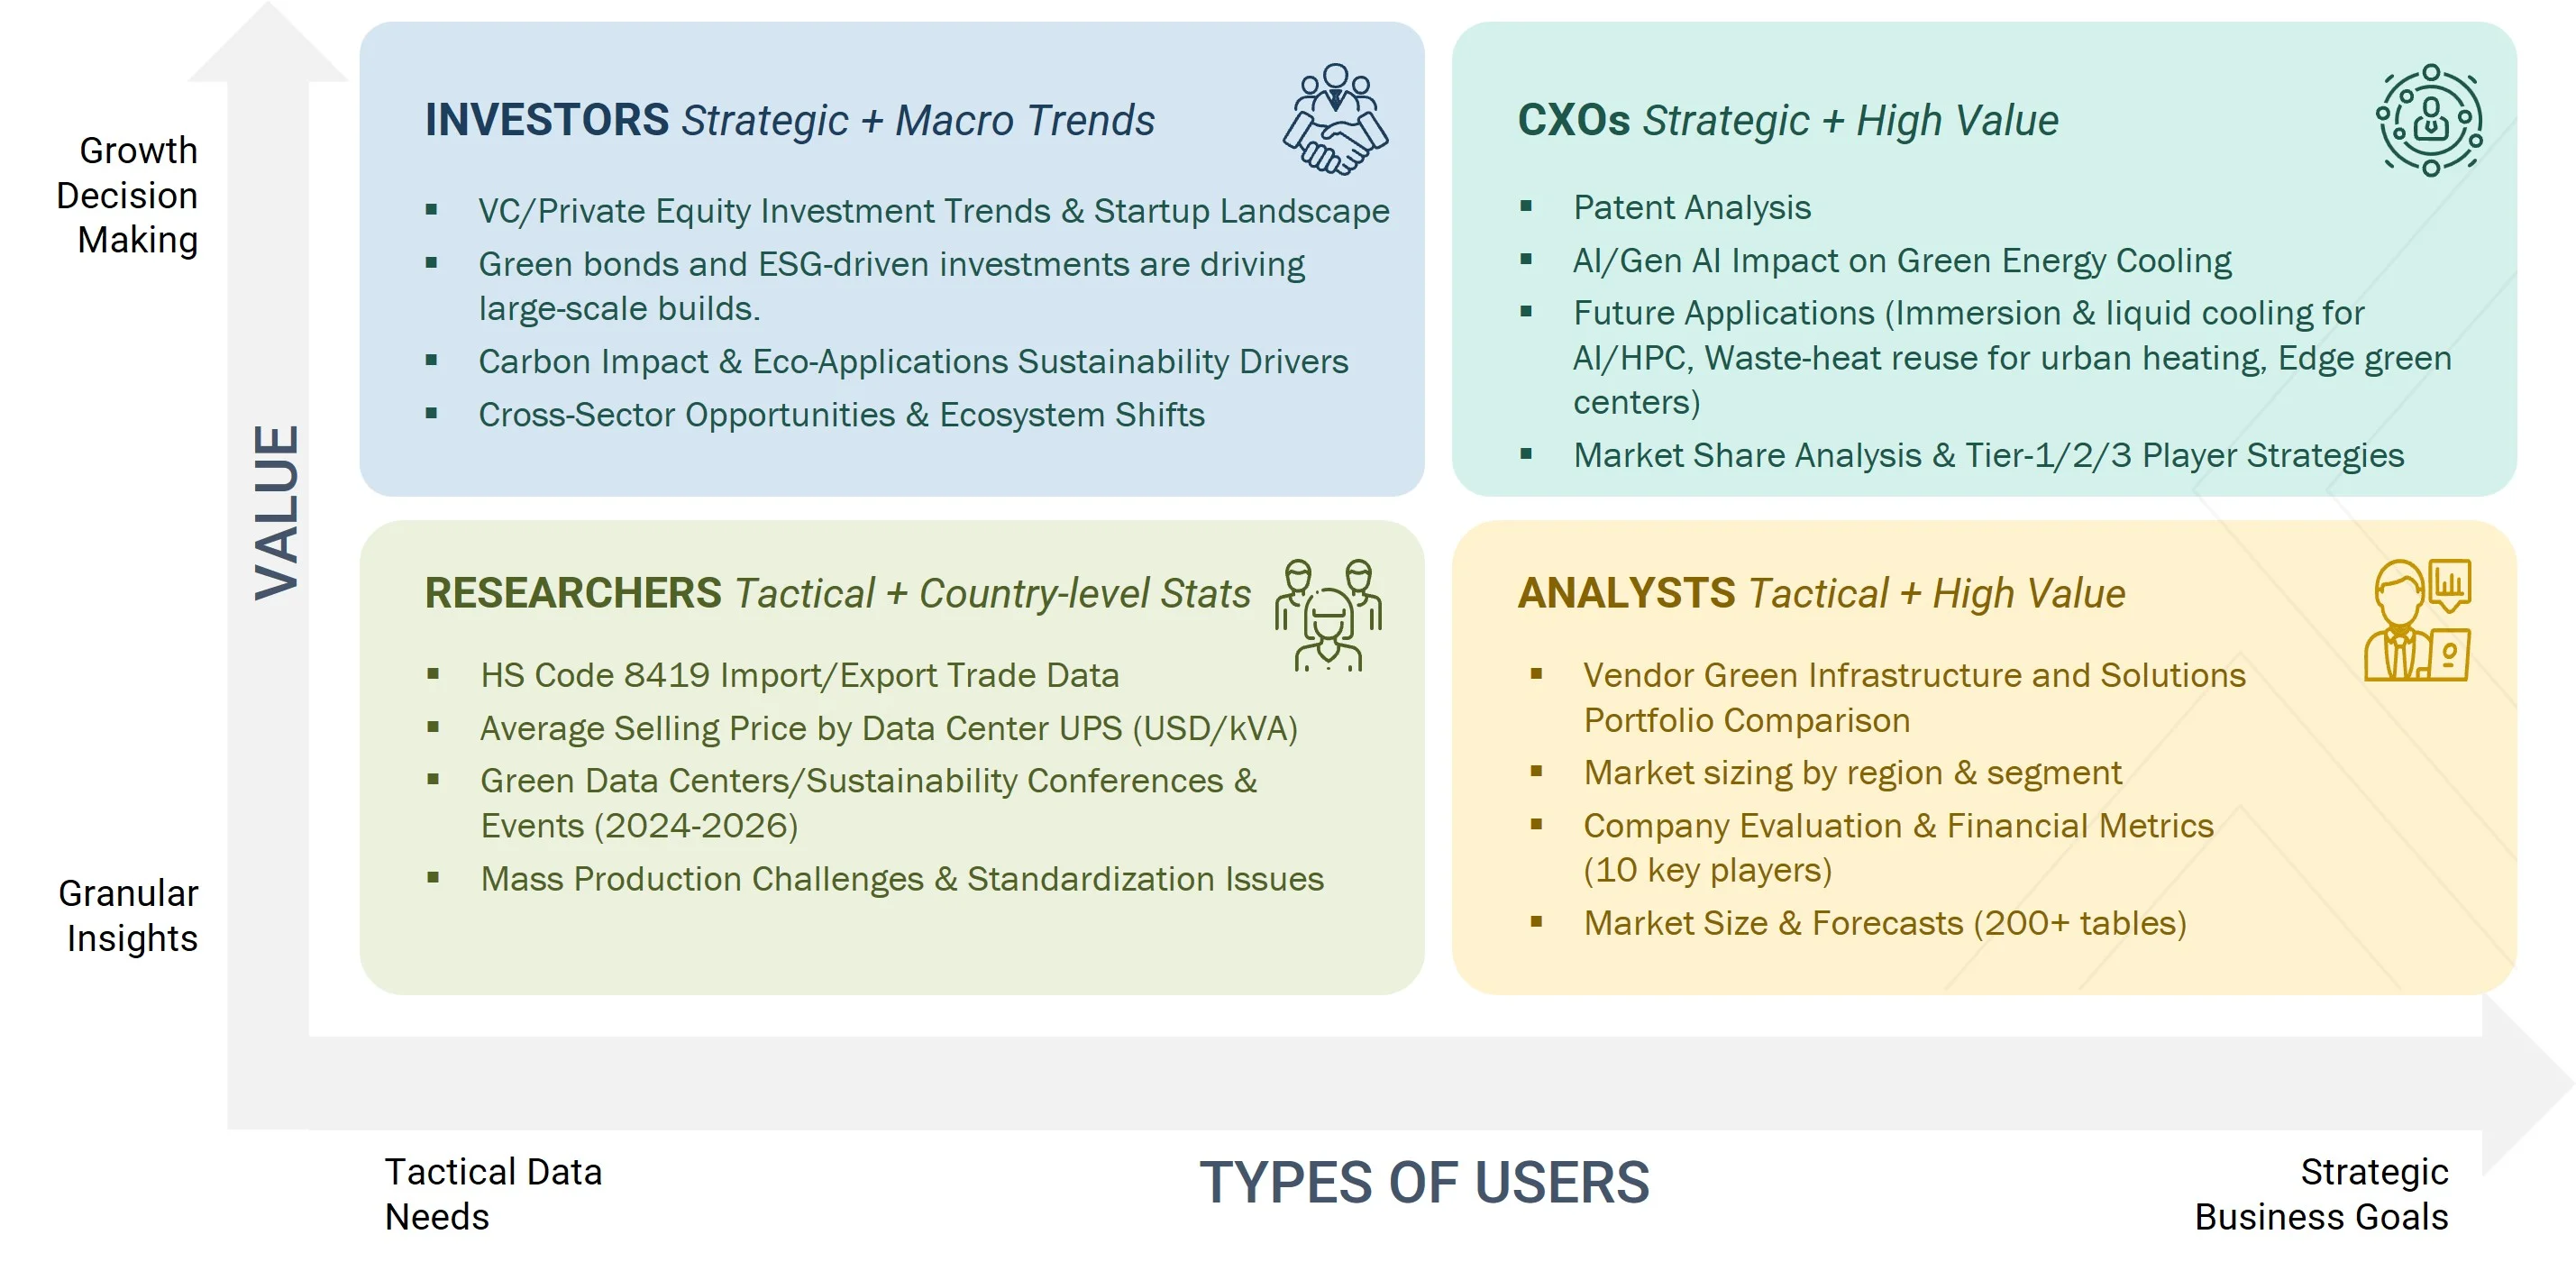
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Leading Solution Provider (US) | In-depth segmentation of the North American Green Data Center Market Extended regional breakdowns for: Europe, Asia Pacific, Middle East & Africa, Latin America |
|
| Leading Solution Provider (EU) | Detailed profiling of additional market players (up to five vendors), including product portfolios, strategic initiatives, and regional presence |
|
RECENT DEVELOPMENTS
- September 2026 : Vertiv agreed to acquire UIG for about USD 1.45 billion, with closing expected in Q4 2026. UIG added microgrid controls, on-site generation orchestration, and behind-the-meter power architecture. This would shorten time to power for data centers in power-constrained locations.
- March 2026 : Vertiv agreed to buy this Italian maker of heat rejection and heat exchange technologies. It expanded Vertiv's thermal portfolio and EMEA manufacturing for AI-ready, high-density data centers. Closing was expected in Q2 2026.
- November 2025 : Eaton announced the USD 9.5 billion purchase of Boyd's thermal business, which closed on 12 March 2026. It added liquid cooling and thermal components for data centers, and about 80% of Boyd's business serves that market.
- July 2025 : Daikin signed a five-year collaboration agreement with Greater Manchester to scale up low-carbon heating and support the city-region’s 2038 carbon neutrality goal. The partnership included installing low-carbon heating systems, developing green skills, conducting community outreach, and deploying innovative heat pump technologies to advance sustainable energy solutions.
- June 2025 : Oklo and Vertiv partnered to co-develop advanced power and thermal management solutions for US hyperscale and colocation data centers. The partnership leveraged Oklo’s advanced nuclear power plants and Vertiv’s cooling and power systems to enhance energy efficiency, provide resilient AI and high-performance computing power, and produce end-to-end reference designs for integrated, sustainable data center operations.
- June 2025 : At GTC Paris 2025, Schneider Electric and NVIDIA released co-developed infrastructure for European AI factories, integrating OCP racks, EcoStruxure Pods, and advanced liquid cooling for high-density AI clusters. Leveraging their expertise in AI-ready infrastructure, grid coordination, and sustainability, Schneider Electric and NVIDIA would jointly respond to the European Commission's "AI Continent Action Plan," which set out a shared mission to establish a minimum of 13 AI factories across Europe while founding up to five AI gigafactories.
- June 2025 : Eaton partnered with Siemens Energy to accelerate AI data center construction through integrated on-site power systems and modular infrastructure. The collaboration included medium- and low-voltage switchgear, UPS systems, busways, IT racks, and scalable 500 MW power plants with gas turbines, battery storage, and clean-air grid connections. The joint approach would reduce CO2 emissions, eliminate diesel backup, and enable rapid deployment of high-availability, AI-ready data centers.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
This research study involved the use of extensive secondary sources, directories, and databases, such as D&B Hoovers, Bloomberg Businessweek, and Factiva, to identify and collect information for a technical, market-oriented, and commercial study of the green data center market. Additionally, a few other market-related reports and analyses published by various industry associations and consortia, such as the National Security Agency (NSA) and SC Magazine, were considered while conducting extensive secondary research.
Secondary Research
The market size of companies offering green data centers was determined based on secondary data available through paid and unpaid sources, analyzing the product portfolios of major companies in the ecosystem, and rating the companies based on their product capabilities and business strategies. Various sources were referred to in the secondary research process to identify and collect information for the study. The secondary sources included annual reports, press releases, investor presentations of companies, product data sheets, white papers, journals, certified publications, and articles from recognized authors, government websites, directories, and databases.
Primary Research
In the primary research process, various primary sources from the supply and demand sides were interviewed to obtain qualitative and quantitative information for this report. The primary sources from the supply side included industry experts, such as chief executive officers (CEOs), vice presidents (VPs), marketing directors, technology and innovation directors, and related key executives from various key companies and organizations operating in the green data center market.
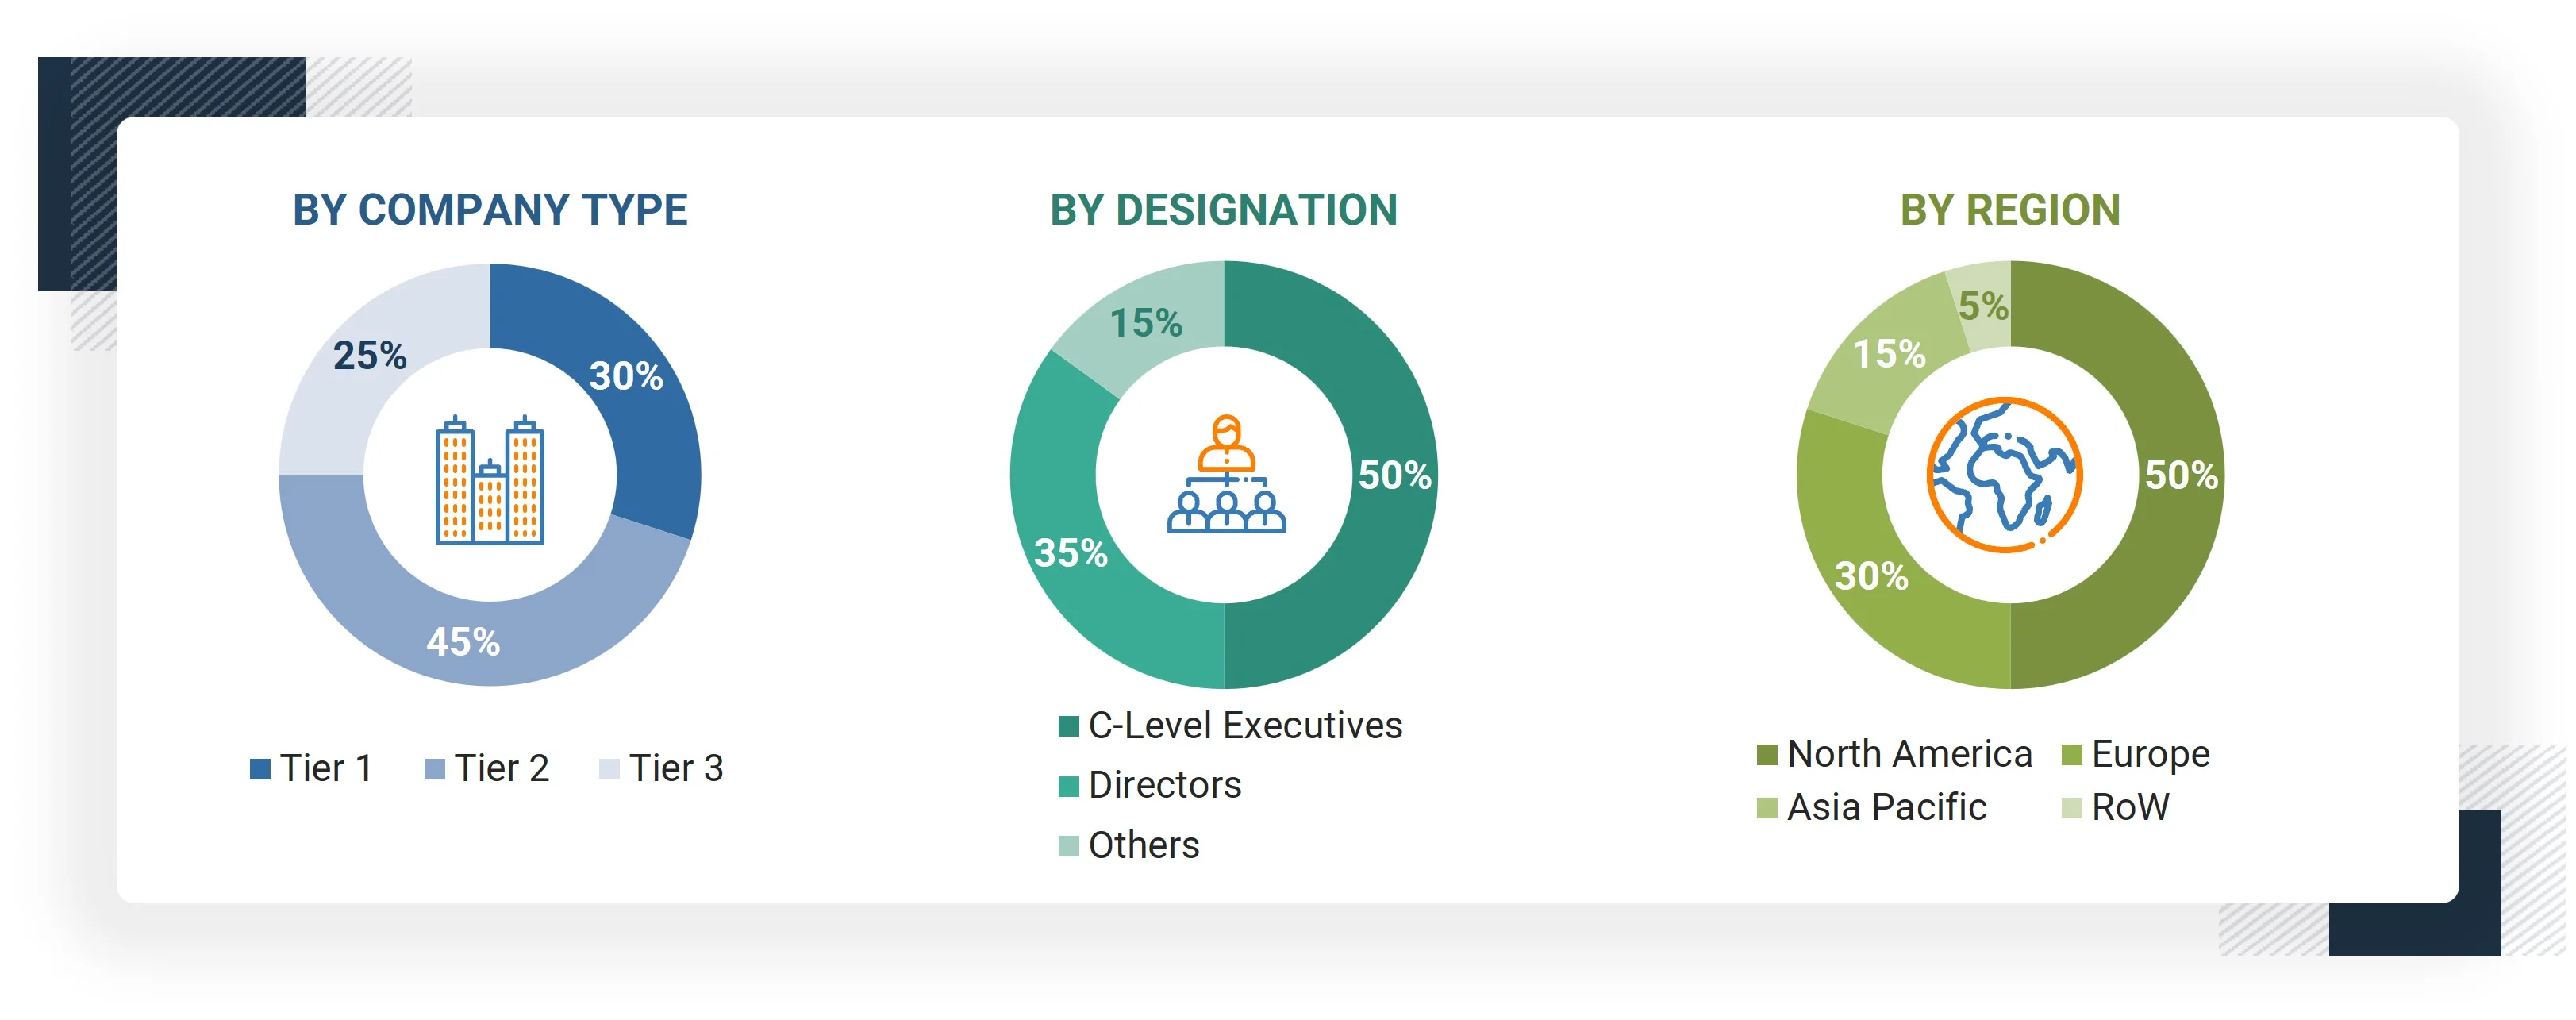
Note: Tier 1 companies’ revenues are more than USD 10 billion; tier 2 companies’ revenues range between USD 1 and 10 billion; and tier 3 companies’ revenues range between USD 500 million and USD 1 billion. Other designations include sales managers, marketing managers, and product managers.
Source: Industry Experts
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
Multiple approaches were adopted to estimate and forecast the green data center market. The first approach involved estimating the market size by companies’ revenue generated through the sale of green data center products.
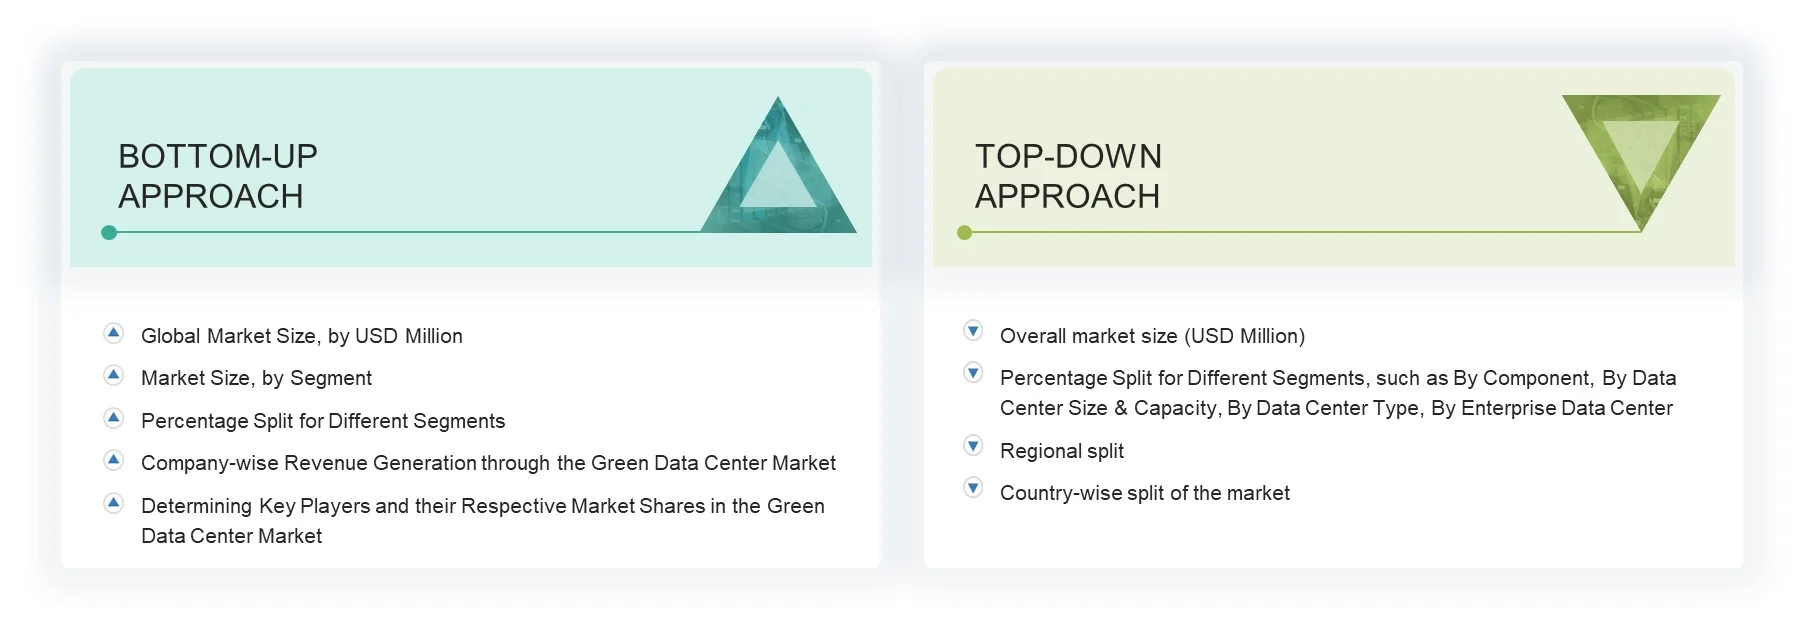
Market Size Estimation Methodology: Top-down Approach
The top-down methodology compiled a comprehensive database of all suppliers active within the green data center market. Revenue generation for these key industry players was assessed by analyzing annual financial statements, official press releases, capital investments, investor decks, premium market databases, and expert interviews. Every supplier's product portfolio was analyzed across parameters including architecture, level of tailorability, solution type, deployment scenario, vertical end user, and geographic location. Market estimates were cross-verified using a combination of primary and secondary intelligence gathering. The primary research phase involved detailed discussions to gather strategic perspectives from executive stakeholders, such as CIOs, CEOs, VPs, division heads, and commercial leads. Finally, the calculated market figures were cross-referenced against historical industry repositories for rigorous validation.
Market Size Estimation Methodology: Bottom-up Approach
The bottom-up methodology determined the deployment rate of green data center solutions across diverse industry verticals in major countries, accounting for regions that drive the majority of market share. To ensure cross-validation, the integration of eco-friendly data center infrastructure across enterprises and application scenarios within these regions was mapped and projected. Specific implementation cases across geographies were weighted to calculate total market valuation.
Driven by these market figures, geographic distribution was established using primary and secondary research insights. This framework incorporated an evaluation of regional market penetration for eco-friendly data centers. Through extensive secondary research, regional investments in Information and Communications Technology (ICT), national socioeconomic parameters, competitive vendor evaluation of key green data center providers, alongside organic and inorganic expansion strategies of global and regional stakeholders were quantified.
Data Triangulation
After determining the overall market size using the market size estimation processes as explained above, the market was split into several segments and subsegments. Data triangulation and market breakup procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment. The overall market size was then used in the top-down procedure to estimate the size of other individual markets via percentage splits of the market segmentation.
Market Definition
Synthesizing perspectives from industry bodies and trade experts, MarketsandMarkets characterizes a green data center as a comprehensive ecosystem of power, thermal management, management software, and professional services tailored to drive sustainable, energy-efficient operations across data center environments. The power architecture encompasses green generation technologies, auxiliary energy storage, backup generators, and eco-friendly power distribution units, while thermal solutions feature advanced eco-air cooling and liquid cooling mechanisms. The software stack covers Data Center Infrastructure Management (DCIM), facility control systems, regulatory compliance monitoring, and related platforms. Supporting services incorporate sustainability consulting, energy assessment, green system integration, deployment, as well as ongoing eco-friendly maintenance. These technologies are integrated within hyperscale, colocation, and corporate facility environments to handle diverse compute workloads based on operational capacity.
According to IBM, a green data center—or eco-sustainable data center—denotes an operational facility built on highly efficient infrastructure that leverages clean technologies to optimize power consumption and minimize ecological footprints. Key evaluation metrics for sustainable data centers include facility footprint minimization, advanced thermal management efficiency, waste heat utilization, adoption of clean power alternatives, among other sustainability drivers.
Key Stakeholders
- Infrastructure & Equipment Vendors
- Software Solution Providers (DCIM, Energy Management, Compliance)
- Colocation Service Providers
- Hyperscale Cloud Providers
- Enterprises
- Renewable Energy Providers (Solar, Wind, Fuel Cells, etc.)
- Regulatory Bodies & Standards Organizations (ASHRAE, Uptime Institute, ISO, etc.)
- Consulting & Advisory Firms (Sustainability, Energy Audits, Certifications)
- Construction, Engineering & Real Estate Firms
- Investors and Real Estate Investment Trusts (REITs)
- System Integrators (SIs)
- Industry Alliances and Advocacy Groups
Report Objectives
- To define, describe, and forecast the green data center market based on component, data center size & capacity, data center type, and region
- To forecast the market size of the five major regional segments: North America, Europe, Asia Pacific, Middle East & Africa, and Latin America
- To strategically analyze the market subsegments concerning individual growth trends, prospects, and contributions to the total market
- To provide detailed information related to the major factors influencing market growth (drivers, restraints, opportunities, and challenges)
- To strategically analyze macro and micro markets1 with respect to growth trends, prospects, and their contribution to the overall market
- To analyze industry trends, patents and innovations, and pricing data related to the market
- To analyze the opportunities in the market for stakeholders and provide details of the competitive landscape for major players
- To profile key players in the market and comprehensively analyze their market share/ranking and core competencies2
- To track and analyze competitive developments, such as mergers & acquisitions, product developments, and partnerships & collaborations in the market
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per the company’s specific needs. The following customization options are available for the report:
Product Analysis
- The product matrix provides a detailed comparison of the product portfolio of each company.y
Geographic Analysis based on feasibility
- Further breakup of the North American green data center market
- Further breakup of the European green data center market
- Further breakup of the Asia Pacific green data center market
- Further breakup of the Middle East & Africa green data center market
- Further breakup of the Latin American green data center market
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Key Questions Addressed by the Report
What is the projected growth of the Green Data Center Market from 2026 to 2031?
The global Green Data Center Market is projected to grow from USD 60.77 billion in 2026 to USD 197.02 billion by 2031, registering a CAGR of 26.5% during the forecast period. This growth reflects increasing investments in energy-efficient data center infrastructure, sustainable computing, renewable energy integration, and technologies that reduce operational costs and carbon emissions.
What are the key factors driving the growth of the Green Data Center Market?
The Green Data Center Market is driven by rising energy consumption from AI workloads, increasing electricity costs, stringent environmental regulations, and corporate net-zero commitments. Growing adoption of renewable energy, energy-efficient cooling systems, optimized power management, and sustainable IT infrastructure is encouraging enterprises and data center operators to reduce carbon footprints while improving operational efficiency.
Which region is expected to grow fastest in the Green Data Center Market?
Asia Pacific is expected to register the highest growth rate in the Green Data Center Market, supported by expanding digital infrastructure, rising data center investments, renewable energy adoption, and government sustainability initiatives. Countries such as China, Japan, and India are creating opportunities for green data center solutions as demand for cloud computing and AI infrastructure increases.
Which segment is expected to grow fastest in the Green Data Center Market?
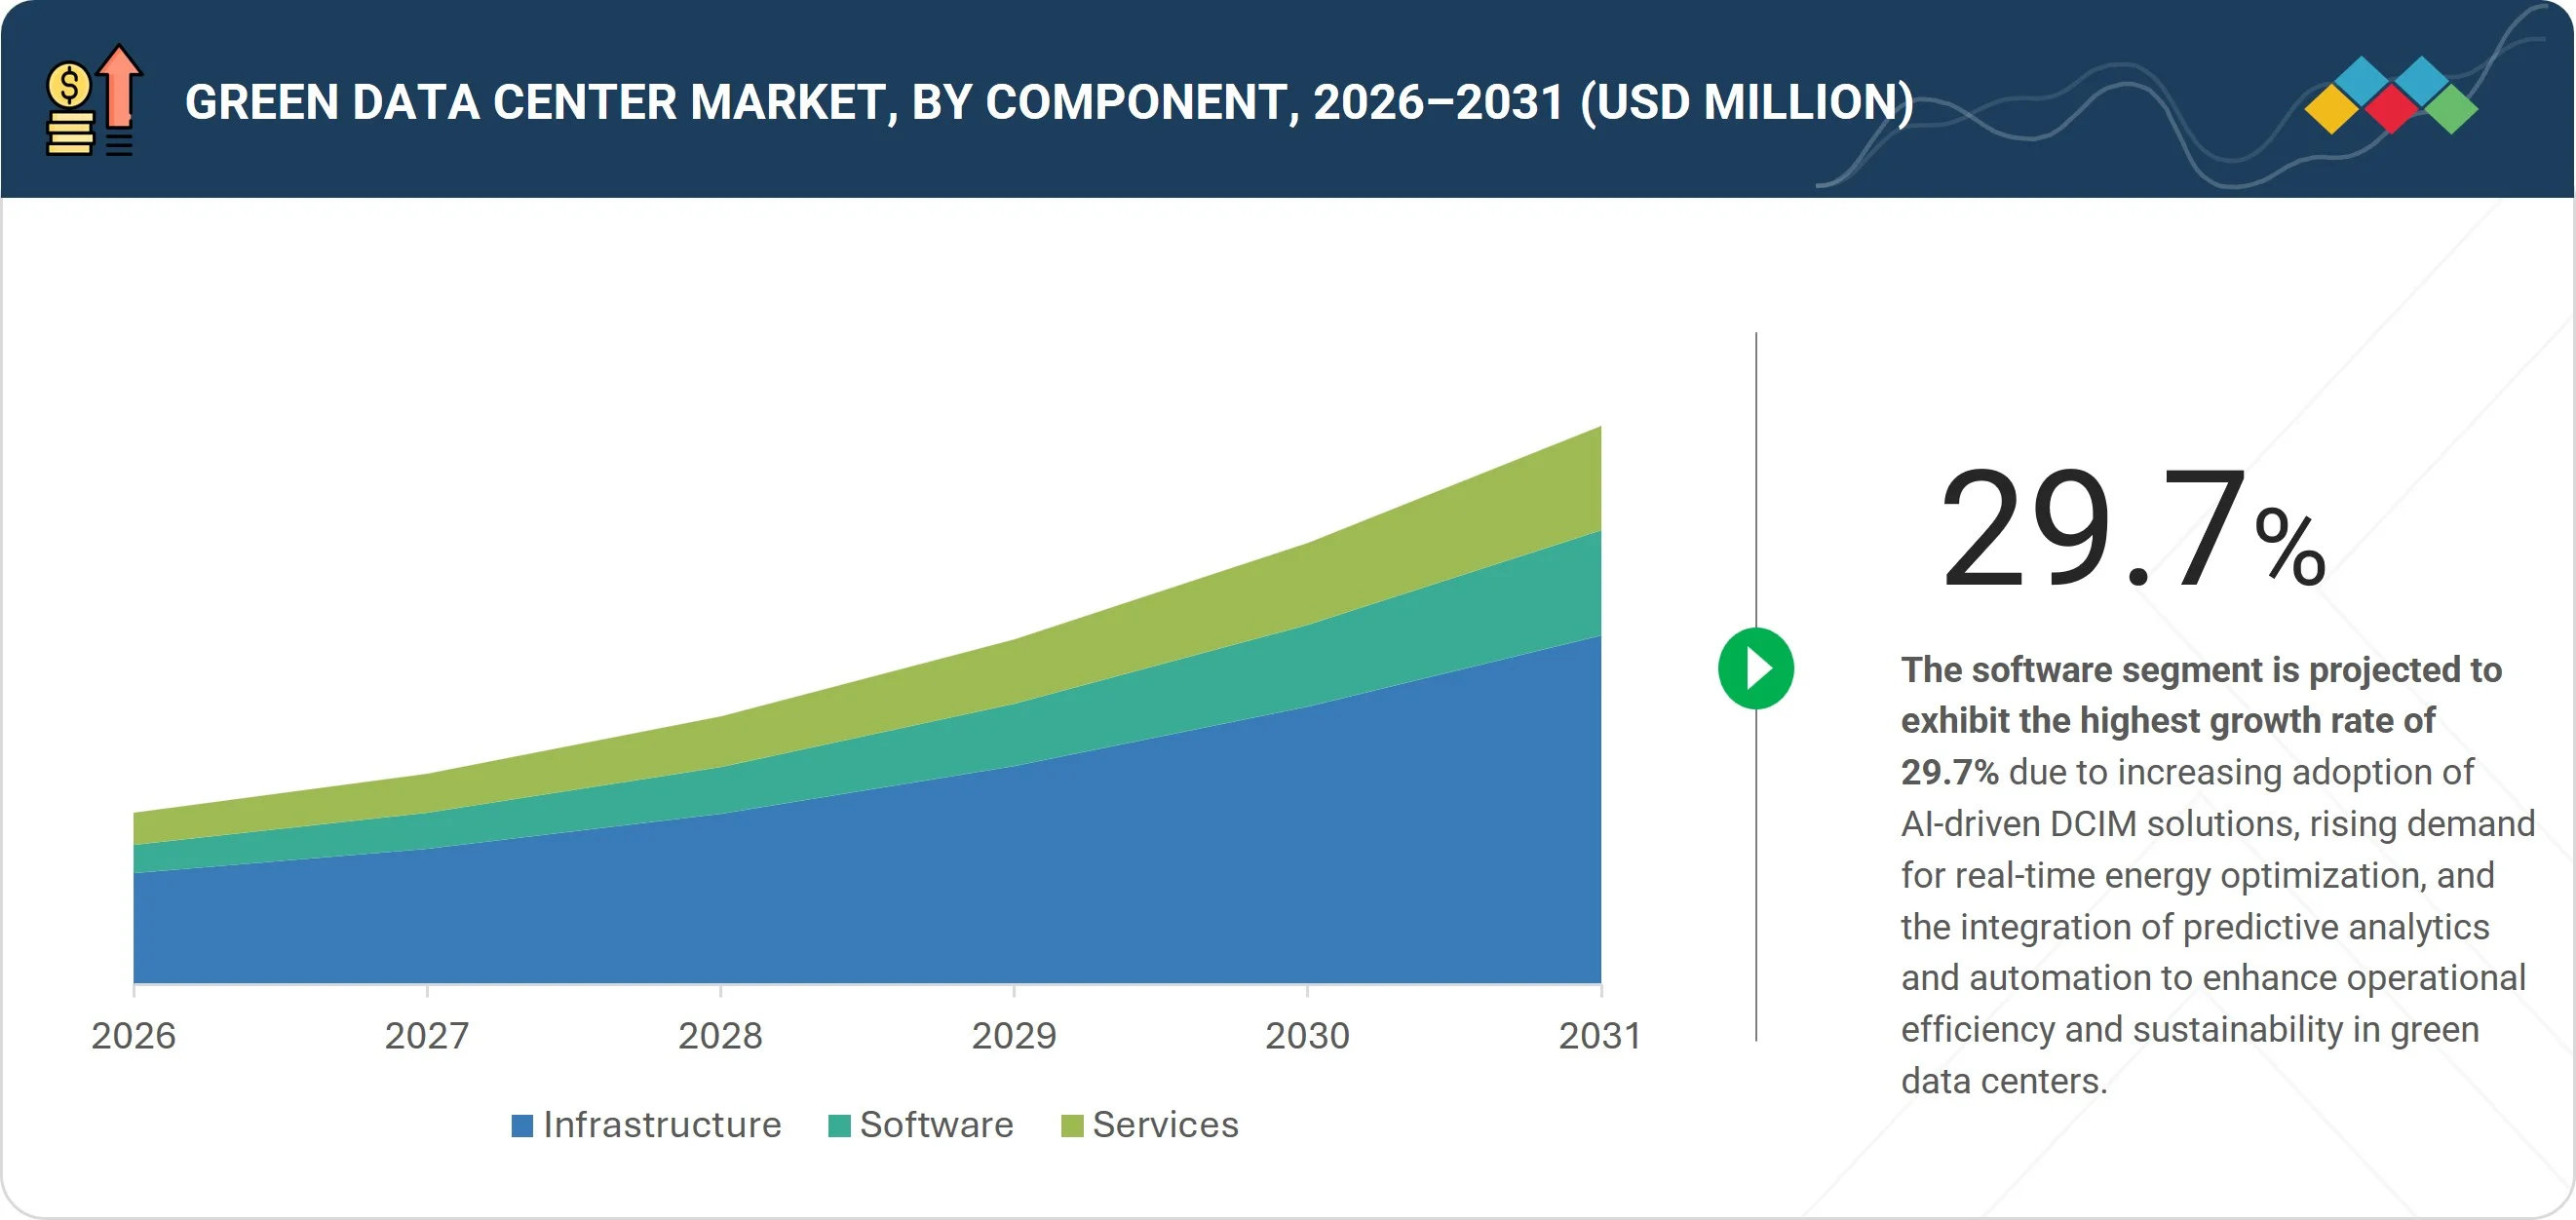
The software segment of the Green Data Center Market is projected to grow at the highest CAGR of 29.7% from 2026 to 2031. Growth is supported by increasing adoption of AI-driven energy optimization, data center infrastructure management (DCIM), building management systems, and sustainability monitoring tools that help operators improve energy efficiency and track environmental performance.
What are the major growth opportunities in the Green Data Center Market?
Major growth opportunities in the Green Data Center Market include prefabricated green data center modules, waste heat recovery systems, circular IT asset management, and sustainability certification solutions. These approaches help organizations reduce resource consumption, improve infrastructure efficiency, and meet environmental targets. Growing demand for sustainable AI and cloud infrastructure is also creating opportunities for technology providers.
Which technologies are shaping the future of the Green Data Center Market?
Key technologies shaping the Green Data Center Market include liquid cooling, energy-efficient air cooling, renewable energy integration, AI-powered energy management software, predictive cooling systems, and advanced power management solutions. These technologies help data center operators optimize power usage, manage increasing computing workloads, reduce heat-related energy consumption, and lower carbon emissions while supporting scalable digital infrastructure.


Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Green Data Center Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
- Canada Green Data Center Market
- US Green Data Center Market
- UK Green Data Center Market
- Germany Green Data Center Market
- France Green Data Center Market
- Italy Green Data Center Market
- China Green Data Center Market
- Japan Green Data Center Market
- India Green Data Center Market
- Saudi Arabia Green Data Center Market
- UAE Green Data Center Market
- South Africa Green Data Center Market
- Brazil Green Data Center Market
- Mexico Green Data Center Market
- Rest Of Europe Green Data Center Market
- Rest Of Asia Pacific Green Data Center Market
- Rest Of Latin America Green Data Center Market
- GCC Countries Green Data Center Market
- Rest Of GCC Countries Green Data Center Market






Growth opportunities and latent adjacency in Green Data Center Market