Rest Of Europe Anatomic Pathology Market (2026-2031)
The Rest Of Europe Anatomic Pathology Market was valued at $340.4 Million in 2026 and projected to reach to $568.4 Million by 2031, representing a compound annual growth rate of 10.8%. Rest Of Europe's anatomic pathology market is positioned for sustained growth through 2031, driven by demographic pressures, healthcare modernization initiatives, and increased investment in diagnostic infrastructure.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Rest Of Europe Anatomic Pathology Market Trends and Insights
- This expansion reflects increasing demand for advanced diagnostic services across the region, driven by aging populations and rising prevalence of chronic diseases.
- Rest Of Europe is witnessing significant investment in laboratory infrastructure and digital pathology adoption, positioning the region as a key growth market within the broader European healthcare landscape. The anatomic pathology sector in Rest Of Europe is benefiting from regulatory harmonization efforts and cross-border collaboration initiatives that enhance service delivery standards.
- Rest Of Europe's market growth outpaces the global average, indicating strong regional momentum in histopathology, cytopathology, and immunohistochemistry services.
- Between 2026 and 2031, Rest Of Europe is expected to capture increasing market share through technological innovation and improved access to specialized diagnostic capabilities..
Key Market Statistics
- CAGR (2026-2031) 10.8% CAGR
- Market Size, 2026 ~USD 340.4 Million
- Forecast, 2031 ~USD 568.4 Million
- Country Rest Of Europe
Rest Of Europe Anatomic Pathology Market Overview
Strong Regional Growth Trajectory :
Rest Of Europe's anatomic pathology market is expanding at a CAGR of 10.8%, outpacing the global average of 10.2%, demonstrating the region's accelerating adoption of advanced diagnostic pathology services.
Aging Population Driving Demand :
Demographic shifts across Rest Of Europe, characterized by an aging population, are significantly increasing the prevalence of chronic diseases and cancer diagnoses, thereby elevating demand for anatomic pathology services.
Laboratory Infrastructure Investment :
Rest Of Europe is witnessing substantial capital investment in laboratory infrastructure modernization, including digital pathology adoption and automation technologies to enhance diagnostic capabilities and efficiency.
Market Valuation Growth :
The market is projected to grow from $340.4 million in 2026 to $568.4 million by 2031, representing a 67% increase over the five-year forecast period, indicating strong market expansion opportunities.
Rest Of Europe Anatomic Pathology Market Dynamics
- The region's aging population and rising chronic disease burden are creating consistent demand for advanced pathology services, while healthcare systems are prioritizing laboratory upgrades to improve diagnostic accuracy and turnaround times. Key growth catalysts include the adoption of digital pathology platforms, integration of artificial intelligence in diagnostic workflows, and expanding healthcare expenditures across the region.
- Healthcare providers and laboratory operators in Rest Of Europe are increasingly recognizing the value of anatomic pathology in precision medicine and early disease detection, positioning the market for continued expansion beyond 2031..
Market Ecosystem
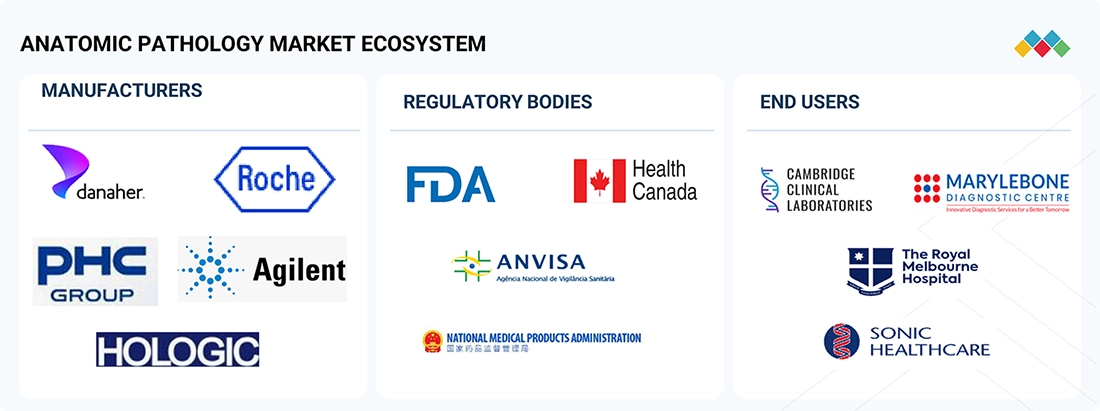
ANATOMIC PATHOLOGY MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Offers comprehensive anatomic pathology solutions through tissue processors, microtomes, staining systems, digital pathology scanners, and workflow automation platforms used for histopathology, immunohistochemistry (IHC), and cancer diagnostics. | Improves laboratory efficiency, enhances diagnostic accuracy, supports workflow standardization, and enables high-throughput pathology operations. |
 |
Provides tissue diagnostics solutions through its portfolio, including automated IHC and ISH staining systems, digital pathology platforms, image analysis software, and biomarker testing solutions for cancer diagnosis and tissue characterization. | Enables precise tissue analysis, supports personalized treatment decisions, improves pathology workflow productivity, and enhances diagnostic confidence. |
 |
Offers a broad portfolio of histology and cytology products, including tissue processors, microtomes, cryostats, slide printers, staining systems, and pathology workflow solutions for specimen preparation and analysis. | Enhances specimen traceability, improves laboratory productivity, streamlines tissue preparation workflows, and supports consistent diagnostic outcomes. |
 |
Provides anatomic pathology consumables and instruments, including antibodies, reagents, automated staining platforms, IHC and ISH solutions, and biomarker testing products used in cancer diagnostics and pathology laboratories. | Delivers high-quality staining performance, supports biomarker analysis, improves laboratory efficiency, and enables accurate tissue-based diagnosis. |
 |
Offers cytopathology and digital diagnostics solutions, including ThinPrep sample preparation systems and Genius Digital Diagnostics platforms for cervical cancer screening and cytology testing workflows. | Improves screening efficiency, enhances diagnostic accuracy, supports automated review processes, and increases laboratory throughput. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
In Vitro Diagnostics
- Polymerase Chain Reaction (PCR)
- Enzyme-Linked Immunosorbent Assay (ELISA)
- Dna Microarrays
- Assay Kits
- Microarrays
- ROCHE HOLDINGS AG
- Thermo Fisher Scientific Inc.
- Danaher Corporation
- Abbott Laboratories
- Biomerieux s.a.
Key Takeaways
- Rest Of Europe's anatomic pathology market will grow from $340.4M (2026) to $568.4M (2031), representing a 10.8% CAGR.
- Rest Of Europe is experiencing above-global-average growth, driven by aging demographics and increased chronic disease prevalence.
- Rest Of Europe is investing heavily in digital pathology and laboratory automation to enhance diagnostic efficiency.
- Rest Of Europe's market expansion is supported by regulatory harmonization and improved cross-border healthcare collaboration.
Anatomic Pathology Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | DIGITAL PATHOLOGY (Process) |
| Forecast Period | 2026-2031 |
| Growth Rate | CAGR of 10.2% from 2026 to 2031 |
| Largest Segment | IN-HOUSE (Model) |
| Market Size Base Year (Billions) | ~USD 8.92 (2026) |
| Revenue Forecast (Billions) | ~USD 14.5 (2031) |
| Segments Covered | Type, Process, Disease, End User, Model |
Rest Of Europe Anatomic Pathology Market Report Segmentation
5 segment dimensions are covered across the global market.
By Type
- AI-Integrated Software
- Cell Processors
- Consumables
- Coverslippers
- Cytopathology Antibodies
- Cytopathology Consumables
- Cytopathology Fixatives
- Cytopathology Kits & Reagents
- Cytopathology Probes
- Cytopathology Services
- Cytopathology Stains & Solvents
- Digital Pathology Scanner
- Digital Pathology Scanners
- Embedding Systems
- Histopathology Antibodies
- Histopathology Consumables
- Histopathology Fixatives
- Histopathology Kits & Reagents
- Histopathology Probes
- Histopathology Services
- Histopathology Stains & Solvents
- Instruments
- Microtomes
- Non-AI-Integrated Software
- Other Cytopathology Consumables
- Other Cytopathology Kits & Reagents
- Other Histopathology Consumables
- Other Histopathology Kits & Reagents
- Other Instruments
- Primary Cytopathology Antibodies
- Primary Histopathology Antibodies
- Secondary Cytopathology Antibodies
- Secondary Histopathology Antibodies
- Slide Staining Systems
- Software
- Storage Systems
- Tissue Processing Systems
By Process
- Advanced Staining/Ihc
- Digital Pathology
- Preanalytics/Sample Preparation
- Primary & Special Staining
By Disease
- Breast Cancer
- Gastric Cancer
- Lymphoma
- Non-Small-Cell Lung Cancer
- Other Diseases
- Prostate Cancer
By End User
- Contract Research Organizations
- Hospitals
- Other End Users
- Pharmaceutical Companies
- Research Laboratories
By Model
- In-House
- Outsourced
Target Audience
- Diagnostic Equipment Manufacturers : Manufacturers need Rest Of Europe-specific market data to identify growth opportunities, assess regional demand for pathology equipment, and develop localized product strategies for laboratory modernization initiatives.
- Laboratory Service Providers : Laboratory operators require detailed market insights to benchmark performance, identify expansion opportunities, and understand competitive positioning within Rest Of Europe's growing anatomic pathology sector.
- Healthcare Investment Firms : Private equity and healthcare investors need comprehensive Rest Of Europe market analysis to evaluate investment opportunities, assess market growth potential, and identify acquisition targets in the pathology sector.
- Digital Pathology Solution Vendors : Software and technology providers require region-specific adoption trends and market forecasts to prioritize Rest Of Europe expansion, tailor solutions to local needs, and project revenue potential.
- Healthcare Policy & Regulatory Bodies : Government agencies and healthcare authorities need market intelligence to inform policy decisions, allocate healthcare resources, and understand diagnostic service capacity requirements across Rest Of Europe.
Reasons to Buy this Report
- Regional Market Sizing & Forecasts : Obtain precise market valuations specific to Rest Of Europe ($340.4M in 2026, $568.4M in 2031) with detailed CAGR analysis to support strategic planning and investment decisions in the region.
- Competitive Landscape Intelligence : Understand the competitive dynamics, key players, and market positioning strategies unique to Rest Of Europe's anatomic pathology sector to identify partnership and expansion opportunities.
- Growth Driver Analysis : Gain insights into region-specific growth catalysts including aging demographics, healthcare infrastructure investments, and regulatory developments driving anatomic pathology adoption across Rest Of Europe.
- Technology Adoption Trends : Access detailed analysis of digital pathology, AI integration, and laboratory automation adoption rates specific to Rest Of Europe, enabling informed technology investment decisions.
- Strategic Market Entry Planning : Leverage Rest Of Europe-specific market data to develop targeted go-to-market strategies, identify high-potential countries, and optimize resource allocation for market penetration.
Frequently asked questions
What is the current size of the anatomic pathology market in Rest Of Europe?
Rest Of Europe's anatomic pathology market is valued at $340.4 million in 2026 and is projected to reach $568.4 million by 2031.
What is the expected growth rate for Rest Of Europe's anatomic pathology market?
Rest Of Europe's anatomic pathology market is expected to grow at a compound annual growth rate (CAGR) of 10.8% from 2026 to 2031.
What factors are driving growth in Rest Of Europe's anatomic pathology market?
Rest Of Europe's market growth is driven by aging populations, rising chronic disease prevalence, digital pathology adoption, laboratory infrastructure investment, and regulatory harmonization across the region.
How does Rest Of Europe's market growth compare to global trends?
Rest Of Europe's anatomic pathology market is growing at 10.8% CAGR, which exceeds the global average of 10.2%, indicating stronger regional momentum and market opportunity.
What technological trends are shaping Rest Of Europe's anatomic pathology market?
Rest Of Europe is experiencing increased adoption of digital pathology, laboratory automation, immunohistochemistry advances, and AI-enabled diagnostic tools that enhance efficiency and accuracy in anatomic pathology services.
RESEARCH METHODOLOGY
The objective of this study is to analyze the key dynamics influencing the anatomic pathology market, including drivers, restraints, opportunities, challenges, and emerging technology trends. The study also evaluates competitive developments such as product launches, regulatory approvals, acquisitions, partnerships, collaborations, and geographic expansions undertaken by leading market participants. Furthermore, it assesses the competitive landscape of the anatomic pathology market by profiling key players and benchmarking them across various business and product strategy parameters. Both top-down and bottom-up approaches were employed to estimate the overall market size, while market breakdown and data triangulation methodologies were used to validate the size of individual segments and subsegments and ensure the accuracy of market estimates.
The four steps involved in estimating the market size are as follows:
Secondary Research
Secondary research for the anatomic pathology market drew on a wide range of credible commercial and regulatory sources, including Bloomberg Business, Factiva, and Dun & Bradstreet for corporate financial and operational data. White papers, scientific publications, annual reports, investor presentations, and SEC filings provided additional context on product pipelines, revenue structures, and market positioning. Regulatory databases were used to track device clearances and approvals in key geographies.
Primary Research
In the primary research process, various sources from both the supply and demand sides were interviewed to obtain qualitative and quantitative information for this report. Supply-side primary interviews were conducted with project managers, product managers, sales directors, vice presidents of diagnostics, CEOs, and business development directors at manufacturers of anatomic pathology products, as well as reagent kit suppliers, laboratory automation vendors, and IVD distributors. Demand-side primary interviews covered laboratory directors and clinical pathologists at hospital and reference laboratories, research laboratory managers, health clinic directors, academic research scientists, and procurement officers at pharmaceutical and biotechnology companies.
The following is a breakdown of the primary respondents:
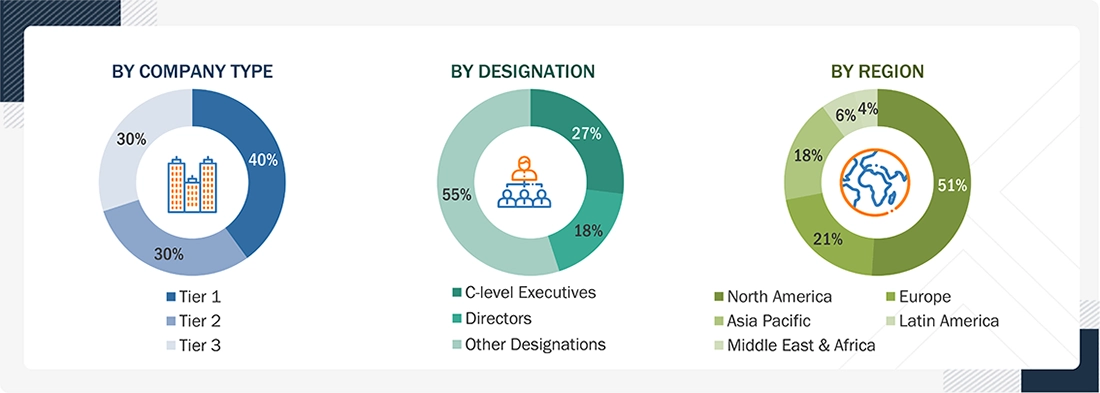
Note: Others include sales, marketing, and product managers.
Companies are classified into tiers based on their total revenues. As of 2025, Tier 1 = >USD 100 million, Tier 2 = USD 10 million to USD 100 million, and Tier 3 = <USD 10 million.
|
COMPANY NAME |
DESIGNATION |
|
Danaher Corporation (US) |
Sales Manager |
|
F. Hoffmann-La Roche AG (Switzerland) |
Product Manager |
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
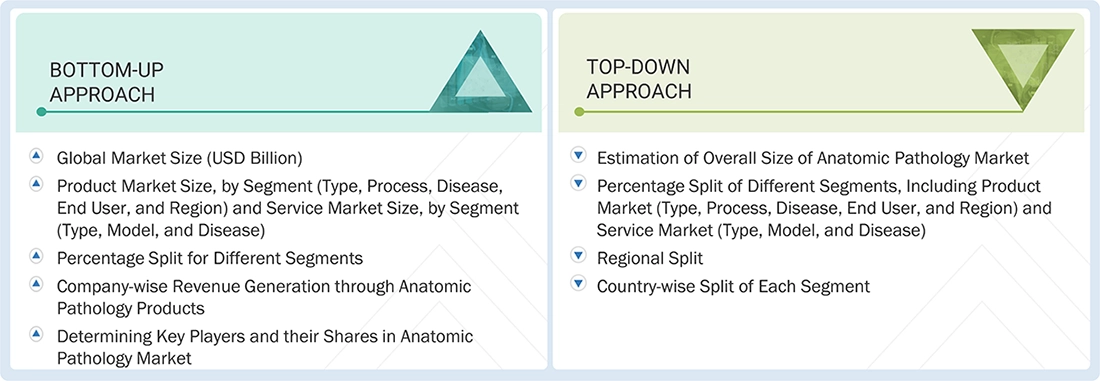
Both top-down and bottom-up approaches were used to estimate and validate the anatomic pathology market’s total size. These methods were also used extensively to estimate the size of various subsegments in the market. The research methodology used to estimate the market size includes the following:
- The key players in the industry have been identified through extensive secondary research
- The revenues generated by leading players operating in the anatomic pathology market were determined through primary and secondary research.
- All percentage shares, splits, and breakdowns have been determined using secondary sources and verified through primary sources.
Anatomic Pathology Market : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size by applying the process mentioned above, the total market was split into several segments and subsegments. The data triangulation and market breakdown procedures were employed to validate and complete the overall market engineering process and arrive at the exact statistics for all segments and subsegments of the anatomic pathology market. The data was triangulated by studying various factors and trends from the demand and supply sides in the anatomic pathology market.
Market Definition
Anatomic pathology is a subspeciality of pathology that focuses on the diagnosis and characterization of diseases through the examination of organs, tissues, cells, and bodily fluids obtained from patients through biopsies, surgical procedures, and other sampling methods. Anatomic pathology testing (APT) encompasses the range of diagnostic technologies, products, and services used within this field, including histopathology, cytopathology, digital pathology and amongst others. These techniques play a critical role in the detection, classification, prognosis, and monitoring of cancer, infectious diseases, and other medical conditions, supporting clinical decision-making and personalized treatment strategies.
Key Stakeholders
- Product Manufacturers, Distributors, and Suppliers
- Diagnostic Laboratories and Clinical Laboratories
- Research Laboratories and CROs
- Academic Universities and Medical Research Centers
- Research and Development (R&D) Centers
- Pharmaceutical and Biotechnology Companies
- Anatomic Pathology Companies
- Market Research and Consulting Firms
- Government Associations
Report Objectives
- To define, describe, and forecast the anatomic pathology product market (type, process, disease, end user, and region), Service market (type, model, disease)
- To provide detailed information about the key factors influencing the growth of the Anatomic Pathology Market (drivers, restraints, opportunities, and challenges)
- To analyze the micromarkets with respect to individual growth trends, prospects, and contributions to the overall market
- To analyze market opportunities for stakeholders and provide the competitive landscape details of the key players
- To forecast the revenue of market segments across five main regions: North America, Europe, Asia Pacific, Latin America, and Middle East & Africa
- To profile the key players of the Anatomic Pathology Market and comprehensively analyze their core competencies and market shares
- To benchmark players within the market using the proprietary Company Evaluation Matrix framework, which analyzes market players on various parameters within the broad categories of business and product excellence
- To study the impact of AI on the market, along with the macroeconomic outlook for each region
Available customizations:
MarketsandMarkets offers the following customizations for this market report.
Company Information
- Additional country-level analysis of the anatomic pathology market
Company Profiles
- Additional five company profiles of players operating in the anatomic pathology market.
Product Analysis
-
Product matrix, which provides a detailed comparison of the product portfolio of each company in the anatomic pathology market
Get the Full Anatomic Pathology Market Report
Full forecast, segment splits, and company analysis for all Anatomic Pathology Market.
- US Anatomic Pathology Market
- Canada Anatomic Pathology Market
- Germany Anatomic Pathology Market
- UK Anatomic Pathology Market
- France Anatomic Pathology Market
- Italy Anatomic Pathology Market
- Spain Anatomic Pathology Market
- China Anatomic Pathology Market
- Japan Anatomic Pathology Market
- India Anatomic Pathology Market
- Rest Of Asia Pacific Anatomic Pathology Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report