Germany Laboratory Informatics Market (2024-2029)
The Germany Laboratory Informatics Market was valued at $161.4 Million in 2024 and projected to reach to $272.3 Million by 2029, representing a compound annual growth rate of 11.0%. Germany's laboratory informatics market is positioned for sustained expansion through 2029, supported by the country's commitment to healthcare digitalization and stringent regulatory frameworks.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Germany Laboratory Informatics Market Trends and Insights
- This expansion reflects Germany's strong healthcare infrastructure and increasing adoption of digital solutions in laboratory operations.
- Germany's market growth rate of 11.0% CAGR outpaces the global average, driven by regulatory compliance requirements, automation investments, and the integration of advanced data management systems across German clinical and research laboratories. The German laboratory informatics sector benefits from the country's emphasis on precision medicine and stringent quality standards in healthcare delivery.
- Germany's pharmaceutical and biotechnology industries are leveraging laboratory informatics solutions to enhance operational efficiency and data integrity.
- Between 2024 and 2029, Germany is expected to see accelerated adoption of cloud-based platforms, artificial intelligence-driven analytics, and interoperable systems that connect laboratory workflows with broader healthcare ecosystems..
Key Market Statistics
- CAGR (2024-2029) 11.0% CAGR
- Market Size, 2024 ~USD 161.4 Million
- Forecast, 2029 ~USD 272.3 Million
- Country Germany
Germany Laboratory Informatics Market Overview
Market Valuation Growth :
Germany's laboratory informatics market is valued at $161.4 million in 2024, with projections reaching $272.3 million by 2029, representing a robust 11% CAGR that exceeds global growth rates.
Regulatory Compliance Drivers :
Germany's stringent healthcare regulations and quality standards are accelerating the adoption of laboratory informatics solutions to ensure compliance with EU directives and German healthcare legislation.
Digital Healthcare Infrastructure :
Germany's advanced healthcare infrastructure and high digitalization rates in clinical and diagnostic laboratories are creating strong demand for integrated informatics platforms and data management systems.
Outpacing Global Growth :
With an 11% CAGR compared to the global average of 10.4%, Germany's market demonstrates stronger momentum driven by healthcare modernization initiatives and increased laboratory automation investments.
Germany Laboratory Informatics Market Dynamics
- The market's 11% CAGR reflects increasing investments in laboratory automation, data management systems, and compliance solutions across clinical diagnostics, pharmaceutical research, and hospital laboratories.
- German healthcare providers are prioritizing integrated informatics platforms to enhance operational efficiency and meet EU regulatory requirements. The forecast growth to $272.3 million by 2029 is underpinned by rising demand for cloud-based laboratory information systems, artificial intelligence-driven analytics, and interoperable healthcare IT solutions.
- Germany's strong pharmaceutical and biotechnology sectors further accelerate adoption of advanced laboratory informatics.
- Continued government support for digital health initiatives and increasing laboratory consolidation will drive market expansion throughout the forecast period..
Market Ecosystem
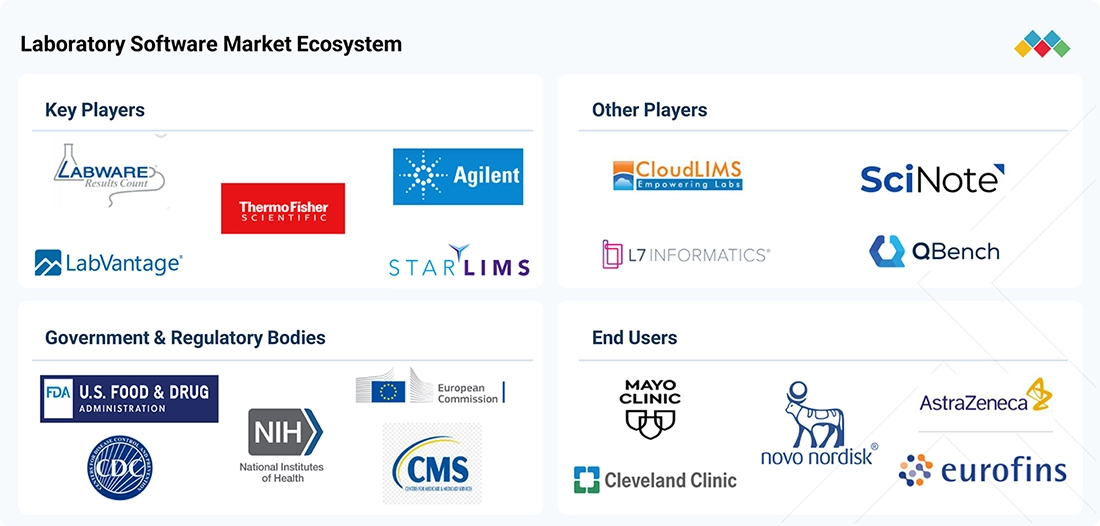
LABORATORY SOFTWARE MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Integrated laboratory informatics supporting sample management, laboratory automation, instrument connectivity, scientific data management, and multi-site laboratory workflows across life sciences and testing environments. | Improves laboratory efficiency and sample traceability, reduces manual data handling, strengthens data integrity, and enables better coordination across laboratory workflows. |
 |
Comprehensive laboratory informatics supporting sample and workflow management, data integration, laboratory automation, analytics, and quality processes across pharmaceutical, biotechnology, diagnostics, research, and testing laboratories. | Improves data accessibility and workflow visibility, reduces repetitive manual tasks, supports standardized processes, and helps laboratories make faster data-driven decisions. |
 |
Integrated laboratory management and automation supporting sample tracking, workflow execution, instrument connectivity, data management, quality control, and standardized laboratory processes across diverse industries. | Streamlines routine laboratory activities, improves data accuracy and traceability, reduces manual intervention, and supports consistent quality and regulatory compliance. |
 |
Digital laboratory informatics supporting sample and testing workflows, laboratory data management, quality processes, inventory, analytics, and regulatory compliance across clinical, life sciences, and testing environments. | Enhances sample visibility and traceability, simplifies laboratory workflows, improves data management, and supports quality, compliance, and operational efficiency. |
 |
Integrated analytical laboratory workflows supporting instrument connectivity, data acquisition and analysis, digital procedure execution, and standardized laboratory processes across pharmaceutical, chemical, and research applications. | Reduces manual steps, improves consistency and data integrity, simplifies analytical workflows, and enables laboratories to manage testing activities more efficiently. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Healthcare Analytics
- Machine Learning
- Natural Language Processing (NLP)
- Blood Pressure Monitors
- Computed Tomography (CT)
- Magnetic Resonance Imaging (MRI)
- Oracle Corporation
- PHILIPS HEALTHCARE
- Siemens healthineers
- International Business Machines Corporation
- EPIC SYSTEMS CORPORATION
Healthcare It
- Computed Tomography (CT)
- Machine Learning
- Magnetic Resonance Imaging (MRI)
- Natural Language Processing (NLP)
- Predictive Analytics
- CERNER CORPORATION
- PHILIPS HEALTHCARE
- Oracle Corporation
- GE HealthCare Technologies Inc.
- Siemens healthineers
Key Takeaways
- Germany's laboratory informatics market is valued at $161.4 million in 2024 and will reach $272.3 million by 2029, representing 11.0% CAGR growth.
- Germany's market growth rate exceeds the global average, driven by regulatory compliance, automation, and digital transformation in healthcare.
- Germany's pharmaceutical and biotechnology sectors are primary adopters of advanced laboratory informatics solutions for operational efficiency.
- Cloud-based platforms and AI-driven analytics are expected to accelerate adoption across German laboratories through 2029.
Laboratory Informatics Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | LABORATORY INFORMATION MANAGEMENT SYSTEMS (Type Of Solution) |
| Forecast Period | 2024–2029 |
| Growth Rate | CAGR of 10.4% from 2024 to 2029 |
| Largest Segment | LIFE SCIENCE INDUSTRIES (Industry) |
| Market Size Base Year (Billions) | ~USD 5.3 (2024) |
| Revenue Forecast (Billions) | ~USD 8.7 (2029) |
| Segments Covered | Type Of Solution, Type, Component, Deployment Model, Industry |
Germany Laboratory Informatics Market Report Segmentation
5 segment dimensions are covered across the global market.
By Type Of Solution
- Chromatography Data Systems
- Electronic Data Capture And Clinical Data Management Systems
- Electronic Lab Notebook
- Electronic Lab Notebooks
- Enterprise Content Management And Document Management Systems
- Laboratory Execution Systems
- Laboratory Information Management Systems
- Scientific Data Management Systems
By Type
- Academic Research Institutes
- Biobanks & Biorepositories
- Broad-Based Laboratory Information Management Systems
- Contract Service Organizations
- Industry-Specific Laboratory Information Management Systems
- Infrastructure-As-A-Service
- Infrastructure-As-A-Service Model
- Molecular Diagnostics And Clinical Research Laboratories
- Ngs Laboratories
- Pharmaceutical & Biotechnology Companies
- Platform-As-A-Service
- Platform-As-A-Service Model
- Software-As-A-Service
- Software-As-A-Service Model
- Toxicology Laboratories
By Component
- Services
- Software
- Support
By Deployment Model
- Cloud-Based Deployment Model
- On-Premises Deployment Model
By Industry
- Chemical Industries
- Environmental Testing Laboratories
- Food & Beverage And Agriculture Industries
- Forensics
- Life Science Industries
- Other Industries
- Petrochemicals And Oil & Gas Industries
GERMANY: LABORATORY INFORMATICS MARKET, BY INDUSTRY, 2022–2029
| Segment | 2022 | 2023 | 2024 | 2025 | 2026 | 2027 | 2028 | 2029 | CAGR (%) |
|---|---|---|---|---|---|---|---|---|---|
| CHEMICAL INDUSTRIES | 30.9 | 34 | 37.5 | 41.4 | 45.8 | 50.6 | 56.1 | 62.3 | 10.7 |
| ENVIRONMENTAL TESTING LABORATORIES | 21.2 | 23.2 | 25.4 | 27.8 | 30.5 | 33.5 | 36.9 | 40.7 | 9.9 |
| FOOD & BEVERAGE AND AGRICULTURE INDUSTRIES | 61.5 | 67.4 | 74.1 | 81.5 | 89.8 | 99.1 | 109.5 | 121.1 | 10.3 |
| FORENSICS | 4.5 | 4.9 | 5.3 | 5.8 | 6.4 | 7 | 7.6 | 8.4 | 9.6 |
| LIFE SCIENCE INDUSTRIES | 213.2 | 235.2 | 260 | 287.7 | 318.8 | 353.8 | 393 | 437.2 | 11 |
| OTHER INDUSTRIES | 6 | 6.6 | 7.2 | 7.8 | 8.6 | 9.4 | 10.3 | 11.4 | 9.6 |
| PETROCHEMICALS AND OIL & GAS INDUSTRIES | 47.2 | 51.7 | 56.7 | 62.3 | 68.5 | 75.5 | 83.2 | 91.9 | 10.1 |
| TOTAL | 384.5 | 423 | 466.2 | 514.5 | 568.4 | 628.9 | 696.7 | 772.9 | 10.6 |
Target Audience
- Healthcare IT Vendors : Laboratory informatics software and system providers need Germany-specific market data to identify growth opportunities, understand regulatory requirements, and develop localized solutions for German healthcare institutions.
- Hospital & Laboratory Administrators : Clinical laboratory directors and hospital IT decision-makers require market insights to evaluate informatics solutions, benchmark against industry standards, and justify digital transformation investments.
- Pharmaceutical & Biotech Companies : German pharmaceutical and biotechnology firms need market intelligence on laboratory informatics adoption to optimize R&D operations, ensure regulatory compliance, and enhance laboratory efficiency.
- Healthcare Consultants & Analysts : Management consultants and healthcare analysts serving German clients require detailed market data to support strategic recommendations, feasibility studies, and investment decisions in laboratory informatics.
- Private Equity & Investors : Investment firms evaluating healthcare IT opportunities in Germany need comprehensive market sizing, growth forecasts, and competitive analysis to assess acquisition targets and portfolio companies.
Key Companies in the Germany Laboratory Informatics Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| NIPPON CONTROL SYSTEM CORPORATION. | Japan | LIMS,CDS,ELN, | |
| CHEMWARE | Australia | Public Company | Wholesale pharmaceutical distribution,Retail pharmacy franchising and banners,Logistics and third-/fourth-party services, |
| LABLOGIC SYSTEMS LTD. | United Kingdom | Private Company | LIMS (including LES-style workflow modules),CDS and radiochromatography informatics,SDMS / data management and archiving, |
| BIOMERIEUX S.A. | France | Public Company | LIMS and LES,CDS, SDMS, and data management,Clinical decision-support and epidemiology software (vision suite, EPISEQ CS), |
| KINDRED HEALTHCARE INC. | United States | Private Company | LIMS,ELN,CDS, |
| LEIDOS | United States | Public Company | LIMS,ELN,CDS, |
| THERMO FISHER SCIENTIFIC INC. | United States | ||
| STARLIMS CORPORATION | Israel | Private Company | LIMS,ELN,SDMS, |
| AGILENT TECHNOLOGIES, INC. | United States | Public Company | Chromatography Data Systems (CDS) and instrument-control software,LIMS / LES / basic workflow management,SDMS and secure data storage, |
| WATERS CORPORATION | United States | Public Company | CDS,SDMS & scientific data management,LIMS / LES, |
| LABLYNX LIMS | United States | Private Company | LIMS Software Licenses & Subscriptions,Implementation & Professional Services,Support & Managed Services, |
| DASSAULT SYSTèMES | France | Public Company | ELN / Scientific Informatics (BIOVIA-centric),LIMS / LES,SDMS / Data Intelligence (incl. NETVIBES, MEDIDATA links), |
| REVVITY | United States | Public Company | LIMS (incl. iLab, LifeCycle, LimsLink, Specimen Gate),ELN & scientific productivity (ChemDraw, workflow tools),CDS & chromatography/LC-MS informatics (SimplicityChrom, integration), |
| XYBION DIGITAL INC. | Canada | Public Company | LIMS,ELN,CDS, |
NIPPON CONTROL SYSTEM CORPORATION.
Nippon Control System Corporation is a Japanese company founded in 1971 specializing in control systems and automation solutions.
CHEMWARE
Chemware is an Australian public company established in 1912 operating in the chemical or laboratory products sector.
LABLOGIC SYSTEMS LTD.
LabLogic Systems Ltd. is a United Kingdom-based private company founded in 1980 providing laboratory information management solutions.
BIOMERIEUX S.A.
bioMérieux S.A. is a French public company founded in 1963 with 14,894 employees specializing in in vitro diagnostics and microbiology testing.
KINDRED HEALTHCARE INC.
Kindred Healthcare Inc. is a United States-based private company founded in 1985 with 64,200 employees operating in the healthcare and rehabilitation services sector.
LEIDOS
Leidos is a United States-based public company founded in 1969 with 50,000 employees providing engineering, IT, and scientific solutions to government and commercial clients.
THERMO FISHER SCIENTIFIC INC.
Thermo Fisher Scientific Inc. is a United States-based company providing laboratory equipment, reagents, and scientific services.
STARLIMS CORPORATION
StarLIMS Corporation is an Israel-based private company founded in 1986 with 162 employees offering laboratory information management systems.
AGILENT TECHNOLOGIES, INC.
Agilent Technologies, Inc. is a United States-based public company founded in 1999 with 18,000 employees providing life sciences, diagnostics, and applied chemical markets solutions.
WATERS CORPORATION
Waters Corporation is a United States-based public company founded in 1958 with 7,900 employees specializing in analytical laboratory instruments and software.
LABLYNX LIMS
LabLynx LIMS is a United States-based private company founded in 1997 providing laboratory information management system solutions.
DASSAULT SYSTèMES
Dassault Systèmes is a French public company founded in 1981 with 25,724 employees providing 3D design, simulation, and digital lifecycle management software.
REVVITY
Revvity is a United States-based public company founded in 1937 with 11,000 employees providing analytical instruments, software, and services for life sciences and diagnostics.
XYBION DIGITAL INC.
Xybion Digital Inc. is a Canadian public company founded in 1977 providing laboratory information management and scientific data solutions.
Reasons to Buy this Report
- Market-Specific Growth Intelligence : Gain detailed insights into Germany's 11% CAGR trajectory and understand the unique drivers propelling the market ahead of global averages, enabling informed investment and expansion decisions.
- Regulatory Compliance Roadmap : Access comprehensive analysis of German and EU regulatory requirements shaping laboratory informatics adoption, critical for vendors and healthcare providers navigating compliance landscapes.
- Competitive Landscape Analysis : Understand the competitive dynamics specific to Germany's market, including key players, market positioning, and differentiation strategies in the $272.3 million opportunity by 2029.
- Sector-Specific Opportunities : Identify high-growth segments within Germany's pharmaceutical, biotechnology, and clinical laboratory sectors, with tailored insights for targeted market penetration and partnership development.
- Strategic Planning & Forecasting : Leverage detailed 5-year projections and market segmentation data to develop evidence-based strategies for product launches, acquisitions, and resource allocation in the German market.
Frequently asked questions
What is the current size of Germany's laboratory informatics market?
Germany's laboratory informatics market was valued at $161.4 million in 2024 and is projected to grow to $272.3 million by 2029.
What is the growth rate for laboratory informatics in Germany?
Germany's laboratory informatics market is growing at a compound annual growth rate (CAGR) of 11.0% from 2024 to 2029.
What are the primary drivers of growth in Germany's laboratory informatics market?
Key drivers include regulatory compliance requirements, automation investments, digital transformation in healthcare, and the adoption of cloud-based and AI-driven solutions across German laboratories.
Which industries are leading adoption of laboratory informatics in Germany?
Germany's pharmaceutical and biotechnology industries are the primary adopters, leveraging laboratory informatics to enhance operational efficiency and data integrity.
What technologies are expected to drive Germany's laboratory informatics market through 2029?
Cloud-based platforms, artificial intelligence-driven analytics, and interoperable systems connecting laboratory workflows with broader healthcare ecosystems are expected to accelerate adoption in Germany.
RESEARCH METHODOLOGY
The study involved several key activities to estimate the current size of the laboratory software market. Extensive secondary research was conducted to gather information on this market. The next step was to validate the findings, assumptions, and size estimates by consulting industry experts throughout the value chain through primary research. Various methods were employed, including top-down and bottom-up approaches, to estimate the overall market size. Following this, market segmentation and data triangulation techniques were utilized to determine the size of specific segments and subsegments within the laboratory software market.
Secondary Research
This research study involved the wide use of secondary sources, directories, databases such as Dun & Bradstreet, Bloomberg Businessweek, and Factiva; white papers, annual reports, and companies’ house documents, investor presentations; and the SEC filings of companies. Secondary research was used to identify and collect information useful for an extensive, technical, market-oriented, and commercial study of the laboratory informatics market. It was also used to obtain important information about the key players and market classification & segmentation according to industry trends to the bottom-most level and key developments related to market and technology perspectives. A database of the key industry leaders was also prepared using secondary research.
Some of the key secondary sources referred to for this study include:
- U.S. Food and Drug Administration (FDA)
- European Medicines Agency (EMA)
- International Organization for Standardization (ISO)
- Clinical and Laboratory Standards Institute (CLSI)
- World Health Organization (WHO)
- International Council for Harmonisation of Technical Requirements for Pharmaceuticals for Human Use (ICH)
- International Society for Pharmaceutical Engineering (ISPE)
- Society for Laboratory Automation and Screening (SLAS)
- U.S. Centers for Medicare & Medicaid Services (CMS)
- U.S. Centers for Disease Control and Prevention (CDC)
- U.S. Securities and Exchange Commission
- Investor Presentations, SEC Filings, and Company Annual Reports
- White Papers, Scientific Journals/Magazines, and News Articles
- Paid Databases, such as Factiva, D&B Hoovers, and Bloomberg
Primary Research
In the primary research process, various sources from both the supply and demand sides were interviewed to obtain qualitative and quantitative information for this report. Primary sources are mainly industry experts from the core and related industries and preferred suppliers, manufacturers, distributors, technology developers, researchers, and organizations related to all segments of this industry’s value chain. In-depth interviews were conducted with various primary respondents, including key industry participants, subject-matter experts (SMEs), C-level executives of key market players, and industry consultants, among other experts, to obtain and verify the critical qualitative and quantitative information as well as assess prospects.
Primary research was conducted to identify segmentation types; industry trends; key players; and key market dynamics such as drivers, restraints, opportunities, challenges, industry trends, and strategies adopted by key players.
Breakdown of the Primary Respondents:
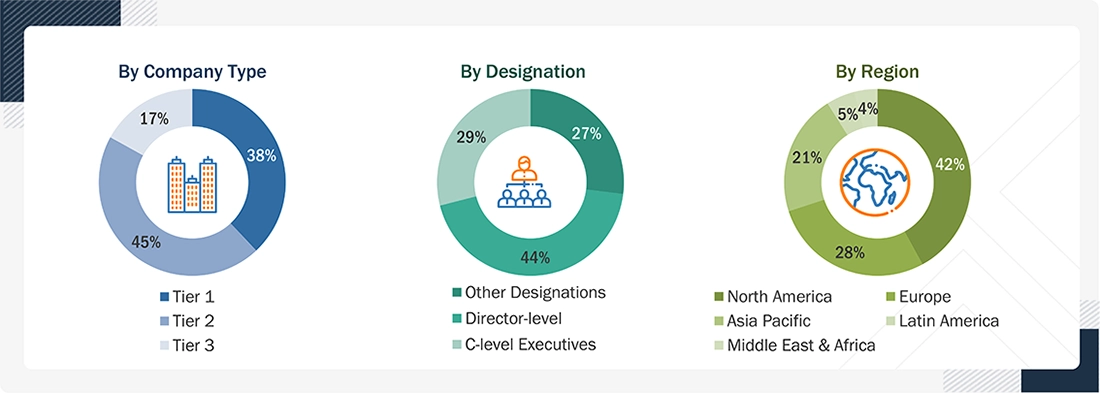
*Others include sales managers, marketing managers, and product managers.
Note: Tiers are defined based on a company’s total revenue, as of 2025: Tier 1 = >USD 1 billion, Tier 2 = USD 500 million to USD 1 billion, and Tier 3 = <USD 500 million.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
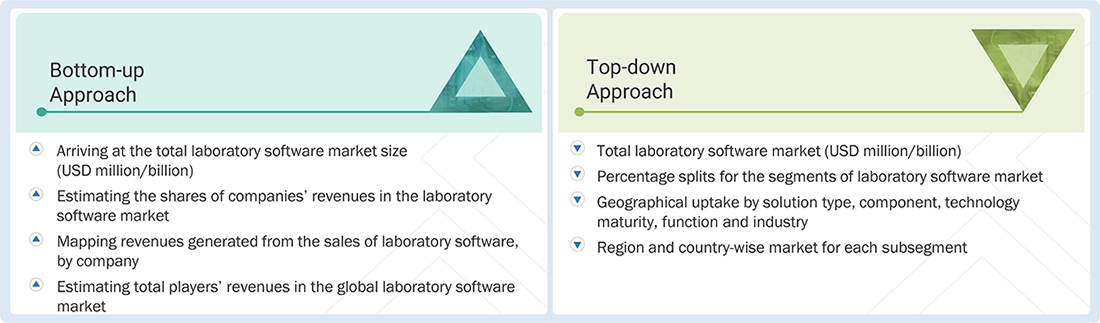
The market size estimates and forecasts provided in this study are derived through a mix of the bottom-up approach (revenue share analysis of leading players) and top-down approach (assessment of utilization/adoption/penetration trends, by solution type, component, technology maturity, function, industry, and region).
Laboratory Software Market : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size using the market size estimation processes, the market was split into several segments and subsegments. To complete the overall market engineering process and arrive at the exact statistics of each market segment and sub-segment, the data triangulation and market breakdown procedures were employed, wherever applicable. The data was triangulated by studying various factors and trends from both the demand and supply sides in the laboratory software market.
Market Definition
Laboratory software refers to solutions designed specifically to support laboratory operations, including the management of scientific data, laboratory workflows, instruments, compliance, and documentation. It encompasses data acquisition, lab automation, instrument interfacing, laboratory networking, data processing, specialized data management systems, laboratory information management systems, scientific data management systems (including data mining and data warehousing), and knowledge management (including the use of electronic laboratory notebooks), among others.
Key Stakeholders
- Laboratory software providers
- Platform providers
- Technology providers
- System integrators
- Healthcare IT service providers
- Pharmaceutical & biotechnology companies
- Research and consulting firms
- Process industries
- Forums, alliances, and associations
- Distributors
- Venture capitalists
- Government organizations
- Academic research institutes
- Institutional investors and investment banks
- Investors/Shareholders
- Consulting companies in the sector
- Raw material and component manufacturers
Report Objectives
- To define, describe, and forecast the global Laboratory Software market based on solution type, component, technology maturity, function, industry, and region
- To provide detailed information regarding the major factors influencing the growth of the market (drivers, restraints, opportunities, and challenges)
- To strategically analyze micro markets with respect to individual growth trends, prospects, and contributions to the overall market
- To analyze the opportunities in the market for stakeholders and provide details of the competitive landscape for market leaders
- To forecast the size of the market segments with respect to five main regions, namely, North America, Europe, Asia, Latin America and Middle East & Africa
- To profile key market players and comprehensively analyze their product portfolios, market positions, and core competencies
- To track and analyze competitive developments such as acquisitions; product launches and upgrades; expansions; agreements, partnerships, and acquisitions; and R&D activities in the Laboratory Software market
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per your company’s specific needs. The following customization options are available for the report:
Company Information
- Detailed analysis and profiling of additional market players (up to 5)
Geographic Analysis
- Further breakdown of the Rest of Asia Pacific radiation dose management market into Taiwan, New Zealand, Thailand, Singapore, Malaysia, and other countries.
- Further breakdown of the Rest of Europe radiation dose management market into Russia, Austria, Finland, Turkey, Norway, Poland, Portugal, Romania, Denmark, and other countries.
Get the Full Laboratory Informatics Market Report
Full forecast, segment splits, and company analysis for all Laboratory Informatics Market.
- Canada Laboratory Informatics Market
- US Laboratory Informatics Market
- UK Laboratory Informatics Market
- France Laboratory Informatics Market
- Italy Laboratory Informatics Market
- Spain Laboratory Informatics Market
- Japan Laboratory Informatics Market
- China Laboratory Informatics Market
- India Laboratory Informatics Market
- Brazil Laboratory Informatics Market
- Mexico Laboratory Informatics Market
- Rest Of Europe Laboratory Informatics Market
- Rest Of Asia Pacific Laboratory Informatics Market
- Rest Of Latin America Laboratory Informatics Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report