Taiwan Semiconductor Manufacturing Equipment Market (2025-2030)

The Taiwan Semiconductor Manufacturing Equipment Market was valued at $36888.3 Million in 2025 and projected to reach to $65730 Million by 2030, representing a compound annual growth rate of 8.6%. Taiwan's semiconductor manufacturing equipment market is poised for sustained growth through 2030, driven by the island's unparalleled position in global chip production.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Taiwan Semiconductor Manufacturing Equipment Market Trends and Insights
- Taiwan's position as a global semiconductor hub drives substantial demand for advanced manufacturing equipment, supported by major foundry operations and ongoing capacity expansions.
- The market in Taiwan reflects the country's critical role in global chip production and its continuous investment in next-generation fabrication technologies. During the 2025–2030 forecast period, Taiwan's semiconductor manufacturing equipment market will benefit from increased capital expenditures by leading chipmakers and the transition toward advanced nodes.
- Taiwan's equipment market growth is underpinned by rising demand for precision tools, process control systems, and automation solutions required for sub-5nm and advanced packaging processes.
- Strategic government initiatives and industry partnerships further strengthen Taiwan's competitive advantage in semiconductor manufacturing, ensuring sustained equipment market expansion through 2030..
Key Market Statistics
- CAGR (2025-2030) 8.6% CAGR
- Market Size, 2025 ~USD 36888.3 Million
- Forecast, 2030 ~USD 65730 Million
- Country Taiwan
Taiwan Semiconductor Manufacturing Equipment Market Overview
Market Valuation Growth :
Taiwan's semiconductor manufacturing equipment market is valued at USD 36,888.3 million in 2025 and is projected to reach USD 65,730 million by 2030, demonstrating robust expansion driven by foundry dominance and capacity investments.
Foundry Leadership Impact :
Taiwan's position as the world's leading semiconductor foundry hub, anchored by TSMC and MediaTek, creates sustained demand for cutting-edge manufacturing equipment and process technology upgrades.
Advanced Node Investments :
Continuous investments in advanced node manufacturing (3nm, 5nm, and below) by Taiwan's major chipmakers necessitate state-of-the-art equipment for lithography, etching, and deposition processes.
Regional Supply Chain Hub :
Taiwan's strategic role in the global semiconductor supply chain attracts equipment manufacturers and suppliers, creating a competitive ecosystem that drives innovation and market growth at 8.6% CAGR.
Taiwan Semiconductor Manufacturing Equipment Market Dynamics
- Major foundries are expanding capacity to meet surging demand for advanced semiconductors in AI, automotive, and IoT applications.
- Government support through subsidies and infrastructure development further strengthens the market foundation.
- The 8.6% CAGR reflects steady modernization of existing fabs and construction of new facilities.
- However, geopolitical tensions and supply chain diversification efforts may introduce volatility.
- Equipment suppliers focusing on Taiwan will benefit from long-term partnerships with established chipmakers and access to cutting-edge technology requirements..
Market Ecosystem
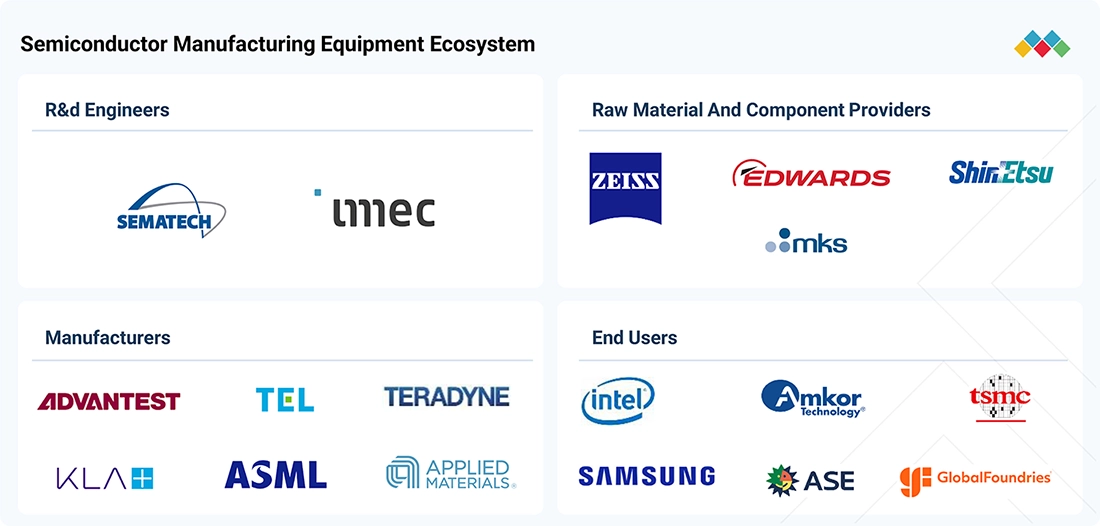
SEMICONDUCTOR MANUFACTURING EQUIPMENT MARKET SIZE, SHARE & TRENDS: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Provides deposition, etching, materials modification, and inspection technologies for semiconductor fabrication and advanced packaging | Enables precise material processing | Improves wafer yield | Supports advanced chip architectures | Enhances manufacturing productivity |
 |
Develops extreme ultraviolet (EUV) and deep ultraviolet (DUV) lithography systems for printing circuit patterns on semiconductor wafers | Enables advanced node manufacturing | Supports higher transistor density | Improves patterning precision | Supports semiconductor scaling |
 |
Provides wafer fabrication equipment for deposition, etching, and cleaning processes used in logic, memory, and advanced packaging manufacturing | Enables precise material removal | Supports complex three-dimensional structures | Improves process control | Enhances manufacturing yields |
 |
Supplies semiconductor production equipment for coating and developing, deposition, etching, cleaning, and other wafer processing steps | Supports advanced wafer processing | Improves process uniformity | Enables higher production efficiency | Supports advanced semiconductor manufacturing |
 |
Provides inspection, metrology, and process control equipment to detect defects and monitor manufacturing processes across semiconductor production | Enables early defect detection | Improves process control | Supports higher yields | Reduces manufacturing variability |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Automotive Electronics And Electrical Equipment
- Battery Electric Vehicle (BEV)
- Light Commercial Vehicles (LCVs)
- Fuel Cell Electric Vehicle (FCEV)
- Sensors
- Hybrid Electric Vehicle (HEV)
- BOSCH LIMITED
- DENSO Corporation
- Continental ag
- Panasonic Holdings Corporation
- Texas Instruments Incorporated
Semiconductor Materials And Components
- Sensors
- Gallium Nitride (GaN)
- Digital Signal Processor (DSP)
- Natural Language Processing (NLP)
- Silicon Carbide
- Texas Instruments Incorporated
- Samsung
- APPLIED MATERIALS, INC.
- Stmicroelectronics
- Lenovo
Key Takeaways
- Taiwan's semiconductor manufacturing equipment market is valued at USD 36.9 billion in 2025 and will grow to USD 65.7 billion by 2030 at an 8.6% CAGR.
- Taiwan's foundry-centric ecosystem and advanced node transitions drive consistent demand for cutting-edge manufacturing equipment and process technologies.
- Capital expenditure cycles by Taiwan's leading chipmakers directly correlate with equipment market growth and technology node advancement.
- Taiwan's strategic position in global semiconductor supply chains ensures sustained investment in manufacturing equipment innovation through 2030.
Semiconductor Manufacturing Equipment Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | OSAT COMPANIES (End User) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 11% from 2025 to 2030 |
| Largest Segment | FRONT-END (Manufacturing Phase) |
| Market Size Base Year (Billions) | ~USD 165.86 (2025) |
| Revenue Forecast (Billions) | ~USD 279.49 (2030) |
| Segments Covered | Manufacturing Phase, Front-End Equipment, Type, Back-End Equipment, End User |
Taiwan Semiconductor Manufacturing Equipment Market Report Segmentation
5 segment dimensions are covered across the global market.
By Manufacturing Phase
- Back-End
- Front-End
- Other Phases
By Front-End Equipment
- Deposition Equipment
- Lithography Equipment
- Metrology & Inspection Equipment
- Other Front-End Equipment
- Wafer Cleaning Equipment
- Wafer Surface Conditioning Equipment
By Type
- Cmp Equipment
- Etching Equipment
- Extreme Ultraviolet (Euv)
By Back-End Equipment
- Bonding
- Dicing
- Packaging
- Wafer Testing/Ic Testing
By End User
- Foundries
- Idm Firms
- Idms
- Osat Companies
- Other End Users
- Other Phases
Target Audience
- Equipment Manufacturers : Semiconductor equipment suppliers need Taiwan-specific market data to identify sales opportunities, understand customer requirements from TSMC and other foundries, and plan product development roadmaps.
- Chipmakers & Foundries : Taiwan-based semiconductor manufacturers require market intelligence to benchmark equipment investments, evaluate supplier performance, and align capacity expansion plans with market growth projections.
- Investment & Private Equity Firms : Investors targeting Taiwan's semiconductor sector need detailed market analysis to evaluate investment opportunities, assess growth potential, and identify acquisition targets in the equipment supply chain.
- Government & Policy Makers : Taiwan's government agencies and policymakers use market data to inform semiconductor industry support programs, infrastructure investments, and strategic initiatives to maintain competitive advantage.
- Consulting & Research Firms : Business consultants and research organizations require Taiwan market cutouts to support client advisory services, competitive analysis, and strategic planning in the semiconductor manufacturing sector.
Key Companies in the Taiwan Semiconductor Manufacturing Equipment Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| SOJITZ CORPORATION | Japan | Public Company | Energy, Resources and Chemicals,Automotive, Aerospace and Transportation Infrastructure,Power, IPP/IWPP and Industrial Infrastructure, |
| FLUOR CORPORATION | United States | Public Company | Energy Solutions (oil, gas, chemicals, LNG, power, energy transition),Urban Solutions (advanced technologies, life sciences, mining and metals, infrastructure, staffing, maintenance),Mission Solutions (government nuclear, security, logistics, mission-critical facilities), |
| SOITEC | France | Public Company | CONNECT RF-SOI for smartphone front-end and RF GaN for 5G,FD-SOI and AUTO FD-SOI for AI, edge, and automotive,Power-SOI and Auto SmartSiC for automotive and industrial, |
| CHROMA ATE | Taiwan | Public Company | Power electronics, server power, and telecom power test systems,Battery, EV, and energy storage test and automation,Semiconductor/IC and PXI test solutions, |
| TEXAS INSTRUMENTS INC | United States | Public Company | Analog – Power,Analog – Signal Chain,Embedded Processing, |
| UNITED MICROELECTRONICS CORP | Taiwan | Public Company | Communications ICs (wireless, networking),Consumer electronics ICs,Automotive semiconductors, |
| SHINCRON CO., LTD. | Japan | Private Company | Optical and precision thin-film coating systems,Industrial and decorative coating equipment,Functional film and advanced materials deposition tools, |
| HITACHI | Japan | Public Company | Digital Systems & Services (IT, cloud, integration),Green Energy & Mobility (power grids, energy, rail),Connective Industries (industrial automation, e-mobility, equipment), |
| APPLIED MATERIALS, INC. | United States | Public Company | Deposition and Etch Systems,CMP, RTP, and Implant,Metrology and Inspection, |
| ASML | Netherlands | Public Company | EUV lithography systems,DUV immersion and dry lithography systems,Metrology and inspection (YieldStar, HMI e-beam), |
| TOKYO ELECTRON LIMITED | Japan | Public Company | Coaters/Developers & Lithography Adjacent,Plasma Etch Systems,Cleaning Systems, |
| LAM RESEARCH CORPORATION | United States | Public Company | Etch systems (dielectric, conductor, TSV),Deposition (CVD, ALD, ECD, gapfill),Clean and bevel (Coronus, Da Vinci/DV-Prime/EOS/SP), |
| KLA CORPORATION | United States | Public Company | Core B2C CRM and Email Marketing,Mobile Messaging and Push (SMS, RCS, WhatsApp, Push),Klaviyo Data Platform (KDP and Advanced KDP), |
| SCREEN HOLDINGS CO., LTD. | Japan | Public Company | Semiconductor Production Equipment,Graphic Arts Equipment,Display Production Equipment and Coater, |
| TERADYNE INC. | United States | Public Company | Semiconductor Test,Robotics,Other (Defense/Aerospace, Board, Wireless, Silicon Photonics Test), |
| ADVANTEST CORPORATION | Japan | Public Company | SoC automated test equipment,Memory and SSD test systems,Handlers, device interfaces, and interconnect solutions, |
| HITACHI HIGH-TECH CORPORATION | Japan | Private Company | Analytical & Medical Solutions,Nano-Technology Solutions (semiconductor and metrology tools),Industrial Solutions and ICT/Components, |
| ASM INTERNATIONAL | Netherlands | Public Company | ALD and PEALD wafer-processing systems,Epitaxy and SiC Epi tools,PECVD and vertical furnace systems (LPCVD, diffusion, oxidation, cure), |
| ONTO INNOVATION | United States | Public Company | Macro-defect inspection and silicon wafer all-surface inspection systems,Optical and integrated metrology systems (including opaque/transparent thin film),Advanced packaging lithography and packaging process tools, |
| NORDSON CORPORATION | United States | Public Company | Industrial Precision Solutions,Medical and Fluid Solutions,Advanced Technology Solutions, |
SOJITZ CORPORATION
Sojitz Corporation is a Japanese public company founded in 1862 with 26,789 employees. It operates as a diversified trading and investment company with global operations.
FLUOR CORPORATION
Fluor Corporation is a United States-based public company founded in 1912 with 22,995 employees. It provides engineering, procurement, and construction services to various industries.
SOITEC
Soitec is a French public company founded in 1992 with 1,961 employees. It specializes in the design and production of semiconductor materials and engineered substrates.
CHROMA ATE
Chroma ATE is a Taiwanese public company founded in 1984 with 1,639 employees. It manufactures test and measurement equipment for the electronics industry.
TEXAS INSTRUMENTS INC
Texas Instruments Inc. is a United States-based public company founded in 1930 with 33,000 employees. It designs and manufactures semiconductors and analog integrated circuits.
UNITED MICROELECTRONICS CORP
United Microelectronics Corp. is a Taiwanese public company founded in 1980 with 20,000 employees. It is a semiconductor foundry providing chip manufacturing services.
SHINCRON CO., LTD.
Shincron Co., Ltd. is a Japanese private company founded in 1951. It operates in specialized manufacturing and industrial sectors.
HITACHI
Hitachi is a Japanese public company founded in 1910 with 287,901 employees. It is a diversified conglomerate operating in electronics, industrial equipment, and infrastructure.
APPLIED MATERIALS, INC.
Applied Materials, Inc. is a United States-based public company founded in 1967 with 36,500 employees. It manufactures equipment and materials used in semiconductor and display manufacturing.
ASML
ASML is a Netherlands-based public company founded in 1984 with 43,938 employees. It designs and manufactures advanced lithography systems for the semiconductor industry.
TOKYO ELECTRON LIMITED
Tokyo Electron Limited is a Japanese public company founded in 1951 with 20,236 employees. It manufactures semiconductor production equipment and provides related services.
LAM RESEARCH CORPORATION
Lam Research Corporation is a United States-based public company founded in 1980 with 20,600 employees. It designs and manufactures semiconductor processing equipment.
KLA CORPORATION
KLA Corporation is a United States-based public company founded in 2012 with 2,333 employees. It provides process control and yield management solutions for semiconductor manufacturing.
SCREEN HOLDINGS CO., LTD.
Screen Holdings Co., Ltd. is a Japanese public company founded in 1943 with 7,170 employees. It manufactures semiconductor production equipment and imaging systems.
TERADYNE INC.
Teradyne Inc. is a United States-based public company founded in 1960 with 6,600 employees. It designs and manufactures automatic test equipment for the semiconductor industry.
ADVANTEST CORPORATION
Advantest Corporation is a Japanese public company founded in 1946 with 7,241 employees. It designs and manufactures semiconductor test equipment and systems.
HITACHI HIGH-TECH CORPORATION
Hitachi High-Tech Corporation is a Japanese private company founded in 1947 with 11,482 employees. It provides analytical instruments, semiconductor equipment, and industrial solutions.
ASM INTERNATIONAL
ASM International is a Netherlands-based public company founded in 1968 with 4,908 employees. It designs and manufactures equipment for semiconductor device manufacturing.
ONTO INNOVATION
Onto Innovation is a United States-based public company founded in 1940 with 1,615 employees. It provides process technology solutions for semiconductor and advanced packaging applications.
NORDSON CORPORATION
Nordson Corporation is a United States-based public company founded in 1909 with 8,200 employees. It manufactures precision dispensing, coating, and surface treatment equipment.
Reasons to Buy this Report
- Identify Growth Opportunities : Understand Taiwan's equipment market expansion from USD 36.9B to USD 65.7B, pinpointing investment and partnership opportunities with foundries and equipment manufacturers operating in the region.
- Competitive Intelligence : Gain insights into Taiwan's foundry ecosystem, major players' capacity expansion plans, and technology roadmaps to benchmark against competitors and inform strategic positioning.
- Supply Chain Optimization : Evaluate Taiwan's role as a semiconductor manufacturing hub to optimize supply chain strategies, identify key suppliers, and assess risks related to geopolitical factors and diversification trends.
- Technology Trend Analysis : Access detailed data on advanced node manufacturing requirements, equipment specifications, and process technology trends specific to Taiwan's leading chipmakers and their equipment needs.
- Market Entry Strategy : Develop informed market entry or expansion strategies for Taiwan with comprehensive data on market size, growth drivers, regulatory environment, and key decision-makers in the semiconductor equipment sector.
Frequently asked questions
What is the current size of Taiwan's semiconductor manufacturing equipment market?
Taiwan's semiconductor manufacturing equipment market is valued at USD 36,888.3 million in 2025.
What is the projected market size for Taiwan's semiconductor manufacturing equipment by 2030?
Taiwan's semiconductor manufacturing equipment market is forecast to reach USD 65,730 million by 2030.
What is the CAGR for Taiwan's semiconductor manufacturing equipment market?
Taiwan's semiconductor manufacturing equipment market is expected to grow at a compound annual growth rate of 8.6% from 2025 to 2030.
What factors drive growth in Taiwan's semiconductor manufacturing equipment market?
Taiwan's equipment market growth is driven by advanced node transitions, increased capital expenditures by foundries, demand for precision manufacturing tools, and government support for semiconductor infrastructure development.
Why is Taiwan significant in the global semiconductor manufacturing equipment market?
Taiwan hosts major semiconductor foundries and advanced fabrication facilities, making it a critical hub for manufacturing equipment demand and innovation in the global semiconductor supply chain.
RESEARCH METHODOLOGY
The study involved major activities in estimating the current market size of the semiconductor manufacturing equipment market. Exhaustive secondary research was conducted to collect information on semiconductor manufacturing technologies, equipment categories, industry developments, and key market participants. The next step was to validate these findings and assumptions with industry experts across the value chain through primary research. Different approaches, including top-down and bottom-up methods, were employed to estimate the total market size. Following this, market breakdown and data triangulation procedures were used to determine the market sizes of segments and subsegments.
Secondary Research
Secondary research for this study involved gathering information from credible sources, including company annual reports, investor presentations, government publications, industry journals, technical papers, and semiconductor industry publications. This process helped understand the semiconductor manufacturing equipment value chain, identify key players, analyze market segmentation and regional trends, and track major technological developments and capacity expansion initiatives. The collected data was used to estimate the overall market size and segment-level revenues, which were subsequently validated through primary research.
Primary Research
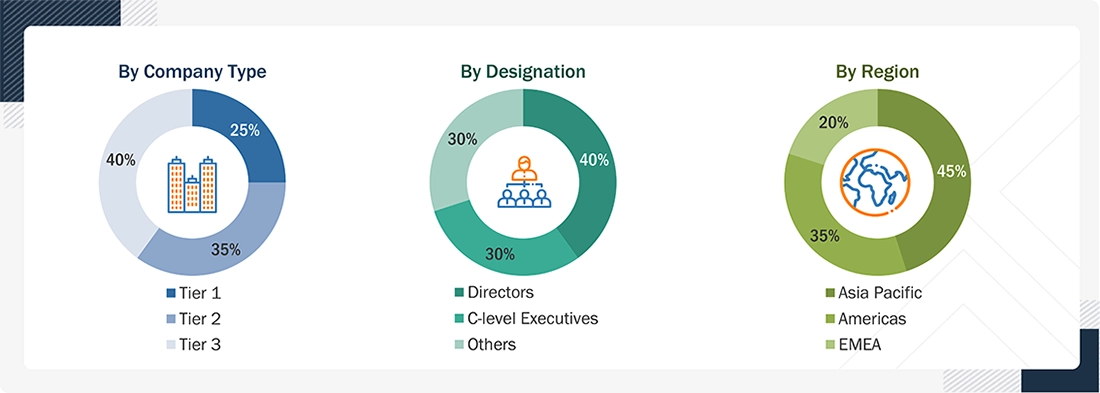
Extensive primary research was conducted after assessing the semiconductor manufacturing equipment market through secondary research. Interviews were conducted with experts from the demand and supply sides across four major regions: Americas, Asia Pacific, Europe, and the Middle East and Africa (MEA). Respondents included equipment manufacturers, semiconductor foundries, integrated device manufacturers (IDMs), outsourced semiconductor assembly and test (OSAT) providers, and industry experts. Primary data was collected through questionnaires, emails, and telephonic interviews to validate market estimates, growth trends, segmentation, and regional demand.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
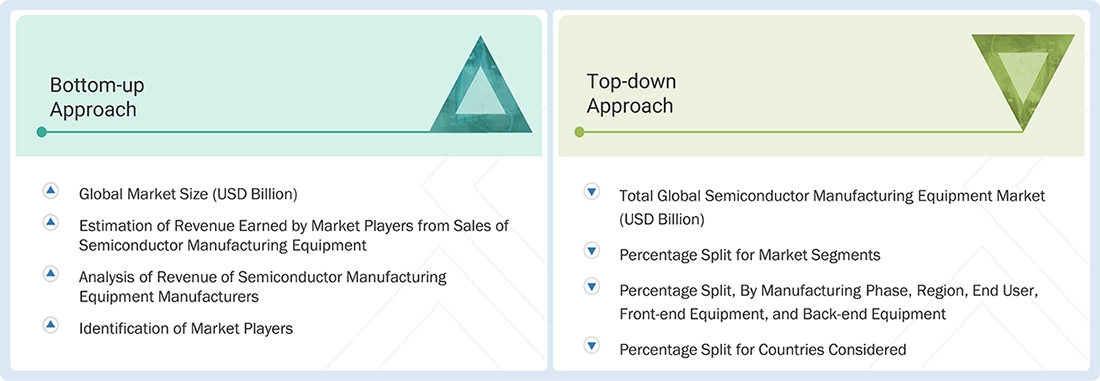
The bottom-up procedure was employed to arrive at the overall size of the semiconductor manufacturing equipment market.
- Identifying semiconductor manufacturing equipment offered by key players across front-end and back-end manufacturing processes
- Tracking major manufacturers and suppliers of lithography, deposition, etching, wafer cleaning, inspection, metrology, assembly, and testing equipment across different regions
- Tracking ongoing and upcoming product launches, capacity expansions, acquisitions, partnerships, and collaborations among semiconductor equipment manufacturers
- Estimating and forecasting the semiconductor manufacturing equipment market in each country and region based on equipment manufacturers' revenues, semiconductor fabrication investments, and relevant industry indicators
- Conducting discussions with key opinion leaders to understand equipment demand across foundries, integrated device manufacturers (IDMs), and outsourced semiconductor assembly and test (OSAT) providers while analyzing the revenue contribution of major companies
- Verifying and cross-checking estimates at every level through discussions with key opinion leaders, including company executives, directors, operations managers, and semiconductor industry experts.
- Studying paid and unpaid information sources, including annual reports, investor presentations, press releases, technical papers, industry publications, and government documents
The top-down approach was used to estimate and validate the total size of the semiconductor manufacturing equipment market.
- Analyzing global semiconductor manufacturing equipment market revenue and overall semiconductor industry investment trends
- Calculating market size using revenue generated by major players through semiconductor manufacturing equipment sales
- Segmenting the market by manufacturing phase, front-end equipment, back-end equipment, end user, and region to derive segment-level market estimates
- Acquiring and analyzing information related to revenues generated by major players through their key equipment offerings
- Conducting discussions with key opinion leaders involved in semiconductor fabrication, wafer processing, advanced packaging, and semiconductor testing equipment
- Estimating geographic market distribution using secondary sources and factors such as semiconductor fabrication capacity, equipment installations, manufacturing investments, and the presence of major semiconductor manufacturers in each country and region.
The market size includes the following:
Data Triangulation
After arriving at the overall market size using the market size estimation processes explained above, the semiconductor manufacturing equipment market has been divided into several segments and subsegments. Data triangulation and market breakdown procedures have been employed to complete the market engineering process and determine the market size of each segment and subsegment. The data has been triangulated by analyzing factors and trends from the demand and supply sides of the semiconductor manufacturing equipment market.
Market Definition
The semiconductor manufacturing equipment market comprises equipment used to manufacture, process, assemble, inspect, and test semiconductor devices. The market includes front-end equipment, such as lithography, deposition, etching, and wafer cleaning systems, and back-end equipment used for semiconductor assembly, packaging, and testing. These technologies support the production of logic, memory, analog, and other semiconductor devices. The equipment is used by foundries, integrated device manufacturers (IDMs), and outsourced semiconductor assembly and test (OSAT) providers. The market covers equipment sales used in semiconductor fabrication, wafer processing, assembly, packaging, inspection, and testing.
Key Stakeholders
- Raw Material Suppliers
- Component and Subsystem Suppliers
- Semiconductor Equipment Manufacturers
- Technology Solution Providers
- IDMs (Integrated Device Manufacturers) and Foundries
- Chip Designers
- Software Developers
- Third-party Service Providers
- Distributors and Resellers
- Service Providers
- Regulatory Bodies
- Research and Development Institutes
- End Users
Report Objectives
- To define, describe, and forecast the size of the semiconductor manufacturing equipment market, by manufacturing phase, front-end equipment, back-end equipment, end user, and region, in terms of value
- To describe and forecast the size of the semiconductor manufacturing equipment market, by front-end equipment, in terms of volume
- To forecast the market for various segments with respect to the main regions, namely, the Americas; Asia Pacific; and Europe, the Middle East, and Africa (EMEA), in terms of value
- To provide global macroeconomic outlooks
- To provide detailed information regarding the drivers, restraints, opportunities, and challenges influencing the market’s growth
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the total market
- To provide ecosystem analysis, value chain, unmet needs and white spaces, interconnected market and cross-sector opportunities, trends/disruptions impacting customer business, technology analysis, pricing analysis, key stakeholders and buying criteria, case study analysis, trade analysis, patent analysis, Porter’s five forces, key conferences and events, AI impact, impact of 2025 US tariff, and regulations related to the semiconductor manufacturing equipment market
- To analyze the opportunities in the market for stakeholders by identifying high-growth segments and detailing the competitive landscape for market players
- To strategically profile key players and comprehensively analyze their market rankings, core competencies, company valuation, and financial metrics, and product/brand comparison, along with detailing the competitive landscape for the market leaders
- To analyze the competitive strategies, such as equipment launches, expansions, agreements, collaborations, and acquisitions, undertaken by market players
- To benchmark players within the market using the competitive leadership mapping framework, which analyzes market players on various parameters within the broad categories of business strategy excellence and strength of product portfolio
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to the company‘s specific needs. The following customization options are available for the report.
Company Information:
- Detailed analysis and profiling of additional market players (up to five)
Get the Full Semiconductor Manufacturing Equipment Market Report
Full forecast, segment splits, and company analysis for all Semiconductor Manufacturing Equipment Market.
- China Semiconductor Manufacturing Equipment Market
- Japan Semiconductor Manufacturing Equipment Market
- South Korea Semiconductor Manufacturing Equipment Market
- India Semiconductor Manufacturing Equipment Market
- US Semiconductor Manufacturing Equipment Market
- Rest Of Asia Pacific Semiconductor Manufacturing Equipment Market
- Rest Of Americas Semiconductor Manufacturing Equipment Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
