France Heat Transfer Fluids Market (2025-2030)
The France Heat Transfer Fluids Market was valued at $208.8 Million in 2025 and projected to reach to $250 Million by 2030, representing a compound annual growth rate of 3.7%. France's heat transfer fluids market is positioned for steady growth through 2030, supported by robust industrial activity and the country's strategic focus on renewable energy adoption.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
France Heat Transfer Fluids Market Trends and Insights
- France's market growth is driven by increasing demand from industrial heating and cooling applications, particularly in manufacturing, chemical processing, and renewable energy sectors.
- The French market benefits from strong regulatory frameworks promoting energy efficiency and sustainable industrial practices, positioning France as a key player in Europe's heat transfer fluids landscape. The expansion of France's heat transfer fluids market reflects broader trends in industrial modernization and the transition toward high-performance thermal management solutions.
- France's chemical and material processing industries continue to invest in advanced heat transfer systems to optimize operational efficiency and reduce energy consumption.
- Between 2025 and 2030, France is expected to see steady adoption of synthetic and bio-based heat transfer fluids, driven by environmental regulations and corporate sustainability commitments across French manufacturing sectors..
Key Market Statistics
- CAGR (2025-2030) 3.7% CAGR
- Market Size, 2025 ~USD 208.8 Million
- Forecast, 2030 ~USD 250 Million
- Country France
France Heat Transfer Fluids Market Overview
Market Size & Growth :
France's heat transfer fluids market is valued at USD 208.8 million in 2025, with projected growth to USD 250.0 million by 2030, reflecting a steady CAGR of 3.7%.
Industrial Demand Drivers :
Growth is primarily driven by increasing demand from manufacturing, chemical processing, and renewable energy sectors across France, where efficient thermal management is critical.
Renewable Energy Integration :
France's commitment to renewable energy expansion, particularly solar thermal and geothermal applications, is creating new opportunities for specialized heat transfer fluid solutions.
Manufacturing & Chemical Processing :
Strong industrial base in France's manufacturing and chemical sectors continues to drive consistent demand for high-performance heat transfer fluids in production processes.
France Heat Transfer Fluids Market Dynamics
- The market benefits from France's established manufacturing and chemical processing industries, which require reliable thermal management solutions.
- Additionally, government initiatives promoting sustainable energy transitions are accelerating demand for heat transfer fluids in solar thermal and geothermal applications.
- The 3.7% CAGR reflects moderate but consistent expansion, with opportunities emerging from modernization of existing industrial facilities and new renewable energy projects across the country..
Market Ecosystem
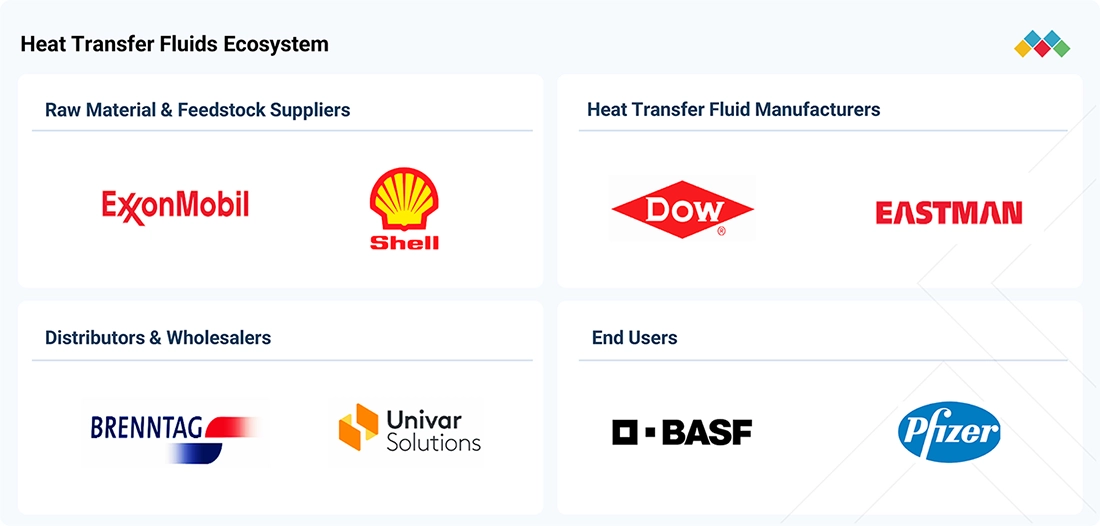
HEAT TRANSFER FLUIDS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Broad HTF portfolio spanning glycol-based and synthetic fluids under the DOWCAL, DOWFROST, DOWTHERM, and SYLTHERM brands. DOWTHERM synthetic fluids (biphenyl/diphenyl oxide and diaryl ethane based) serve high-temperature liquid- and vapor-phase systems up to 400°C across solar power, oil and gas, polymers, and chemicals, while DOWFROST propylene glycol fluids serve HVAC and food-contact cooling loops. | Wide temperature range coverage from a single supplier reduces the need to qualify multiple vendors; DOWTHERM's thermal stability at up to 400°C and DOWFROST's high-purity, low-toxicity formulation extend fluid service life and reduce corrosion, lowering maintenance costs and unplanned downtime. |
 |
Therminol-branded synthetic and mineral-oil heat transfer fluids used in indirect process heating and cooling, spanning non-pressurized moderate-temperature grades (Therminol 55, 59) to high-temperature liquid-phase fluids (Therminol 66, 68) operating up to 360°C, plus vapor-phase and low-temperature pumping grades for combined heating/cooling systems. Widely deployed in petrochemical processing, concentrated solar power, and manufacturing. | Decades of field validation across more than 15,000 installed systems, engineered fouling resistance, and a dedicated fluid-testing and lifecycle-care program that helps operators catch degradation early, extend fluid life, and minimize maintenance-driven downtime. |
 |
Mobiltherm 600 Series heat transfer oils, formulated from highly refined mineral base stocks, used in closed and open, cold-oil-sealed indirect heating and cooling systems across general industrial processes. | Strong resistance to thermal cracking and oxidation supports an extended service life without deposit formation or viscosity increase, while good heat transfer efficiency and pumpability at both start-up and operating temperatures help minimize energy loss and equipment wear. |
 |
Seriola and Gilotherm ranges of mineral and synthetic heat transfer fluids for open and closed thermal-fluid circuits, spanning general industrial mineral oils (Seriola) to alkylbenzene- and aromatic-based synthetic fluids (Seriola AB, Gilotherm GR/TR) for higher-temperature closed-loop systems in plastics, pharma, food and beverage, and chemical manufacturing. | Higher thermal conductivity and oxidation resistance versus standard fluids reduce film thickness and extend oil-drain intervals, cutting maintenance costs, while a dedicated cleaner product (Seriola Cleaner) supports circuit maintenance between fluid changes. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Automotive Advance Technologies
- Battery Electric Vehicle (BEV)
- Light Commercial Vehicles (LCVs)
- Fuel Cell Electric Vehicle (FCEV)
- Hybrid Electric Vehicle (HEV)
- Internal Combustion Engine (ICE)
- BOSCH LIMITED
- Continental ag
- Visteon Corporation
- DENSO Corporation
- ZF FRIEDRICHSHAFEN AG
Bulk Chemicals And Inorganics
- Corrosion Inhibitors
- Glycol Ethers
- Acetic Acid
- Acetone
- Ammonium Nitrate
- Basf se
- DOW CHEMICAL COMPANY
- Exxon Mobil Corporation
- AZELIS HOLDINGS SA
- Sinopec limited
Equipment Machine And Tooling
- Wastewater Treatment
- Air Cooled Heat Exchangers
- Diaphragm Pumps
- Fiberglass
- HVAC System
- Alfa Laval Corporate AB
- Veolia
- Daikin Industries,Ltd.
- Johnson Controls International plc
- Parker-Hannifin Corporation
Key Takeaways
- France's heat transfer fluids market is valued at USD 208.8 million in 2025 and will reach USD 250.0 million by 2030.
- France's market is growing at a CAGR of 3.7%, reflecting steady demand from industrial and renewable energy applications.
- France's regulatory environment and sustainability initiatives are accelerating adoption of advanced thermal management solutions.
- France's chemical processing and manufacturing sectors are primary drivers of heat transfer fluids consumption through 2030.
Heat Transfer Fluids Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | RENEWABLE ENERGY (End-Use Industry) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 4.3% from 2025 to 2030 |
| Largest Segment | LOW TEMPERATURE (Temperature) |
| Market Size Base Year (Billions) | ~USD 5.1 (2025) |
| Revenue Forecast (Billions) | ~USD 6.3 (2030) |
| Segments Covered | Product Type, Temperature, End-Use Industry |
France Heat Transfer Fluids Market Report Segmentation
3 segment dimensions are covered across the global market.
By Product Type
- Glycol-Based Fluids
- Mineral Oils
- Other Product Types
- Synthetic Fluids
By Temperature
- High Temperature
- Low Temperature
- Medium Temperature
- Ultra-High Temperature
By End-Use Industry
- Automotive
- Chemical & Petrochemical
- Chemical & Petrochemicals
- Food & Beverages
- Hvac
- Oil & Gas
- Other End-Use Industries
- Pharmaceuticals
- Renewable Energy
FRANCE: HEAT TRANSFER FLUIDS MARKET, BY END-USE INDUSTRY, 2025–2030
| Segment | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | CAGR (%) |
|---|---|---|---|---|---|---|---|
| AUTOMOTIVE | 14.9 | 15.6 | 16.2 | 16.9 | 17.7 | 18.5 | 4.3 |
| CHEMICAL & PETROCHEMICAL | 54.6 | 55.8 | 57.1 | 58.4 | 59.9 | 61.2 | 2.3 |
| FOOD & BEVERAGES | 17.6 | 18.2 | 18.9 | 19.6 | 20.3 | 21 | 3.6 |
| HVAC | 19.7 | 20.5 | 21.4 | 22.3 | 23.4 | 24.4 | 4.4 |
| OIL & GAS | 40.9 | 42.4 | 44 | 45.7 | 47.5 | 49.3 | 3.8 |
| OTHER END-USE INDUSTRIES | 18.2 | 18.8 | 19.4 | 20.1 | 20.7 | 21.3 | 3.2 |
| PHARMACEUTICALS | 24.2 | 25.3 | 26.5 | 27.8 | 29.2 | 30.6 | 4.8 |
| RENEWABLE ENERGY | 18.7 | 19.5 | 20.5 | 21.5 | 22.6 | 23.7 | 4.9 |
| TOTAL | 208.8 | 216.2 | 224 | 232.4 | 241.3 | 250 | 3.7 |
Target Audience
- Heat Transfer Fluid Manufacturers : Manufacturers need France-specific market data to assess market potential, identify growth segments, and develop localized product strategies for industrial and renewable applications.
- Industrial Equipment Suppliers : Equipment suppliers require detailed demand insights from French manufacturing and chemical sectors to align product offerings with regional thermal management requirements.
- Renewable Energy Companies : Solar thermal and geothermal operators need market intelligence on heat transfer fluid demand in France's expanding renewable energy sector for project planning.
- Chemical & Manufacturing Facilities : Industrial operators require market analysis to benchmark fluid specifications, identify supplier options, and optimize thermal management investments in France.
- Investment & Strategy Consultants : Consultants advising on French industrial investments need comprehensive market data to support due diligence, feasibility studies, and strategic recommendations.
Key Companies in the France Heat Transfer Fluids Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| PETROBRAS | Brazil | Public Company | |
| DOW | United States | Public Company | |
| EASTMAN CHEMICAL COMPANY | United States | Public Company | |
| EXXON MOBIL CORPORATION | United States | Public Company | |
| CHEVRON CORPORATION | United States | Public Company | |
| HUNTSMAN CORPORATION | United States | Public Company | |
| SHELL PLC | United Kingdom | Public Company | |
| LANXESS | Germany | Public Company | |
| CLARIANT | Switzerland | Public Company | |
| WACKER CHEMIE AG | Germany | Public Company | |
| INDIAN OIL CORPORATION LTD. | India | Public Company | |
| ARKEMA | France | Public Company | |
| BASF SE | Germany | Public Company |
PETROBRAS
Petrobras is a Brazilian public company founded in 1953 that operates as a major integrated energy company. With 43,199 employees, it is one of the largest oil and gas producers in the world.
DOW
Dow is a United States-based public company founded in 1897 with 34,600 employees. It is a leading global provider of chemical, plastic, and agricultural products.
EASTMAN CHEMICAL COMPANY
Eastman Chemical Company is a United States public company founded in 1920 with 13,000 employees. It manufactures and markets a broad range of chemicals, fibers, and plastics.
EXXON MOBIL CORPORATION
Exxon Mobil Corporation is a United States public company founded in 1870 with 57,900 employees. It is one of the world's largest integrated oil and gas companies.
CHEVRON CORPORATION
Chevron Corporation is a United States public company founded in 1879 with 43,039 employees. It is a major global energy company engaged in oil and gas exploration, production, and refining.
HUNTSMAN CORPORATION
Huntsman Corporation is a United States public company founded in 1970 with 6,000 employees. It manufactures and markets specialty chemicals and materials for various industrial applications.
SHELL PLC
Shell PLC is a United Kingdom-based public company founded in 1897 with 84,000 employees. It is one of the world's largest integrated oil and gas companies.
LANXESS
Lanxess is a German public company founded in 1863 with 11,630 employees. It is a specialty chemicals manufacturer serving diverse industries including automotive, construction, and consumer goods.
CLARIANT
Clariant is a Swiss public company founded in 1886 with 9,998 employees. It is a specialty chemicals manufacturer providing solutions for various industrial and consumer applications.
WACKER CHEMIE AG
Wacker Chemie AG is a German public company founded in 1914 with 16,196 employees. It produces chemical products including silicones, polymers, and fine chemicals for industrial applications.
INDIAN OIL CORPORATION LTD.
Indian Oil Corporation Ltd. is an Indian public company founded in 1959 with 29,941 employees. It is one of India's largest integrated oil and gas companies.
ARKEMA
Arkema is a French public company founded in 2003 with 20,700 employees. It is a specialty chemicals and advanced materials manufacturer serving industrial and consumer markets.
BASF SE
BASF SE is a German public company founded in 1865 with 106,428 employees. It is the world's largest chemical producer, offering a comprehensive portfolio of chemicals, plastics, and agricultural products.
Reasons to Buy this Report
- Market Size & Valuation Data : Access precise market valuation for France at USD 208.8 million (2025) with detailed forecasts through 2030, enabling accurate budgeting and investment planning.
- Growth Trajectory & CAGR Analysis : Understand France's 3.7% CAGR performance relative to global 4.3% growth, identifying market maturity levels and competitive positioning opportunities.
- Sector-Specific Demand Insights : Gain detailed intelligence on demand drivers across French manufacturing, chemical processing, and renewable energy sectors to target high-growth applications.
- Competitive Landscape Intelligence : Develop France-specific go-to-market strategies with insights into industrial demand patterns, regulatory environment, and regional market dynamics.
- Investment & Expansion Planning : Make informed decisions on market entry, capacity expansion, or product development in France with comprehensive market sizing and growth forecasts.
Frequently asked questions
What is the current size of France's heat transfer fluids market?
France's heat transfer fluids market is estimated at USD 208.8 million in 2025.
What is the projected market size for France by 2030?
France's heat transfer fluids market is projected to reach USD 250.0 million by 2030.
What is the CAGR for France's heat transfer fluids market?
France's heat transfer fluids market is expected to grow at a CAGR of 3.7% from 2025 to 2030.
Which industries drive demand for heat transfer fluids in France?
France's primary demand drivers include chemical processing, manufacturing, renewable energy, and industrial heating and cooling applications.
What factors influence France's heat transfer fluids market growth?
France's market growth is influenced by regulatory frameworks promoting energy efficiency, sustainability commitments, industrial modernization, and the transition to synthetic and bio-based fluids.
RESEARCH METHODOLOGY
The study involved four major activities in estimating the size of the heat transfer fluids market. Exhaustive secondary research was done to collect information on the market, the peer market, and the parent market. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. Thereafter, the market breakdown and data triangulation procedures were used to estimate the market size of the segments and subsegments.
Secondary Research
In the secondary research process, various secondary sources have been referred to for identifying and collecting information for this study. These secondary sources include annual reports, press releases, investor presentations of companies, white papers, certified publications, trade directories, certified publications, articles from recognized authors, gold standard and silver standard websites, and databases.
Secondary research has been used to obtain key information about the value chain of the industry, monetary chain of the market, the total pool of key heat transfer fluids players, market classification and segmentation according to industry trends to the bottom-most level, and regional markets. It was also used to obtain information about the key developments from a market-oriented perspective.
Primary Research
The heat transfer fluids market comprises several stakeholders in the value chain, which include raw material suppliers, manufacturers, distributors, and end users. Various primary sources from the supply and demand sides of the heat transfer fluids market have been interviewed to obtain qualitative and quantitative information. The primary interviewees from the demand side include key opinion leaders in application sectors. The primary sources from the supply side include manufacturers, associations, and institutions involved in the heat transfer fluids industry.
Primary interviews were conducted to gather insights such as market statistics, data on revenue collected from the products and services, market breakdowns, market size estimations, market forecasting, and data triangulation. Primary research also helped in understanding the various trends related to temperature range, product type, application, end-use industry, and region. Stakeholders from the demand side, such as CIOs, CTOs, and CSOs, were interviewed to understand the buyer’s perspective on the suppliers, products, component providers, and their current usage of heat transfer fluids and future outlook of their business, which will affect the overall market.
The breakdown of profiles of the primary interviewees is illustrated in the figure below:
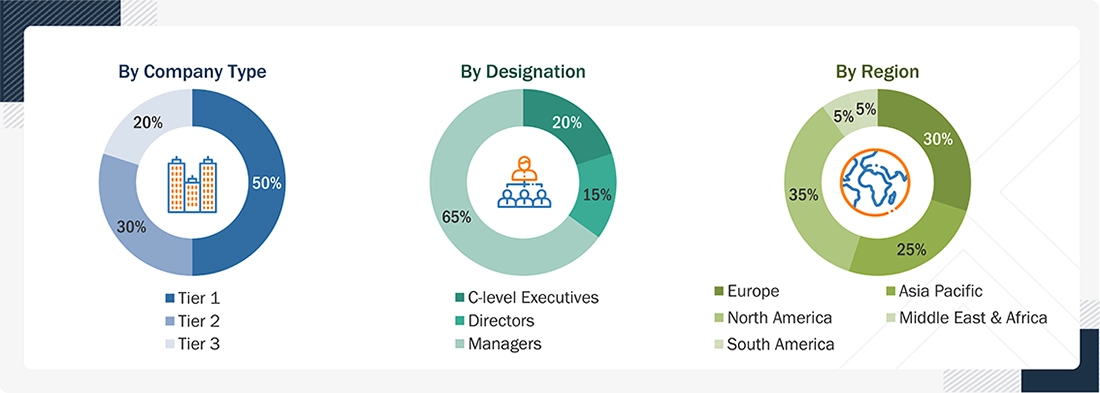
Note: Tier 1, Tier 2, and Tier 3 companies are classified based on their market revenue in 2025 available in the public domain, product portfolios, and geographical presence.
Other designations include sales representatives, production heads, and technicians.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
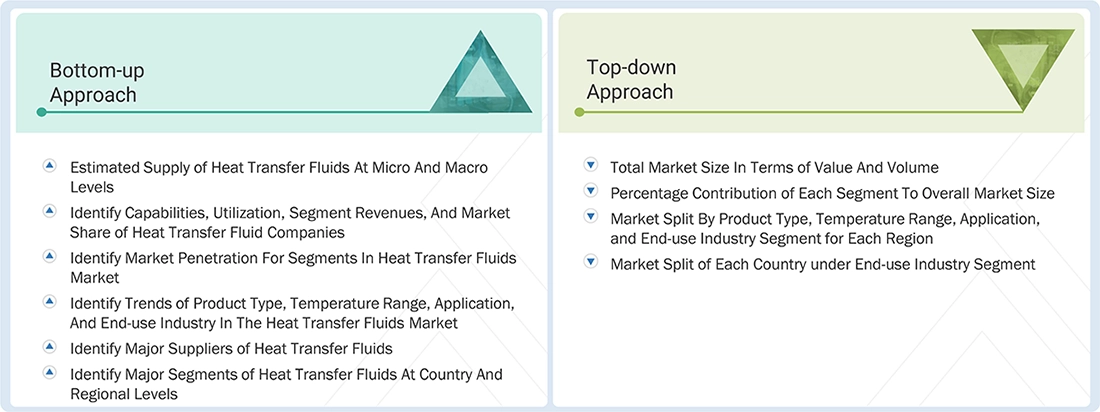
- The top-down approach was used to estimate and validate the size of various submarkets for heat transfer fluids for each region. The research methodology used to estimate the market size included the following steps:
- The key players in the industry have been identified through extensive secondary research.
- The supply chain of the industry has been determined through primary and secondary research.
- The global market was then segmented into five major regions and validated by industry experts.
- All percentage shares, splits, and breakdowns based on temperature range, product type, application, end-use industry, and region were determined using secondary sources and verified through primary sources.
- All possible parameters that affect the markets covered in this research study were accounted for, viewed in extensive detail, verified through primary research, and analyzed to get the final quantitative and qualitative data. This data was consolidated and added with detailed inputs and analysis and presented in this report
Data Triangulation
After arriving at the total market size from the estimation process for heat transfer fluids above, the overall market has been split into several segments and sub-segments. To complete the overall market engineering process and arrive at the exact statistics for all the segments and sub-segments, the data triangulation and market breakdown procedures have been employed, wherever applicable. The data has been triangulated by studying various factors and trends from both the demand and supply sides. Along with this, the market size has been validated by using both the top-down and bottom-up approaches and primary interviews. Hence, for every data segment, there have been three sources—top-down approach, bottom-up approach, and expert interviews. The data was assumed correct when the values arrived from the three sources matched.
Market Definition
The heat transfer fluids market comprises fluids engineered to transfer, distribute, and regulate thermal energy between heat sources and heat-consuming equipment across industrial and commercial applications. The market includes mineral and petroleum-based oils, synthetic fluids and silicones, glycol-based fluids, inorganic molten salts, and other specialized thermal media operating across sub-zero, moderate, high, and ultra-high temperature ranges. These fluids are utilized in industrial process heating, thermal energy storage, chilled and hot water loops, dynamic process temperature control, cryogenic & low-temperature processing, power generation and waste heat recovery, thermal management, and other applications. Key end-use industries include chemical & petrochemicals, plastics & polymer processing, oil & gas, automotive, electronics & data centers, food & beverage, pharmaceuticals, renewable energy, HVAC, and other end-use industries. The market encompasses fluid manufacturing, formulation, supply, and application-specific thermal management solutions.
Key Stakeholders
- Heat transfer fluids manufacturers
- Heat transfer fluids traders, distributors, and suppliers
- Raw material suppliers
- Government and private research organizations
- Associations and industrial bodies
- R&D institutions
- Environmental support agencies
Report Objectives
- To define, describe, and forecast the size of the heat transfer fluids market, in terms of value and volume
- To provide detailed information regarding the major factors (drivers, opportunities, restraints, and challenges) influencing the growth of the market
- To estimate and forecast the market size based on temperature range, product type, application, end-use industry, and region
- To forecast the size of the market with respect to major regions, namely, Europe, North America, Asia Pacific, Middle East & Africa and South America, along with their key countries
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and their contribution to the overall market
- To analyze opportunities in the market for stakeholders and provide a competitive landscape of market leaders
- To track and analyze recent developments such as product launches, collaborations, contracts, acquisitions, and expansions in the market
- To strategically profile key market players and comprehensively analyze their core competencies
Available customizations:
Along with the given market data, MarketsandMarkets offers customizations according to the company’s specific needs. The following customization options are available for the report:
Regional Analysis
- Further breakdown of a region with respect to a particular country or additional application/ end-use industry
Company Information
- Detailed analysis and profiles of additional market players
Tariff & Regulations
- Regulations and impact on the heat transfer fluids market
Get the Full Heat Transfer Fluids Market Report
Full forecast, segment splits, and company analysis for all Heat Transfer Fluids Market.
- China Heat Transfer Fluids Market
- Japan Heat Transfer Fluids Market
- India Heat Transfer Fluids Market
- South Korea Heat Transfer Fluids Market
- Canada Heat Transfer Fluids Market
- Mexico Heat Transfer Fluids Market
- US Heat Transfer Fluids Market
- Germany Heat Transfer Fluids Market
- Italy Heat Transfer Fluids Market
- UK Heat Transfer Fluids Market
- Spain Heat Transfer Fluids Market
- UAE Heat Transfer Fluids Market
- Saudi Arabia Heat Transfer Fluids Market
- South Africa Heat Transfer Fluids Market
- Argentina Heat Transfer Fluids Market
- Brazil Heat Transfer Fluids Market
- South America Heat Transfer Fluids Market
- Rest Of Europe Heat Transfer Fluids Market
- Rest Of Asia Pacific Heat Transfer Fluids Market
- GCC Countries Heat Transfer Fluids Market
- –Rest Of GCC Countries Heat Transfer Fluids Market
- Rest Of South America Heat Transfer Fluids Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report