


Precision Farming Market Size, Share & Trends
Report Code
SE 2831
Published in
Sep, 2026, By MarketsandMarkets™
Precision Farming Market by Automation & Control Systems, Cloud-based Software, System Integration & Consulting Services, Guidance Technology, Variable Rate Technology, Yield Monitoring, Field Mapping, Variable Rate Application - Global Forecast to 2033

USD 23.07 BN
MARKET SIZE, 2033

CAGR 9.8%
(2026-2033)

298
REPORT PAGES

242
MARKET TABLES
OVERVIEW

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The precision farming market worldwide will expand from USD 11.97 billion in 2026 to USD 23.07 billion by 2033, at a CAGR of 9.8%. The market expansion results from technological progress that supports data-based efficient farming, rising interest in sustainable agriculture, and government backing of agricultural initiatives. The market experiences additional growth because of data analytics adoption, variable rate application (VRA) techniques, and nanotechnology advancements. The market experiences rapid acceleration because of global digital transformation initiatives and IoT and AI integration with the existing factors, enabling smarter decision-making, resource optimization, and improved long-term agricultural productivity.
KEY TAKEAWAYS
-
BY OFFERINGHardware holds a share of 68.7% of the precision farming market in 2025 because it forms the foundation for data collection and automation, with widespread adoption of sensors, GPS devices, drones, and automated machinery driving real-time monitoring, field mapping, and efficient farm operations.
-
BY TECHNOLOGYGuidance technology led the precision farming market by accounting for 40.0% in 2025 as GPS- and GNSS-based systems enable accurate field navigation, reduce overlaps and input waste, and enhance operational efficiency across planting, spraying, and harvesting activities.
-
BY APPLICATIONYield monitoring held the largest market share of 25.3% in 2025 because it provides farmers with real-time insights into crop performance, enabling data-driven decisions to optimize inputs, improve yield quality, and maximize overall farm productivity.
-
BY REGIONNorth America holds the largest share of the precision farming market due to its advanced adoption of smart agricultural technologies, strong government support for sustainable farming, and high investment in precision equipment and IoT-based solutions.
-
COMPETITIVE LANDSCAPE - Key PlayersMajor market players have adopted both organic and inorganic strategies, including partnerships and investments. For instance, Deere & Company, AGCO Corporation, CNH Industrial N.V., KUBOTA Corporation, TOPCON CORPORATION have entered into a number of agreements and partnerships to cater to the growing demand for aerospace materials across innovative applications.
-
COMPETITIVE LANDSCAPE - Startups/SMEsDICKEY-john and GAMAYA, among others, have distinguished themselves among startups and SMEs by securing strong footholds in specialized niche areas, underscoring their potential as emerging market leaders in the precision farming market.
A major future opportunity in the precision farming market lies in the integration of advanced technologies such as artificial intelligence (AI), machine learning (ML), and data analytics to enable predictive and autonomous farm management. As the volume of data from IoT sensors, drones, and satellite imagery continues to expand, AI-driven insights can optimize irrigation, fertilization, pest management, and yield forecasting with unprecedented accuracy. This transition toward data-driven and automated decision-making will enhance productivity, reduce input costs, and promote sustainable resource utilization. Furthermore, the rising adoption of autonomous tractors, robotics, and cloud-based farm management platforms supported by 5G connectivity and government initiatives promoting digital agriculture will create significant growth opportunities and redefine the future of modern farming practices.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
Core technologies such as drones, irrigation controllers, GPS, flow and application control devices, guidance and steering systems, handheld mobile devices, and sensors are central to the precision farming ecosystem. These technologies are widely used in applications including dairy and livestock management, field farming, harvest and inventory management, soil and irrigation management, pruning, and weather monitoring. Automation and control systems are increasingly leading the way in automating field operations such as crop scouting, planting, tilling, spraying, and weeding. Agricultural software plays a vital role, offering modules for crop protection, environmental monitoring, waste and pollution management, landscape and soil care, and crop nutrition optimization. With advancements in AI, IoT, blockchain, and cloud services, software adoption is accelerating, creating lucrative opportunities for providers to deliver solutions that enhance operational efficiency, energy use, and accessibility. The market opportunity is expanding beyond precision hardware toward AI-enabled decision support, autonomous and assisted machinery, connected farm-data platforms, remote sensing, and recurring software and services, with value increasingly linked to measurable improvements in productivity, input efficiency, labor utilization, and sustainability.

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Drivers
Impact
Level
Level
-
Inclination Toward Data-driven and Efficient Farming due to Technological Advancements

-
Growing Emphasis on Sustainable Agricultural Practices


RESTRAINTS
Impact
Level
Level
-
High Initial Investment and Technology Costs

-
Lack of Technical Know-how and Skilled Workforce


OPPORTUNITIES
Impact
Level
Level
-
Growth Potential of Variable-rate Application (VRA) in Precision Farming

-
Adoption of Data Analytics in the Agriculture Sector


CHALLENGES
Impact
Level
Level
-
Lack of Standardized Policies and Regulations

-
Data Privacy Issues and Security Concerns

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Growing emphasis on sustainable agricultural practices
The growing emphasis on sustainable agriculture is driving the adoption of precision farming. By using soil sensors, satellite imagery, and data analytics, precision farming enables efficient use of water, fertilizers, and pesticides, reducing waste and environmental impact while improving yields. Global initiatives, such as government-backed natural farming clusters in India and international programs by FAO and IFAD, further promote eco-friendly farming, positioning precision agriculture as a key tool for achieving scalable and measurable sustainability goals.
Restraint: High initial investment and technology costs
High initial investments and technology costs limit the adoption of precision farming. Advanced tools such as GPS-guided machinery, soil sensors, and data analytics platforms require significant spending for purchase, installation, and maintenance, making them inaccessible for small and marginal farmers, especially in developing regions. Coupled with limited financing, subsidies, and technical knowledge, these high costs act as a major barrier to widespread adoption despite the long-term benefits of improved yields, resource efficiency, and sustainability.
Opportunity: Growth potential of variable rate application (VRA) in precision farming
Variable rate application (VRA) presents significant growth potential in precision farming by enabling farmers to optimize inputs such as fertilizers, pesticides, and water based on specific field conditions. This precision boosts yields, reduces costs and waste, and promotes sustainability. Key industry players, including Deere & Company, Hexagon AB, and Valmont Industries, are advancing VRA technologies through smart machinery, digital tools, and irrigation systems, highlighting its role in driving efficient, sustainable, and future-ready farming practices.
Challenge: Lack of standardized policies and regulations
The lack of standardized policies and regulations poses a major challenge for precision agriculture. Non-uniform rules create interoperability issues between equipment and systems from different manufacturers, leading to inefficiencies, higher operational costs, and delayed innovation. Without consistent regulatory frameworks, technology integration is hindered, limiting the productivity and sustainability benefits of precision farming. Initiatives such as the US GAO’s 2024 recommendations for technical standards and funding support aim to address these issues and promote a more efficient, integrated agricultural ecosystem.
PRECISION FARMING MARKET SIZE, SHARE & TRENDS: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Integration of GPS-guided autonomous tractors and real-time data analytics through the John Deere Operations Center platform | Enhances planting accuracy, optimizes input use, reduces labor dependency, and increases overall yield efficiency |
 |
Deployment of precision farming and variable rate application technologies via Fendt and Massey Ferguson machinery | Reduces seed and fertilizer wastage, improves field uniformity, and boosts crop productivity |
 |
Use of AFS (Advanced Farming Systems) for automated steering, yield mapping, and field data integration across Case IH and New Holland brands | Improves resource utilization, minimizes overlaps, reduces fuel consumption, and enhances farm profitability |
 |
Implementation of smart tractors and remote farm monitoring systems integrated with IoT sensors and GNSS-based guidance | Increases operational precision, lowers input costs, and supports sustainable farming practices |
 |
Development of GNSS-based precision guidance systems, crop health monitoring, and machine control solutions | Provides centimeter-level accuracy, enhances operational efficiency, and ensures data-driven decision-making in farm management |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
The precision farming ecosystem comprises R&D institutes and universities, hardware component providers, software providers, and precision farming OEMs, with each participant contributing to the development, integration, and commercialization of precision agriculture solutions. R&D institutions and laboratories support technology development, field research, robotics, and agronomic innovation, while hardware component providers supply sensing, imaging, positioning, machinery, and other equipment that enable data collection and precision operations. Software providers complement these technologies with farm-management platforms, field analytics, mapping, connectivity, and decision-support capabilities. Precision farming OEMs integrate hardware, software, and machinery into end-to-end solutions covering guidance, variable-rate application, autonomous operations, livestock management, and farm productivity. Collaboration across these ecosystem participants is accelerating the integration of connected technologies, automation, and data-driven decision-making, while enabling farmers to improve input efficiency, productivity, and resource utilization.

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Precision Farming Market, By Offering
The software segment in the precision farming market is expected to record the highest CAGR during 2026–2033 due to the increasing reliance on data-driven farming practices. Farmers are increasingly using software to monitor crop health, optimize irrigation, manage inputs, and predict yields with high accuracy. The integration of IoT devices, sensors, drones, and satellite imagery generates massive volumes of data that require advanced software for real-time analysis and actionable insights. Additionally, cloud-based platforms and mobile applications enable remote farm management and scalability, making software adoption more flexible and cost-effective than hardware upgrades. Industry trends, such as the push for sustainability, government-backed digital farming initiatives, and partnerships between agri-tech companies and software providers, further accelerate market growth, positioning software as a critical driver for precision agriculture modernization.
Precision Farming Market, By Technology
Variable-rate Technology (VRA) is expected to register the highest CAGR in the precision farming market due to its ability to optimize the application of inputs such as fertilizers, pesticides, seeds, and water based on real-time field variability. By adjusting input rates to the specific needs of different soil zones and crops, VRA enhances yield, reduces input costs, and minimizes environmental impact. The increasing adoption of IoT sensors, GPS-enabled equipment, and advanced analytics platforms supports the scalability and accuracy of VRA. Furthermore, rising demand for sustainable and resource-efficient farming, coupled with partnerships between equipment manufacturers and digital solution providers (e.g., Deere & Company, Valmont Industries), drives rapid deployment of VRA systems, making it a key growth area in precision agriculture technology.
Precision Farming Market, By Application
Weather tracking and forecasting applications are expected to record the highest CAGR in the precision farming market because climate variability and extreme weather events increasingly impact crop productivity and farm profitability. Advanced weather monitoring tools, combined with AI-driven predictive models, provide farmers with real-time insights on rainfall, temperature, humidity, and frost risk, enabling proactive decision-making. These systems help optimize irrigation schedules, planting and harvesting times, and crop protection strategies, reducing losses and improving resource efficiency. Additionally, integration with IoT devices, drones, and cloud-based platforms allows seamless data collection and analysis, supporting scalable and precise farm management. Growing awareness of climate-smart agriculture and government-backed initiatives further accelerates the adoption of weather tracking and forecasting solutions in precision farming.
REGION
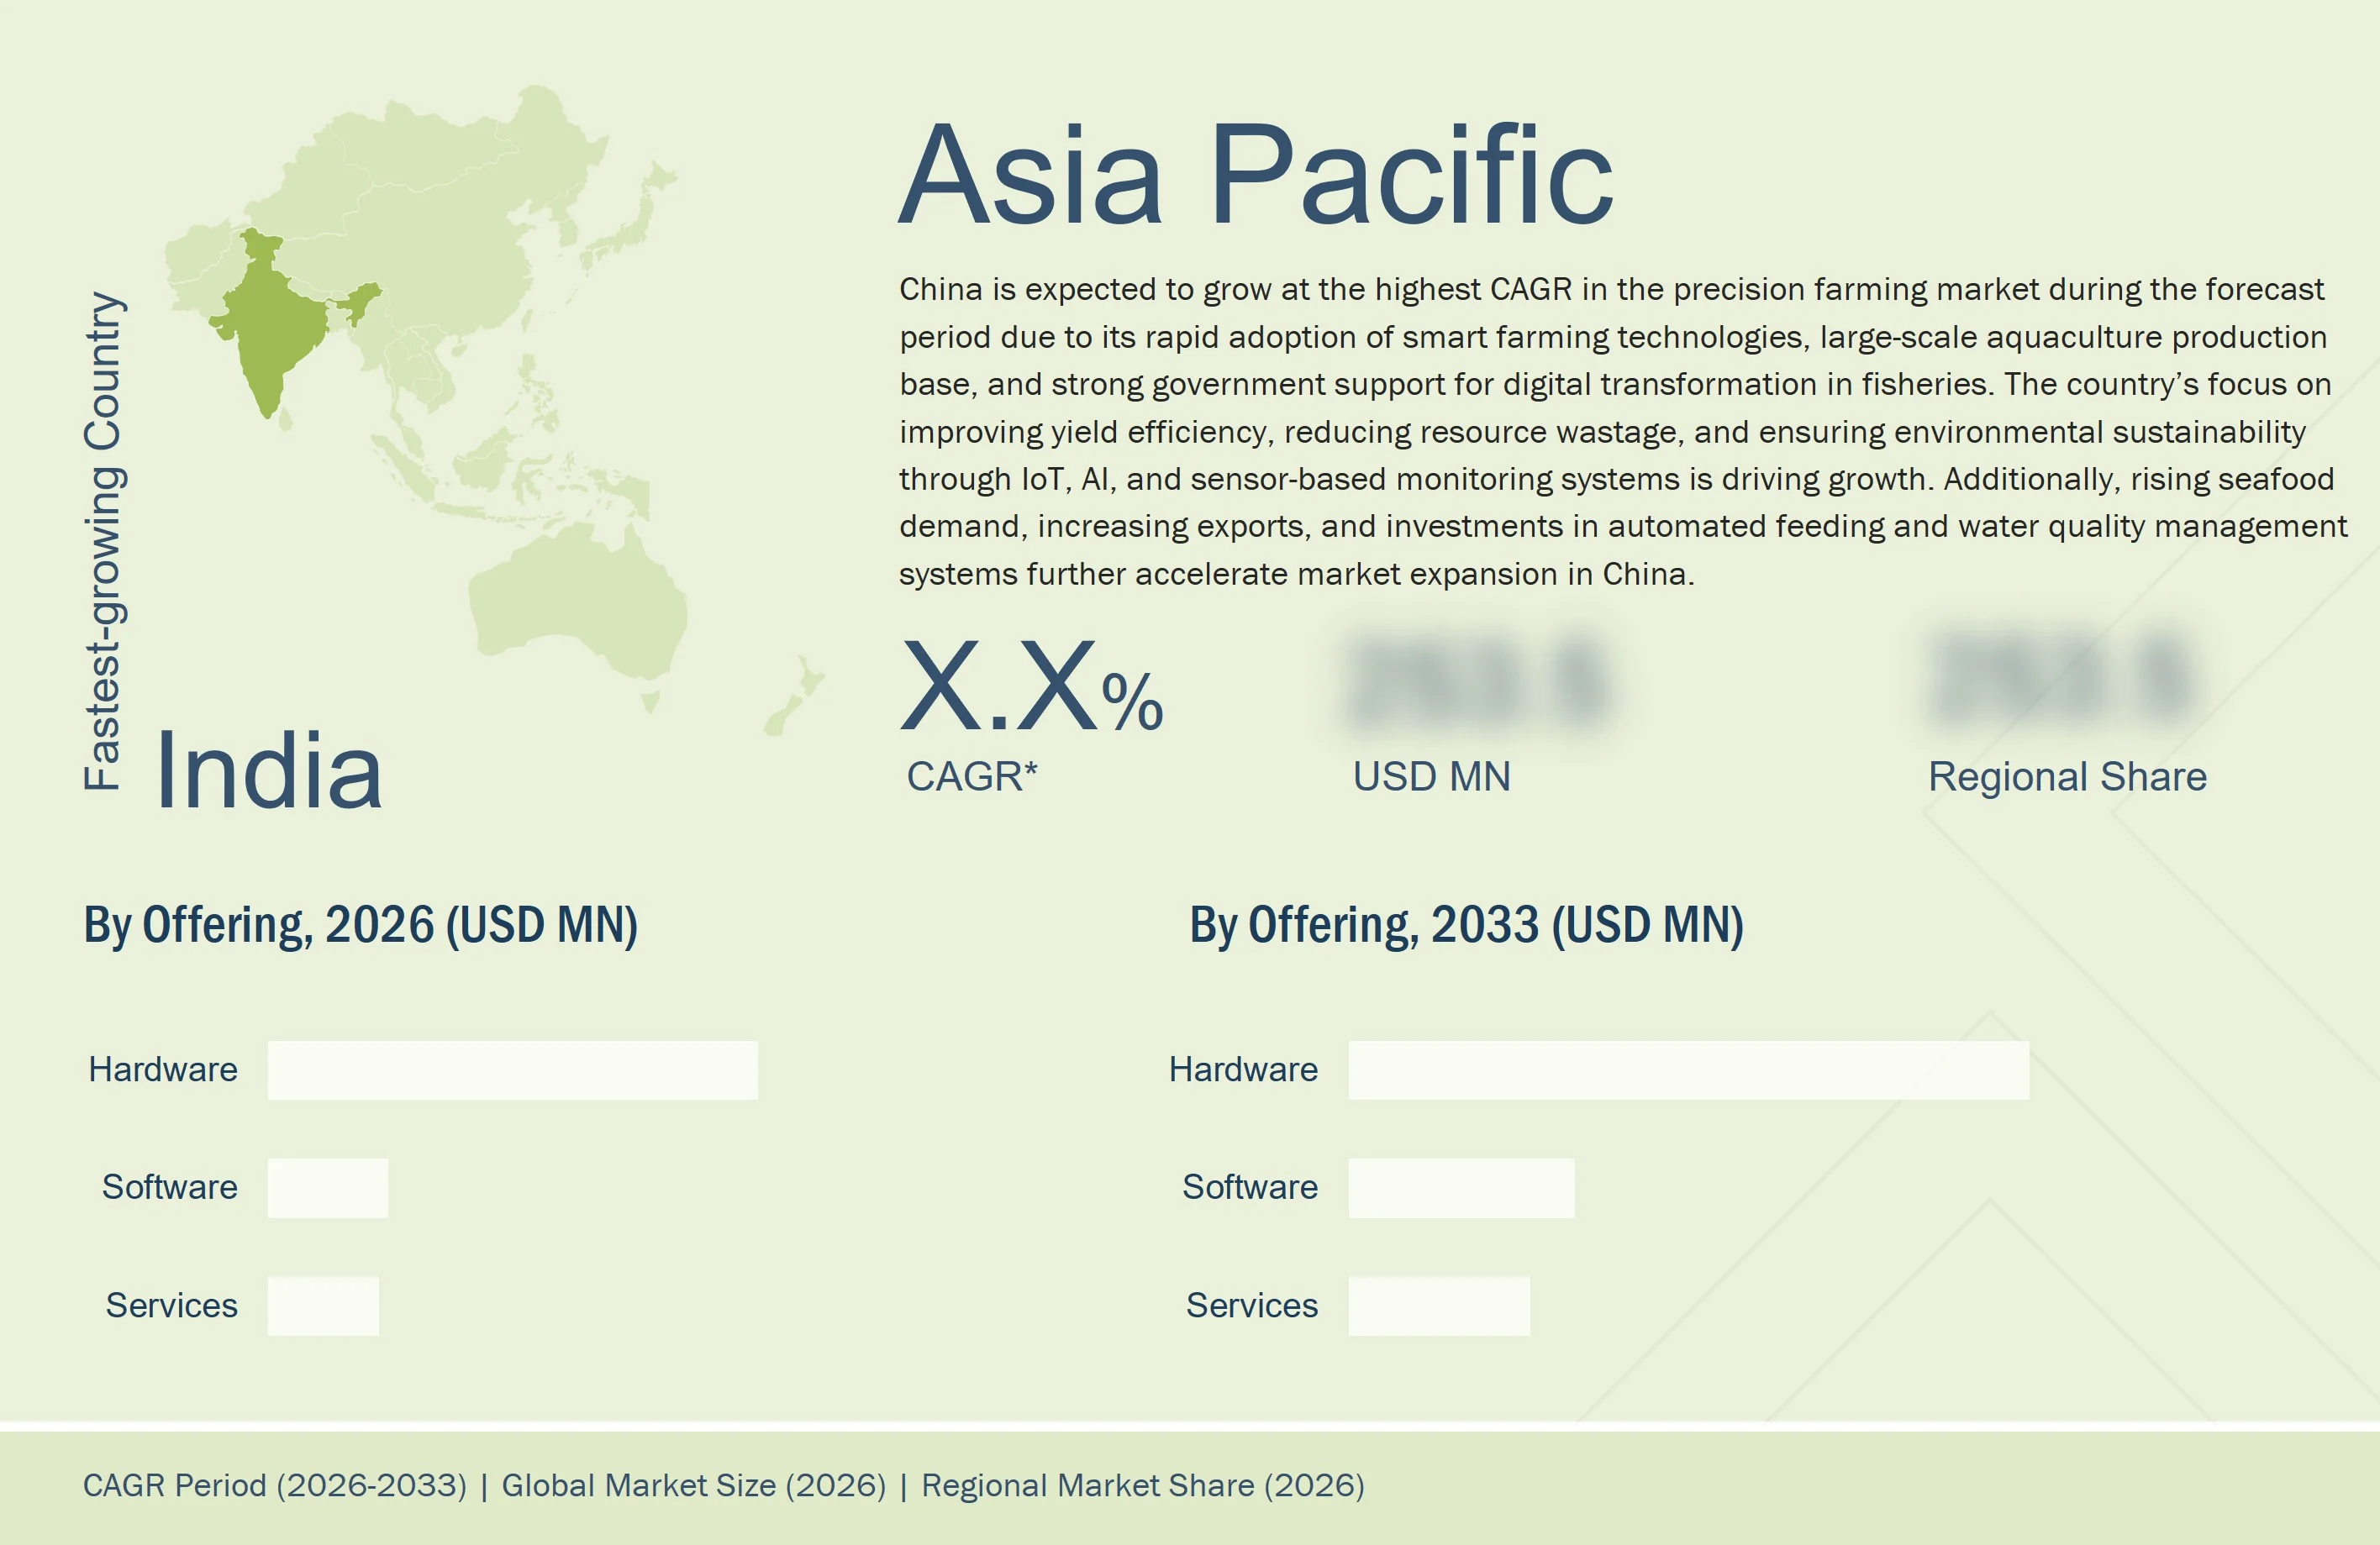
Asia Pacific to be the fastest-growing region in global precision farming market during forecast period
Asia Pacific is expected to record the highest CAGR in the precision farming market due to increasing adoption of smart agricultural technologies, rising government support for sustainable farming, and rapid modernization of agriculture in countries such as China, India, Japan, and Australia. The region faces growing food demand from its expanding population, driving the need for higher productivity and efficient resource management. Investments in IoT-based solutions, AI-driven farm management software, and precision machinery are accelerating, supported by favorable policies, subsidies, and initiatives promoting digital agriculture. Additionally, rising awareness of climate-resilient and environmentally sustainable practices encourages farmers to adopt precision farming technologies, positioning Asia Pacific as the fastest-growing regional market.
PRECISION FARMING MARKET SIZE, SHARE & TRENDS: COMPANY EVALUATION MATRIX
In the precision farming market matrix, Deere & Company (Star) leads with a robust market share and a comprehensive product footprint, stemming from its well-established brand, expansive solution suite, and global customer base, which make its advanced technologies widely adopted across geographies. TELUS (Emerging Leader) is gaining significant visibility due to its innovative connected agriculture offerings and strategic investments, allowing it to rapidly expand its market presence and capture emerging opportunities. While Deere & Company dominates through scale and trusted technology, TELUS is well-positioned to move further toward the leaders’ quadrant as demand for digital and data-driven farming solutions accelerates.

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Deere & Company (US)
- AGCO Corporation (US)
- CNH Industrial N.V. (Netherlands)
- Ag Leader Technology (US)
- AgEagle Aerial Systems Inc (US)
- Topcon Corporation (Japan)
- Bayer AG (Climate LLC.) (Germany)
- TeeJet Technologies (US)
- Hexagon AB (Sweden)
- Kubota Corporation (Japan)
- Trimble Inc. (US)
- Abaco S.p.A. (Italy)
- Cropx Inc. (Israel)
- Farmers Edge Inc. (Canada)
- Grownetics (US)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2026 (Value) | USD 11.97 BN |
| Market Forecast in 2033 (Value) | USD 23.07 BN |
| Growth Rate | CAGR of 9.8% from 2026-2033 |
| Years Considered | 2022-2033 |
| Base Year | 2025 |
| Forecast Period | 2026-2033 |
| Units Considered | Value (USD Million/Billion), Volume (Thousand Units) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends. |
| Segments Covered |
|
| Regions Covered | North America, Europe, Asia Pacific, and RoW |
WHAT IS IN IT FOR YOU: PRECISION FARMING MARKET SIZE, SHARE & TRENDS REPORT CONTENT GUIDE

DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Large Agribusiness |
|
|
| Equipment Manufacturer |
|
|
| Technology Vendor |
|
|
| Farm Cooperative |
|
|
| Food Processor |
|
|
RECENT DEVELOPMENTS
- February 2026 : In February 2026, Topcon Agriculture expanded the territory of Precision Ag Solved (PAS), a primary distributor of Topcon's precision agriculture portfolio, into Western Canada. The expanded territory covers British Columbia, Alberta, Saskatchewan, and Manitoba. PAS provides Topcon precision agriculture technologies through its distribution network while also maintaining inventory, service parts, and technical training for precision agriculture resellers. The expansion increases farmer access to Topcon's precision guidance, positioning, and agricultural technology.
- May 2025 : The partnership between CNH Industrial N.V. and Starlink enabled satellite internet access to farmers in distant areas, which improved precision farming technologies through autonomous tractors and AI-driven weed detection by utilizing Starlink's 7,000+ satellite network for real-time data and cloud operations.
- March 2025 : Deere & Company introduced SmartDetect Digital, a safety system for mid-size and large wheel loaders, which uses stereo cameras and machine learning to detect people and objects, alert operators in real-time, and integrate with the John Deere Operations Center for near-miss notifications and weekly reports.
- February 2025 : Ag Leader Technology introduced RightPath as a passive implement steering system that used the tractor's guidance line to guide farming equipment while improving input accuracy, reducing crop damage and operator fatigue, and supporting multiple GPS correction sources.
- February 2025 : Topcon Agriculture (Topcon Corporation) collaborated with Bonsai Robotics to enhance precision farming for permanent crops through the combination of Bonsai's vision-based autonomous navigation with Topcon's autosteering and telematics systems for automated operations, data-driven choices, and precise harvesting capabilities.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
TITLE
PAGE NO
1
INTRODUCTION
29
2
EXECUTIVE SUMMARY
35
3
PREMIUM INSIGHTS
39
4
MARKET OVERVIEW
Smart agriculture's growth hinges on AI, sustainability, and overcoming tech cost barriers.
42
4.1
INTRODUCTION
4.2
MARKET DYNAMICS
4.2.1
DRIVERS
4.2.1.1
INCREASING DEPLOYMENT OF AUTONOMOUS MACHINERY AND AI-ENABLED SOLUTIONS
4.2.1.2
GROWING EMPHASIS ON SUSTAINABLE AGRICULTURAL PRACTICES
4.2.1.3
INCREASING GOVERNMENT SUPPORT FOR SMART AGRICULTURE
4.2.2
RESTRAINTS
4.2.2.1
HIGH INITIAL INVESTMENT AND TECHNOLOGY COSTS
4.2.2.2
LACK OF TECHNICAL KNOWLEDGE AND SHORTAGE OF SKILLED WORKFORCE
4.2.3
OPPORTUNITIES
4.2.3.1
GROWING INTEGRATION OF VRA FOR SITE-SPECIFIC INPUT MANAGEMENT
4.2.3.2
INCREASING USE OF ADVANCED ANALYTICS TO OPTIMIZE FARM-LEVEL DECISION-MAKING
4.2.3.3
RAPID ADVANCEMENTS IN NANOTECHNOLOGY FOR PRECISION AGRICULTURE
4.2.4
CHALLENGES
4.2.4.1
LACK OF STANDARDIZED POLICIES AND REGULATIONS
4.2.4.2
DATA PRIVACY ISSUES AND SECURITY CONCERNS
4.2.4.3
LIMITED DIGITAL INFRASTRUCTURE IN RURAL AREAS
4.3
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
4.3.1
INTERCONNECTED MARKETS
4.3.2
CROSS-SECTOR OPPORTUNITIES
4.4
STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
5
INDUSTRY TRENDS
Navigate competitive forces and macroeconomic shifts transforming global precision agriculture markets.
52
5.1
INTRODUCTION
5.2
PORTER'S FIVE FORCE ANALYSIS
5.2.1
INTENSITY OF COMPETITIVE RIVALRY
5.2.2
THREAT OF SUBSTITUTES
5.2.3
BARGAINING POWER OF BUYERS
5.2.4
BARGAINING POWER OF SUPPLIERS
5.2.5
THREAT OF NEW ENTRANTS
5.3
MACROECONOMIC OUTLOOK
5.3.1
INTRODUCTION
5.3.2
GDP TRENDS AND FORECAST
5.3.3
TRENDS IN GLOBAL AGRICULTURAL MACHINERY MARKET
5.3.4
TRENDS IN GLOBAL AGRICULTURAL DRONES AND REMOTE SENSING MARKET
5.4
VALUE CHAIN ANALYSIS
5.5
ECOSYSTEM ANALYSIS
5.6
PRICING ANALYSIS
5.6.1
AVERAGE SELLING PRICE TREND OF DRONES, BY REGION, 2022–2025
5.6.2
AVERAGE SELLING PRICE OF PRECISION FARMING HARDWARE COMPONENTS, BY KEY PLAYER, 2025
5.7
TRADE ANALYSIS
5.7.1
IMPORT DATA
5.7.2
EXPORT DATA
5.8
KEY CONFERENCES AND EVENTS, 2026–2027
5.9
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
5.10
INVESTMENT AND FUNDING SCENARIO
5.11
CASE STUDY ANALYSIS
5.11.1
SYNGENTA ENHANCES PRECISION AGRICULTURE WITH SATELLITE INSIGHTS FROM PLANET LABS PBC
5.11.2
TELNYX DEPLOYS IOT-BASED SENSORS TO SUPPORT FRUIT SIZE MONITORING AND YIELD MANAGEMENT
5.11.3
FARMONAUT TECHNOLOGIES ENHANCES CALIFORNIA AGRICULTURE WITH DRONE-ENABLED PRECISION FARMING
5.11.4
PRECISION AGRICULTURE ENHANCES COTTON YIELDS IN PARBHANI THROUGH DIGITAL INNOVATION
5.12
IMPACT OF 2025 US TARIFF ON PRECISION FARMING MARKET
5.12.1
INTRODUCTION
5.12.2
KEY TARIFF RATES
5.12.3
PRICE IMPACT ANALYSIS
5.12.4
IMPACT ON COUNTRIES/REGIONS
5.12.4.1
US
5.12.4.2
EUROPE
5.12.4.3
ASIA PACIFIC
5.12.5
IMPACT ON APPLICATIONS
6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, AND INNOVATIONS
AI and IoT revolutionize precision farming, unlocking new market potentials and patent opportunities.
73
6.1
KEY EMERGING TECHNOLOGIES
6.1.1
GLOBAL POSITIONING SYSTEM (GPS)/GLOBAL NAVIGATION SATELLITE SYSTEM (GNSS)
6.1.2
REMOTE SENSING (SATELLITE AND UAV/DRONES)
6.1.3
GEOGRAPHIC INFORMATION SYSTEM (GIS)
6.2
COMPLEMENTARY TECHNOLOGIES
6.2.1
INTERNET OF THINGS (IOT)
6.2.2
ARTIFICIAL INTELLIGENCE (AI) AND MACHINE LEARNING (ML)
6.2.3
TELEMATICS AND WIRELESS COMMUNICATION (E.G., LORA, NB-IOT, 5G)
6.3
ADJACENT TECHNOLOGIES
6.3.1
AUGMENTED REALITY (AR) AND VIRTUAL REALITY (VR)
6.3.2
DIGITAL TWIN AND SIMULATION MODELS
6.4
TECHNOLOGY ROADMAP
6.5
PATENT ANALYSIS
6.6
IMPACT OF AI ON PRECISION FARMING
6.6.1
TOP USE CASES AND MARKET POTENTIAL
6.6.2
BEST PRACTICES IN PRECISION FARMING MARKET
6.6.3
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
6.6.4
CLIENTS’ READINESS TO ADOPT AI IN PRECISION FARMING MARKET
7
REGULATORY LANDSCAPE
Navigate complex global regulations with insights on key agencies and industry-specific ISO standards.
84
7.1
INTRODUCTION
7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
7.1.2
INDUSTRY STANDARDS
7.1.2.1
ISO 18497-1:2024: SAFETY OF PARTIALLY AUTOMATED, SEMI-AUTONOMOUS AND AUTONOMOUS AGRICULTURAL MACHINERY
7.1.2.2
ISO 25119: SAFETY-RELATED PARTS OF CONTROL SYSTEMS FOR AGRICULTURE AND FORESTRY
7.1.2.3
ISO 11783: TRACTORS AND MACHINERY FOR AGRICULTURE AND FORESTRY — SERIAL CONTROL AND COMMUNICATIONS DATA NETWORK
7.1.2.4
ISO 14001: ENVIRONMENTAL MANAGEMENT SYSTEM
8
CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
Understand stakeholder influence and unmet needs to optimize precision farming adoption strategies.
87
8.1
DECISION-MAKING PROCESS
8.2
KEY STAKEHOLDERS IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
8.2.1
KEY STAKEHOLDERS IN BUYING PROCESS
8.2.2
BUYING CRITERIA
8.3
ADOPTION BARRIERS AND INTERNAL CHALLENGES
8.4
UNMET NEEDS OF VARIOUS APPLICATIONS
9
PRECISION FARMING MARKET, BY OFFERING
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million and Units | 48 Data Tables
93
9.1
INTRODUCTION
9.2
HARDWARE
9.2.1
AUTOMATION & CONTROL SYSTEMS
9.2.1.1
DISPLAYS
9.2.1.1.1
RISING USE OF PRECISION FARMING SOLUTIONS IN YIELD MONITORING AND FIELD MAPPING APPLICATIONS TO BOOST DISPLAY DEMAND
9.2.1.2
GUIDANCE & STEERING SYSTEMS
9.2.1.2.1
INCREASING DEPLOYMENT OF GPS-BASED GUIDANCE AND AUTOMATED STEERING SOLUTIONS TO DRIVE MARKET
9.2.1.3
GPS/GNSS DEVICES
9.2.1.3.1
GENUINE NEED FOR BETTER RESOURCE ALLOCATION AND INCREASING YIELD TO ELEVATE DEMAND FOR GPS/GNSS DEVICES
9.2.1.4
DRONES/UAVS
9.2.1.4.1
RISING ADOPTION OF DRONES FOR EARLY DETECTION OF FIELD ANOMALIES, PESTS, AND DISEASES TO DRIVE MARKET
9.2.1.5
IRRIGATION CONTROLLERS
9.2.1.5.1
GROWING FOCUS ON ENHANCING WATER DISTRIBUTION EFFICIENCY FOR OPTIMAL CROP HYDRATION TO PROPEL MARKET
9.2.1.6
HANDHELD MOBILE DEVICES/HANDHELD COMPUTERS
9.2.1.6.1
ABILITY TO PROVIDE REAL-TIME CONNECTIVITY FOR MANAGING AGRICULTURAL DATA AND PROCESSES TO FUEL SEGMENTAL GROWTH
9.2.1.7
FLOW & APPLICATION CONTROL DEVICES
9.2.1.7.1
INCREASING ADOPTION OF CONTROL DEVICES FOR OPTIMIZED INPUT DELIVERY TO FOSTER MARKET EXPANSION
9.2.1.8
OTHER AUTOMATION & CONTROL SYSTEMS
9.2.2
SENSING & MONITORING DEVICES
9.2.2.1
YIELD MONITORS
9.2.2.1.1
POTENTIAL TO OPTIMIZE RESOURCE ALLOCATION AND ENHANCE PROFITABILITY TO ACCELERATE ADOPTION
9.2.2.2
SOIL SENSORS
9.2.2.2.1
MOISTURE SENSORS
9.2.2.2.2
TEMPERATURE SENSORS
9.2.2.2.3
NUTRIENT SENSORS
9.2.2.3
WATER SENSORS
9.2.2.3.1
NEED TO OPTIMIZE IRRIGATION DECISIONS THROUGH REAL-TIME WATER MONITORING TO SPUR DEMAND
9.2.2.4
CLIMATE SENSORS
9.2.2.4.1
NECESSITY FOR EARLY DETECTION OF CLIMATIC ANOMALIES AND OPTIMIZATION OF CROP CONDITIONS TO DRIVE MARKET
9.3
SOFTWARE
9.3.1
LOCAL/WEB-BASED SOFTWARE
9.3.1.1
RISING ADOPTION OF ADVANCED CONNECTIVITY SOLUTIONS IN AREAS WITH LIMITED NETWORK ACCESS TO SUPPORT MARKET GROWTH
9.3.2
CLOUD-BASED SOFTWARE
9.3.2.1
EXPANDING DEPLOYMENT OF CLOUD PLATFORMS FOR SUSTAINABLE AGRICULTURE TO CREATE OPPORTUNITIES
9.4
SERVICES
9.4.1
SYSTEM INTEGRATION & CONSULTING SERVICES
9.4.1.1
NEED TO ALIGN HARDWARE AND SOFTWARE COMPONENTS FOR SUSTAINABLE FARMING PRACTICES TO CONTRIBUTE TO SEGMENTAL GROWTH
9.4.2
MANAGED SERVICES
9.4.2.1
FARM OPERATION SERVICES
9.4.2.2
STRONG FOCUS OF MEDIUM- AND LARGE-SCALE FARMS ON MAXIMIZING EFFICIENCY TO BOOST SEGMENTAL GROWTH
9.4.2.3
DATA SERVICES
9.4.2.4
PROLIFERATION OF MOBILE APPLICATIONS IN PRECISION FARMING TO ACCELERATE DATA SERVICE DEMAND
9.4.2.5
DATA ANALYTICS SERVICES
9.4.2.6
INTEGRATION OF AI, ML, AND BIG DATA ANALYTICS TO EVALUATE HISTORICAL AND REAL-TIME DATA TO PROPEL MARKET
9.4.3
CONNECTIVITY SERVICES
9.4.3.1
NECESSITY FOR SYNCHRONIZED FUNCTIONING OF FARM EQUIPMENT, DRONES, AND IOT DEVICES TO STIMULATE DEMAND
9.4.4
ASSISTED PROFESSIONAL SERVICES
9.4.4.1
SUPPLY CHAIN MANAGEMENT SERVICES
9.4.4.1.1
FOCUS ON ENHANCING TRACEABILITY AND TRANSPARENCY ACROSS SUPPLY CHAIN TO DRIVE DEMAND
9.4.4.2
CLIMATE INFORMATION SERVICES
9.4.4.2.1
NECESSITY TO ENSURE LONG-TERM FARM SUSTAINABILITY TO ACCELERATE SEGMENTAL GROWTH
9.4.4.3
OTHER ASSISTED PROFESSIONAL SERVICES
9.4.5
MAINTENANCE & SUPPORT SERVICES
9.4.5.1
NEED TO MINIMIZE DOWNTIME AND RESOLVE TECHNICAL ISSUES PROMPTLY TO FUEL SEGMENTAL GROWTH
10
PRECISION FARMING MARKET, BY TECHNOLOGY
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 14 Data Tables
122
10.1
INTRODUCTION
10.2
GUIDANCE TECHNOLOGY
10.2.1
GPS/GNSS-BASED GUIDANCE TECHNOLOGY
10.2.1.1
ABILITY TO ENHANCE SITE-SPECIFIC OPERATIONS, INPUT ACCURACY, AND SUSTAINABLE RESOURCE MANAGEMENT TO FACILITATE MARKET GROWTH
10.2.2
GIS-BASED GUIDANCE TECHNOLOGY
10.2.2.1
ADVANCING SPATIAL DATA MANAGEMENT, RESOURCE OPTIMIZATION, AND SITE-SPECIFIC DECISION SUPPORT TO DRIVE MARKET
10.3
REMOTE SENSING TECHNOLOGY
10.3.1
HANDHELD OR GROUND-BASED SENSING
10.3.1.1
NEED FOR COST-EFFECTIVE FIELD MONITORING AND YIELD ASSESSMENT SOLUTIONS TO FUEL DEMAND
10.3.2
SATELLITE OR AERIAL SENSING
10.3.2.1
ADOPTION OF ADVANCED CROP MONITORING AND YIELD TECHNOLOGIES TO DRIVE MARKET
10.4
VARIABLE-RATE TECHNOLOGY
10.4.1
MAP-BASED
10.4.1.1
POTENTIAL TO REDUCE INPUT WASTE THROUGH SITE-SPECIFIC APPLICATION TO BOOST DEPLOYMENT
10.4.2
SENSOR-BASED
10.4.2.1
INCLINATION TOWARD OPTIMIZED INPUT APPLICATION AND SUSTAINABLE CROP MANAGEMENT TO SUPPORT SEGMENTAL GROWTH
11
PRECISION FARMING MARKET, BY APPLICATION
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 27 Data Tables
134
11.1
INTRODUCTION
11.2
YIELD MONITORING
11.2.1
ON-FARM YIELD MONITORING
11.2.1.1
GROWING PREFERENCE FOR SUSTAINABLE AND RESOURCE-EFFICIENT FARMING TO FUEL SEGMENTAL GROWTH
11.2.2
OFF-FARM YIELD MONITORING
11.2.2.1
NEED TO ASSESS YIELD QUALITY POST-HARVEST TO FOSTER MARKET GROWTH
11.3
CROP SCOUTING
11.3.1
USE OF GPS AND UAV TECHNOLOGIES TO ENHANCE CROP HEALTH TO FACILITATE MARKET GROWTH
11.3.2
PRE-SEEDING CROP SCOUTING
11.3.3
POST-SEEDING CROP SCOUTING
11.3.4
CROP MONITORING
11.4
FIELD MAPPING
11.4.1
BOUNDARY MAPPING
11.4.1.1
GREATER EMPHASIS ON IMPROVING SAMPLING ACCURACY AND MONITORING CROP PRODUCTION TO AUGMENT SEGMENTAL GROWTH
11.4.2
DRAINAGE MAPPING
11.4.2.1
REQUIREMENT FOR IMPROVED FIELD CONDITIONS AND SUSTAINABLE CROP PRODUCTION TO PROPEL MARKET
11.5
VARIABLE-RATE APPLICATION
11.5.1
PRECISION IRRIGATION
11.5.1.1
INCREASING FOCUS ON WATER WASTE REDUCTION AND YIELD MAXIMIZATION TO STIMULATE DEMAND
11.5.2
PRECISION SEEDING
11.5.2.1
POTENTIAL TO OFFER HIGHER YIELDS AND MINIMIZED CROP DAMAGE TO DRIVE SEGMENTAL GROWTH
11.5.3
PRECISION FERTILIZATION
11.5.3.1
SIGNIFICANT FOCUS ON SITE-SPECIFIC NUTRIENT MANAGEMENT AND RESOURCE OPTIMIZATION TO DRIVE ADOPTION
11.5.3.2
NITROGEN VRA
11.5.3.3
PHOSPHOROUS VRA
11.5.3.4
LIME VRA
11.5.4
OTHER VARIABLE-RATE APPLICATION TYPES
11.6
WEATHER TRACKING & FORECASTING
11.6.1
NEED FOR ENHANCING FARM EFFICIENCY THROUGH ADVANCED WEATHER MONITORING & FORECASTING TO DRIVE DEMAND
11.7
INVENTORY MANAGEMENT
11.7.1
FOCUS ON OPTIMIZING RESOURCE EFFICIENCY TO DRIVE ADOPTION OF STRATEGIC FARM INVENTORY MANAGEMENT
11.8
FARM LABOR MANAGEMENT
11.8.1
EMPHASIS ON REDUCING LABOR COSTS AND INCREASING CROP YIELD TO DRIVE SEGMENTAL GROWTH
11.9
FINANCIAL MANAGEMENT
11.9.1
INCREASING FOCUS ON IMPROVING PROFITABILITY AND MITIGATING FINANCIAL RISKS TO BOOST ADOPTION
11.10
OTHER APPLICATIONS
12
PRECISION FARMING MARKET, BY REGION
Comprehensive coverage of 8 Regions with country-level deep-dive of 23 Countries | 80 Data Tables.
156
12.1
INTRODUCTION
12.2
NORTH AMERICA
12.2.1
US
12.2.1.1
SIGNIFICANT PRESENCE OF MAJOR MARKET PLAYERS TO FUEL MARKET GROWTH
12.2.2
CANADA
12.2.2.1
DIGITAL INNOVATION AND SUSTAINABLE FARMING PRACTICES TO STRENGTHEN MARKET EXPANSION
12.2.3
MEXICO
12.2.3.1
GROWING ADVANCEMENTS IN DIGITAL TOOLS AND SMART FARMING TECHNOLOGIES TO DRIVE MARKET
12.3
EUROPE
12.3.1
GERMANY
12.3.1.1
DIGITALIZATION AND STRATEGIC INVESTMENTS IN AGRICULTURE SECTOR TO ACCELERATE MARKET GROWTH
12.3.2
UK
12.3.2.1
RISING USE OF AUTOMATION AND ROBOTICS IN PLANTING, CROP MANAGEMENT, AND HARVESTING TO SUPPORT MARKET GROWTH
12.3.3
FRANCE
12.3.3.1
DATA-DRIVEN STARTUPS AND SMART ENVIRONMENTAL INSIGHTS TO FACILITATE MARKET GROWTH
12.3.4
SPAIN
12.3.4.1
ELEVATING USE OF DRONE-BASED FIELD SURVEILLANCE AND SMART IRRIGATION SYSTEMS TO REINFORCE MARKET EXPANSION
12.3.5
ITALY
12.3.5.1
RISING FOCUS ON SUSTAINABLE AND EFFICIENT FARMING TO DRIVE MARKET
12.3.6
POLAND
12.3.6.1
GRADUAL ADOPTION OF SMART FARMING SUPPORTED BY EU FUNDING AND MODERNIZATION EFFORTS TO PROPEL MARKET
12.3.7
NORDICS
12.3.7.1
STRONG DIGITAL INFRASTRUCTURE AND ENVIRONMENTAL GOALS TO CONTRIBUTE TO MARKET GROWTH
12.3.8
REST OF EUROPE
12.4
ASIA PACIFIC
12.4.1
CHINA
12.4.1.1
GOVERNMENT INVESTMENTS IN AI-DRIVEN FARMING AND PESTICIDE MANAGEMENT TO STIMULATE MARKET GROWTH
12.4.2
JAPAN
12.4.2.1
LAUNCH OF ROBOTIC SOLUTIONS AND AGRICULTURAL AUTOMATED SYSTEMS TO FUEL MARKET GROWTH
12.4.3
SOUTH KOREA
12.4.3.1
GOVERNMENT SUPPORT TO DEVELOP SMART FARMING VILLAGES TO CONTRIBUTE TO MARKET GROWTH
12.4.4
INDIA
12.4.4.1
AI-ENABLED AGRICULTURAL ADVISORY AND PRECISION FARMING INFRASTRUCTURE TO ACCELERATE MARKET GROWTH
12.4.5
AUSTRALIA
12.4.5.1
RISING FOCUS ON IMPROVING FERTILIZER EFFICIENCY AND INCREASE CROP YIELDS TO BOOST DEMAND
12.4.6
INDONESIA
12.4.6.1
DIGITAL TRANSFORMATION IN AGRICULTURE TO FACILITATE MARKET GROWTH
12.4.7
MALAYSIA
12.4.7.1
SMART FARMING INITIATIVES FOCUSED ON FIELD EFFICIENCY IMPROVEMENT AND MANUAL LABOR REDUCTION TO FUEL MARKET EXPANSION
12.4.8
THAILAND
12.4.8.1
ESCALATING USE OF DRONES, GPS-GUIDED TRACTORS, SENSOR-BASED IRRIGATION SYSTEMS TO DRIVE MARKET
12.4.9
VIETNAM
12.4.9.1
INTEGRATION OF SATELLITE IMAGERY AND AUTOMATED IRRIGATION SYSTEMS TO REINFORCE MARKET EXPANSION
12.4.10
REST OF ASIA PACIFIC
12.5
ROW
12.5.1
MIDDLE EAST
12.5.1.1
BAHRAIN
12.5.1.1.1
STRONG GOVERNMENT COMMITMENT TO FOOD SECURITY AND DIGITAL TRANSFORMATION TO SPIKE DEMAND
12.5.1.2
KUWAIT
12.5.1.2.1
ADOPTION OF SMART WATER MANAGEMENT AND VERTICAL FARMING TO SUPPORT MARKET
12.5.1.3
OMAN
12.5.1.3.1
IMPLEMENTATION OF SMART AGRICULTURE AND FOOD SECURITY INITIATIVES TO STRENGTHEN MARKET EXPANSION
12.5.1.4
QATAR
12.5.1.4.1
STRATEGIC ADVANCEMENTS AND AGRICULTURAL DIGITIZATION FOR SUSTAINABLE FOOD SECURITY TO DRIVE MARKET
12.5.1.5
SAUDI ARABIA
12.5.1.5.1
INNOVATION AND STRATEGIC INITIATIVES TRANSFORMING AGRICULTURE SECTOR TO SUPPORT MARKET GROWTH
12.5.1.6
UAE
12.5.1.6.1
STRATEGIC ADOPTION OF SUSTAINABLE DESERT FARMING PRACTICES TO STIMULATE MARKET GROWTH
12.5.1.7
REST OF MIDDLE EAST
12.5.2
AFRICA
12.5.2.1
SOUTH AFRICA
12.5.2.1.1
ADVANCEMENTS IN AGRICULTURE THROUGH SATELLITE IOT AND AI-DRIVEN SOLUTIONS TO CONTRIBUTE TO MARKET GROWTH
12.5.2.2
REST OF AFRICA
12.5.3
SOUTH AMERICA
12.5.3.1
ADVANCING DIGITAL CONNECTIVITY AND TECHNOLOGICAL INTEGRATION TO STIMULATE DEMAND
12.5.4
BRAZIL
12.5.4.1
LARGE-SCALE COMMERCIAL AGRICULTURE AND DIGITALISATION DRIVE PRECISION FARMING ADOPTION
12.5.5
ARGENTINA
12.5.5.1
MECHANISED BROAD-ACRE FARMING AND DATA-DRIVEN AGRICULTURE ACCELERATE PRECISION TECHNOLOGY ADOPTION
12.5.6
REST OF SOUTH AMERICA
12.5.6.1
AGRICULTURAL MODERNISATION AND RESOURCE-EFFICIENCY NEEDS SUPPORT EMERGING PRECISION FARMING ADOPTION
13
COMPETITIVE LANDSCAPE
Uncover strategic insights and market positioning of key players and startups through 2026.
208
13.1
OVERVIEW
13.2
KEY PLAYER STRATEGIES/RIGHT TO WIN, 2023–2026
13.3
REVENUE ANALYSIS, 2021–2025
13.4
MARKET SHARE ANALYSIS, 2025
13.5
COMPANY VALUATION AND FINANCIAL METRICS, 2026
13.6
PRODUCT COMPARISON
13.7
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2026
13.7.1
STARS
13.7.2
EMERGING LEADERS
13.7.3
PERVASIVE PLAYERS
13.7.4
PARTICIPANTS
13.7.5
COMPANY FOOTPRINT: KEY PLAYERS, 2026
13.7.5.1
COMPANY FOOTPRINT
13.7.5.2
REGION FOOTPRINT
13.7.5.3
OFFERING FOOTPRINT
13.7.5.4
TECHNOLOGY FOOTPRINT
13.7.5.5
APPLICATION FOOTPRINT
13.8
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2026
13.8.1
PROGRESSIVE COMPANIES
13.8.2
RESPONSIVE COMPANIES
13.8.3
DYNAMIC COMPANIES
13.8.4
STARTING BLOCKS
13.8.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2026
13.8.5.1
DETAILED LIST OF KEY STARTUPS/SMES
13.8.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
13.9
COMPETITIVE SCENARIO
13.9.1
PRODUCT LAUNCHES
13.9.2
DEALS
14
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)
227
14.1
KEY PLAYERS
14.1.1
DEERE & COMPANY
14.1.1.1
BUSINESS OVERVIEW
14.1.1.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
14.1.1.3
RECENT DEVELOPMENTS
14.1.1.3.1
PRODUCT LAUNCHES
14.1.1.3.2
DEALS
14.1.1.3.3
OTHER DEVELOPMENTS
14.1.1.4
MNM VIEW
14.1.1.4.1
KEY STRENGTHS
14.1.1.4.2
STRATEGIC CHOICES
14.1.1.4.3
WEAKNESSES AND COMPETITIVE THREATS
14.1.2
AGCO CORPORATION
14.1.3
CNH INDUSTRIAL N.V.
14.1.4
AG LEADER TECHNOLOGY
14.1.5
AGEAGLE AERIAL SYSTEMS INC.
14.1.6
TOPCON CORPORATION
14.1.7
BAYER AG (CLIMATE LLC)
14.1.8
TEEJET TECHNOLOGIES
14.1.9
HEXAGON AB
14.1.10
KUBOTA CORPORATION
14.2
OTHER PLAYERS
14.2.1
TRIMBLE INC.
14.2.2
ABACO S.P.A.
14.2.3
CROPX INC.
14.2.4
FARMERS EDGE INC.
14.2.5
GROWNETICS
14.2.6
CROPIN TECHNOLOGY SOLUTIONS PRIVATE LIMITED
14.2.7
GAMAYA
14.2.8
DICKEY-JOHN
14.2.9
TELUS
14.2.10
HARXON CORPORATION
14.2.11
AGRICOLUS
14.2.12
ESRI
14.2.13
FARMDOK GMBH
14.2.14
YARA
14.2.15
CLAAS KGAA MBH
15
RESEARCH METHODOLOGY
287
15.1
RESEARCH DATA
15.1.1
SECONDARY DATA
15.1.1.1
KEY DATA FROM SECONDARY SOURCES
15.1.1.2
LIST OF KEY SECONDARY SOURCES
15.1.2
PRIMARY DATA
15.1.2.1
KEY DATA FROM PRIMARY SOURCES
15.1.2.2
LIST OF PRIMARY INTERVIEW PARTICIPANTS
15.1.2.3
BREAKDOWN OF PRIMARIES
15.1.2.4
KEY INDUSTRY INSIGHTS
15.1.3
SECONDARY AND PRIMARY RESEARCH
15.2
MARKET SIZE ESTIMATION METHODOLOGY
15.2.1
BOTTOM-UP APPROACH
15.2.1.1
APPROACH TO ARRIVE AT MARKET SIZE USING BOTTOM-UP ANALYSIS (DEMAND SIDE)
15.2.2
TOP-DOWN APPROACH
15.2.2.1
APPROACH TO ARRIVE AT MARKET SIZE USING TOP-DOWN ANALYSIS (SUPPLY SIDE)
15.3
DATA TRIANGULATION
15.4
RISK ANALYSIS
15.5
RESEARCH ASSUMPTIONS
15.6
RESEARCH LIMITATIONS
16
APPENDIX
299
16.1
DISCUSSION GUIDE
16.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL
16.3
CUSTOMIZATION OPTIONS
16.4
RELATED REPORTS
16.5
AUTHOR DETAILS
LIST OF TABLES
TABLE 1
REPORT INCLUSIONS AND EXCLUSIONS
TABLE 2
STRATEGIC MOVES
TABLE 3
PRECISION FARMING MARKET: IMPACT OF PORTER'S FIVE FORCES
TABLE 4
GDP PERCENTAGE CHANGE, BY COUNTRY, 2021–2030
TABLE 5
ROLE OF PLAYERS IN PRECISION FARMING ECOSYSTEM
TABLE 6
AVERAGE SELLING PRICE TREND OF PRECISION FARMING DRONES, BY REGION, 2022–2025 (USD)
TABLE 7
AVERAGE SELLING PRICE TREND OF PRECISION FARMING HARDWARE COMPONENTS, BY KEY PLAYER, 2021–2025 (USD)
TABLE 8
IMPORT DATA FOR HS CODE 8433-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD THOUSANDS)
TABLE 9
EXPORT DATA FOR HS CODE 8433-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD THOUSANDS)
TABLE 10
PRECISION FARMING MARKET: LIST OF CONFERENCES AND EVENTS
TABLE 11
US-ADJUSTED RECIPROCAL TARIFF RATES
TABLE 12
EVOLUTION OF PRECISION FARMING TECHNOLOGIES
TABLE 13
LIST OF KEY PATENTS IN PRECISION FARMING MARKET, 2024–2025
TABLE 14
TOP USE CASES AND MARKET POTENTIAL
TABLE 15
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
TABLE 16
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 17
EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 18
ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 19
ROW: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 20
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP 3 APPLICATIONS
TABLE 21
KEY BUYING CRITERIA, BY APPLICATION
TABLE 22
UNMET NEEDS IN PRECISION FARMING MARKET, BY APPLICATION
TABLE 23
PRECISION FARMING MARKET, BY OFFERING, 2022–2025 (USD MILLION)
TABLE 24
PRECISION FARMING MARKET, BY OFFERING, 2026–2033 (USD MILLION)
TABLE 25
PRECISION FARMING MARKET, BY HARDWARE, 2022–2025 (USD MILLION)
TABLE 26
PRECISION FARMING MARKET, BY HARDWARE, 2026–2033 (USD MILLION)
TABLE 27
HARDWARE: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 28
HARDWARE: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 29
HARDWARE: PRECISION FARMING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)
TABLE 30
HARDWARE: PRECISION FARMING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)
TABLE 31
AUTOMATION & CONTROL SYSTEMS: PRECISION FARMING MARKET, BY DEVICE TYPE, 2022–2025 (USD MILLION)
TABLE 32
AUTOMATION & CONTROL SYSTEMS: PRECISION FARMING MARKET, BY DEVICE TYPE, 2026–2033 (USD MILLION)
TABLE 33
AUTOMATION & CONTROL SYSTEMS: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 34
AUTOMATION & CONTROL SYSTEMS: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 35
DRONES/UAVS: PRECISION FARMING MARKET, IN TERMS OF VOLUME, 2022–2025 (THOUSAND UNITS)
TABLE 36
DRONES/UAVS: PRECISION FARMING MARKET, IN TERMS OF VOLUME, 2026–2033 (THOUSAND UNITS)
TABLE 37
SENSING & MONITORING DEVICES: PRECISION FARMING MARKET, BY DEVICE TYPE, 2022–2025 (USD MILLION)
TABLE 38
SENSING & MONITORING DEVICES: PRECISION FARMING MARKET, BY DEVICE TYPE, 2026–2033 (USD MILLION)
TABLE 39
SENSING & MONITORING DEVICES: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 40
SENSING & MONITORING DEVICES: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 41
SOIL SENSORS: PRECISION FARMING MARKET, BY SENSOR TYPE, 2022–2025 (USD MILLION)
TABLE 42
SOIL SENSORS: PRECISION FARMING MARKET, BY SENSOR TYPE, 2026–2033 (USD MILLION)
TABLE 43
SOFTWARE: PRECISION FARMING MARKET, BY TYPE, 2022–2025 (USD MILLION)
TABLE 44
SOFTWARE: PRECISION FARMING MARKET, BY TYPE, 2026–2033 (USD MILLION)
TABLE 45
SOFTWARE: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 46
SOFTWARE: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 47
SOFTWARE: PRECISION FARMING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)
TABLE 48
SOFTWARE: PRECISION FARMING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)
TABLE 49
LOCAL/WEB-BASED SOFTWARE: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 50
LOCAL/WEB-BASED SOFTWARE: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 51
CLOUD-BASED SOFTWARE: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 52
CLOUD-BASED SOFTWARE: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 53
SERVICES: PRECISION FARMING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 54
SERVICES: PRECISION FARMING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 55
SERVICES: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 56
SERVICES: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 57
SERVICES: PRECISION FARMING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)
TABLE 58
SERVICES: PRECISION FARMING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)
TABLE 59
SYSTEM INTEGRATION & CONSULTING SERVICES: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 60
SYSTEM INTEGRATION & CONSULTING SERVICES: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 61
MANAGED SERVICES: PRECISION FARMING MARKET, BY TYPE, 2022–2025 (USD MILLION)
TABLE 62
MANAGED SERVICES: PRECISION FARMING MARKET, BY TYPE, 2026–2033 (USD MILLION)
TABLE 63
MANAGED SERVICES: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 64
MANAGED SERVICES: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 65
CONNECTIVITY SERVICES: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 66
CONNECTIVITY SERVICES: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 67
ASSISTED PROFESSIONAL SERVICES: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 68
ASSISTED PROFESSIONAL SERVICES: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 69
MAINTENANCE & SUPPORT SERVICES: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 70
MAINTENANCE & SUPPORT SERVICES: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 71
PRECISION FARMING MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)
TABLE 72
PRECISION FARMING MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)
TABLE 73
GUIDANCE TECHNOLOGY: PRECISION FARMING MARKET, BY OFFERING, 2022–2025 (USD MILLION)
TABLE 74
GUIDANCE TECHNOLOGY: PRECISION FARMING MARKET, BY OFFERING, 2026–2033 (USD MILLION)
TABLE 75
GUIDANCE TECHNOLOGY: PRECISION FARMING MARKET, BY TYPE, 2022–2025 (USD MILLION)
TABLE 76
GUIDANCE TECHNOLOGY: PRECISION FARMING MARKET, BY TYPE, 2026–2033 (USD MILLION)
TABLE 77
REMOTE SENSING TECHNOLOGY: PRECISION FARMING MARKET, BY OFFERING, 2022–2025 (USD MILLION)
TABLE 78
REMOTE SENSING TECHNOLOGY: PRECISION FARMING MARKET, BY OFFERING, 2026–2033 (USD MILLION)
TABLE 79
REMOTE SENSING TECHNOLOGY: PRECISION FARMING MARKET, BY TYPE, 2022–2025 (USD MILLION)
TABLE 80
REMOTE SENSING TECHNOLOGY: PRECISION FARMING MARKET, BY TYPE, 2026–2033 (USD MILLION)
TABLE 81
VARIABLE-RATE TECHNOLOGY: PRECISION FARMING MARKET, BY OFFERING, 2022–2025 (USD MILLION)
TABLE 82
VARIABLE-RATE TECHNOLOGY: PRECISION FARMING MARKET, BY OFFERING, 2026–2033 (USD MILLION)
TABLE 83
VARIABLE-RATE TECHNOLOGY: PRECISION FARMING MARKET, BY TYPE, 2022–2025 (USD MILLION)
TABLE 84
VARIABLE-RATE TECHNOLOGY: PRECISION FARMING MARKET, BY TYPE, 2026–2033 (USD MILLION)
TABLE 85
PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 86
PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 87
BENEFITS OF YIELD MONITORING
TABLE 88
YIELD MONITORING: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 89
YIELD MONITORING: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 90
YIELD MONITORING: PRECISION FARMING MARKET, BY TYPE, 2022–2025 (USD MILLION)
TABLE 91
YIELD MONITORING: PRECISION FARMING MARKET, BY TYPE, 2026–2033 (USD MILLION)
TABLE 92
CROP SCOUTING: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 93
CROP SCOUTING: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 94
FIELD MAPPING: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 95
FIELD MAPPING: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 96
FIELD MAPPING: PRECISION FARMING MARKET, BY TYPE, 2022–2025 (USD MILLION)
TABLE 97
FIELD MAPPING: PRECISION FARMING MARKET, BY TYPE, 2026–2033 (USD MILLION)
TABLE 98
VARIABLE-RATE APPLICATION: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 99
VARIABLE-RATE APPLICATION: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 100
VARIABLE-RATE APPLICATION: PRECISION FARMING MARKET, BY TYPE, 2022–2025 (USD MILLION)
TABLE 101
VARIABLE-RATE APPLICATION: PRECISION FARMING MARKET, BY TYPE, 2026–2033 (USD MILLION)
TABLE 102
WEATHER TRACKING & FORECASTING: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 103
WEATHER TRACKING & FORECASTING: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 104
INVENTORY MANAGEMENT: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 105
INVENTORY MANAGEMENT: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 106
FARM LABOR MANAGEMENT: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 107
FARM LABOR MANAGEMENT: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 108
FINANCIAL MANAGEMENT: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 109
FINANCIAL MANAGEMENT: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 110
OTHER APPLICATIONS: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 111
OTHER APPLICATIONS: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 112
PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 113
PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 114
NORTH AMERICA: PRECISION FARMING MARKET, 2022–2025 (USD MILLION)
TABLE 115
NORTH AMERICA: PRECISION FARMING MARKET, 2026–2033 (USD MILLION)
TABLE 116
NORTH AMERICA: PRECISION FARMING MARKET, BY OFFERING, 2022–2025 (USD MILLION)
TABLE 117
NORTH AMERICA: PRECISION FARMING MARKET, BY OFFERING, 2026–2033 (USD MILLION)
TABLE 118
NORTH AMERICA: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 119
NORTH AMERICA: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 120
US: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 121
US: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 122
CANADA: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 123
CANADA: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 124
MEXICO: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 125
MEXICO: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 126
EUROPE: PRECISION FARMING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)
TABLE 127
EUROPE: PRECISION FARMING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)
TABLE 128
EUROPE: PRECISION FARMING MARKET, BY OFFERING, 2022–2025 (USD MILLION)
TABLE 129
EUROPE: PRECISION FARMING MARKET, BY OFFERING, 2026–2033 (USD MILLION)
TABLE 130
EUROPE: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 131
EUROPE: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 132
GERMANY: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 133
GERMANY: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 134
UK: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 135
UK: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 136
FRANCE: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 137
FRANCE: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 138
SPAIN: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 139
SPAIN: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 140
ITALY: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 141
ITALY: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 142
POLAND: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 143
POLAND: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 144
NORDICS: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 145
NORDICS: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 146
REST OF EUROPE: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 147
REST OF EUROPE: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 148
ASIA PACIFIC: PRECISION FARMING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)
TABLE 149
ASIA PACIFIC: PRECISION FARMING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)
TABLE 150
ASIA PACIFIC: PRECISION FARMING MARKET, BY OFFERING, 2022–2025 (USD MILLION)
TABLE 151
ASIA PACIFIC: PRECISION FARMING MARKET, BY OFFERING, 2026–2033 (USD MILLION)
TABLE 152
ASIA PACIFIC: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 153
ASIA PACIFIC: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 154
CHINA: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 155
CHINA: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 156
JAPAN: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 157
JAPAN: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 158
SOUTH KOREA: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 159
SOUTH KOREA: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 160
INDIA: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 161
INDIA: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 162
AUSTRALIA: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 163
AUSTRALIA: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 164
INDONESIA: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 165
INDONESIA: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 166
MALAYSIA: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 167
MALAYSIA: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 168
THAILAND: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 169
THAILAND: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 170
VIETNAM: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 171
VIETNAM: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 172
REST OF ASIA PACIFIC: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 173
REST OF ASIA PACIFIC: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 174
ROW: PRECISION FARMING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 175
ROW: PRECISION FARMING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 176
ROW: PRECISION FARMING MARKET, BY OFFERING, 2022–2025 (USD MILLION)
TABLE 177
ROW: PRECISION FARMING MARKET, BY OFFERING, 2026–2033 (USD MILLION)
TABLE 178
ROW: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 179
ROW: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 180
MIDDLE EAST: PRECISION FARMING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)
TABLE 181
MIDDLE EAST: PRECISION FARMING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)
TABLE 182
MIDDLE EAST: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 183
MIDDLE EAST: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 184
AFRICA: PRECISION FARMING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)
TABLE 185
AFRICA: PRECISION FARMING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)
TABLE 186
AFRICA: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 187
AFRICA: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 188
SOUTH AMERICA: PRECISION FARMING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)
TABLE 189
SOUTH AMERICA: PRECISION FARMING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)
TABLE 190
SOUTH AMERICA: PRECISION FARMING MARKET, BY APPLICATION, 2022–2025 (USD MILLION)
TABLE 191
SOUTH AMERICA: PRECISION FARMING MARKET, BY APPLICATION, 2026–2033 (USD MILLION)
TABLE 192
PRECISION FARMING MARKET: KEY PLAYER STRATEGIES/RIGHT TO WIN, 2023–2026
TABLE 193
PRECISION FARMING MARKET: DEGREE OF COMPETITION
TABLE 194
PRECISION FARMING MARKET: REGION FOOTPRINT
TABLE 195
PRECISION FARMING MARKET: OFFERING FOOTPRINT
TABLE 196
PRECISION FARMING MARKET: TECHNOLOGY FOOTPRINT
TABLE 197
PRECISION FARMING MARKET: APPLICATION FOOTPRINT
TABLE 198
PRECISION FARMING MARKET: DETAILED LIST OF KEY STARTUPS/SMES
TABLE 199
PRECISION FARMING MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
TABLE 200
PRECISION FARMING MARKET: PRODUCT LAUNCHES, MARCH 2025–SEPTEMBER 2026
TABLE 201
PRECISION FARMING MARKET: DEALS, MARCH 2024–MAY 2025
TABLE 202
DEERE & COMPANY: COMPANY OVERVIEW
TABLE 203
DEERE & COMPANY: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 204
DEERE & COMPANY: PRODUCT LAUNCHES
TABLE 205
DEERE & COMPANY: DEALS
TABLE 206
DEERE & COMPANY: OTHER DEVELOPMENTS
TABLE 207
AGCO CORPORATION: COMPANY OVERVIEW
TABLE 208
AGCO CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 209
AGCO CORPORATION: PRODUCT LAUNCHES
TABLE 210
AGCO CORPORATION: DEALS
TABLE 211
AGCO CORPORATION: EXPANSIONS
TABLE 212
CNH INDUSTRIAL N.V.: COMPANY OVERVIEW
TABLE 213
CNH INDUSTRIAL N.V.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 214
CNH INDUSTRIAL N.V.: PRODUCT LAUNCHES
TABLE 215
CNH INDUSTRIAL N.V.: DEALS
TABLE 216
AG LEADER TECHNOLOGY: COMPANY OVERVIEW
TABLE 217
AG LEADER TECHNOLOGY: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 218
AG LEADER TECHNOLOGY: PRODUCT LAUNCHES
TABLE 219
AGEAGLE AERIAL SYSTEMS INC.: COMPANY OVERVIEW
TABLE 220
AGEAGLE AERIAL SYSTEMS INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 221
AGEAGLE AERIAL SYSTEMS INC.: PRODUCT LAUNCHES
TABLE 222
TOPCON CORPORATION: COMPANY OVERVIEW
TABLE 223
TOPCON CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 224
TOPCON CORPORATION: PRODUCT LAUNCHES
TABLE 225
TOPCON CORPORATION: DEALS
TABLE 226
TOPCON CORPORATION: EXPANSIONS
TABLE 227
BAYER AG (CLIMATE LLC): COMPANY OVERVIEW
TABLE 228
BAYER AG (CLIMATE LLC): PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 229
BAYER AG (CLIMATE LLC): PRODUCT LAUNCHES
TABLE 230
BAYER AG (CLIMATE LLC): DEALS
TABLE 231
TEEJET TECHNOLOGIES: COMPANY OVERVIEW
TABLE 232
TEEJET TECHNOLOGIES: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 233
TEEJET TECHNOLOGIES: PRODUCT LAUNCHES
TABLE 234
TEEJET TECHNOLOGIES: DEALS
TABLE 235
HEXAGON AB: COMPANY OVERVIEW
TABLE 236
HEXAGON AB: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 237
HEXAGON AB: PRODUCT LAUNCHES
TABLE 238
KUBOTA CORPORATION: COMPANY OVERVIEW
TABLE 239
KUBOTA CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 240
KUBOTA CORPORATION: PRODUCT LAUNCHES
TABLE 241
KUBOTA CORPORATION: DEALS
TABLE 242
KUBOTA CORPORATION: OTHER DEVELOPMENTS
TABLE 243
TRIMBLE INC.: COMPANY OVERVIEW
TABLE 244
ABACO S.P.A.: COMPANY OVERVIEW
TABLE 245
CROPX INC.: COMPANY OVERVIEW
TABLE 246
FARMERS EDGE INC.: COMPANY OVERVIEW
TABLE 247
GROWNETICS: COMPANY OVERVIEW
TABLE 248
CROPIN TECHNOLOGY SOLUTIONS PRIVATE LIMITED: COMPANY OVERVIEW
TABLE 249
GAMAYA: COMPANY OVERVIEW
TABLE 250
DICKEY-JOHN: COMPANY OVERVIEW
TABLE 251
TELUS: COMPANY OVERVIEW
TABLE 252
HARXON CORPORATION: COMPANY OVERVIEW
TABLE 253
AGRICOLUS: COMPANY OVERVIEW
TABLE 254
ESRI: COMPANY OVERVIEW
TABLE 255
FARMDOK GMBH: COMPANY OVERVIEW
TABLE 256
YARA: COMPANY OVERVIEW
TABLE 257
CLAAS KGAA MBH: COMPANY OVERVIEW
TABLE 258
PRECISION FARMING MARKET: RISK ANALYSIS
LIST OF FIGURES
FIGURE 1
MARKETS COVERED AND REGIONAL SCOPE
FIGURE 2
DURATION COVERED
FIGURE 3
MARKET SCENARIO
FIGURE 4
PRECISION FARMING MARKET, 2022–2033
FIGURE 5
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN PRECISION FARMING MARKET (JANUARY 2023–MARCH 2026)
FIGURE 6
DISRUPTIVE TRENDS IMPACTING GROWTH OF PRECISION FARMING MARKET
FIGURE 7
HIGH-GROWTH SEGMENTS IN PRECISION FARMING MARKET, 2026-2033
FIGURE 8
ASIA PACIFIC TO BE FASTEST-GROWING MARKET DURING FORECAST PERIOD
FIGURE 9
INCREASING AUTOMATION TREND TO PROVIDE LUCRATIVE OPPORTUNITIES FOR PLAYERS IN PRECISION FARMING MARKET
FIGURE 10
DRONES/UAVS TO ACCOUNT FOR LARGEST SHARE OF PRECISION FARMING MARKET FOR AUTOMATION & CONTROL SYSTEMS IN 2033
FIGURE 11
YIELD MONITORING TO BE LARGEST APPLICATION IN PRECISION FARMING MARKET FROM 2026 TO 2033
FIGURE 12
NORTH AMERICA TO ACCOUNT FOR LARGEST SHARE OF PRECISION FARMING MARKET FROM 2026 TO 2033
FIGURE 13
PRECISION FARMING MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
FIGURE 14
PRECISION FARMING MARKET DRIVERS: IMPACT ANALYSIS
FIGURE 15
PRECISION FARMING MARKET RESTRAINTS: IMPACT ANALYSIS
FIGURE 16
PRECISION FARMING MARKET OPPORTUNITIES: IMPACT ANALYSIS
FIGURE 17
PRECISION FARMING MARKET CHALLENGES: IMPACT ANALYSIS
FIGURE 18
PRECISION FARMING MARKET: PORTER'S FIVE FORCES ANALYSIS
FIGURE 19
PRECISION FARMING MARKET: VALUE CHAIN ANALYSIS
FIGURE 20
KEY PLAYERS IN PRECISION FARMING ECOSYSTEM
FIGURE 21
AVERAGE SELLING PRICE TREND OF PRECISION FARMING DRONES, BY REGION, 2022–2025
FIGURE 22
AVERAGE SELLING PRICE OF PRECISION FARMING HARDWARE COMPONENTS OFFERED BY KEY PLAYER IN 2025
FIGURE 23
IMPORT SCENARIO FOR HS CODE 8433-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025
FIGURE 24
EXPORT SCENARIO FOR HS CODE 8433-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025
FIGURE 25
TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS
FIGURE 26
INVESTMENT AND FUNDING SCENARIO, 2021–2025
FIGURE 27
NUMBER OF PATENTS GRANTED IN PRECISION FARMING MARKET, 2016–2025
FIGURE 28
DECISION-MAKING FACTORS IN PRECISION FARMING MARKET
FIGURE 29
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP 3 APPLICATIONS
FIGURE 30
KEY BUYING CRITERIA FOR TOP 3 APPLICATIONS
FIGURE 31
ADOPTION BARRIERS AND INTERNAL CHALLENGES
FIGURE 32
SOFTWARE SEGMENT TO RECORD HIGHEST CAGR IN PRECISION FARMING MARKET DURING FORECAST PERIOD
FIGURE 33
VARIABLE-RATE TECHNOLOGY TO EXHIBIT HIGHEST CAGR IN PRECISION FARMING MARKET DURING FORECAST PERIOD
FIGURE 34
YIELD MONITORING APPLICATION TO ACCOUNT FOR LARGEST MARKET SHARE FROM 2026 TO 2033
FIGURE 35
ASIA PACIFIC TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
FIGURE 36
NORTH AMERICA: PRECISION FARMING MARKET SNAPSHOT
FIGURE 37
EUROPE: PRECISION FARMING MARKET SNAPSHOT
FIGURE 38
ASIA PACIFIC: PRECISION FARMING MARKET SNAPSHOT
FIGURE 39
SOUTH AMERICA TO ACCOUNT FOR LARGEST MARKET SHARE IN ROW REGION BY 2033
FIGURE 40
PRECISION FARMING MARKET: REVENUE ANALYSIS OF KEY PLAYERS, 2021–2025
FIGURE 41
MARKET SHARE ANALYSIS OF COMPANIES OFFERING PRECISION FARMING SOLUTIONS, 2025
FIGURE 42
COMPANY VALUATION, 2026
FIGURE 43
FINANCIAL METRICS, 2026
FIGURE 44
PRODUCT COMPARISON
FIGURE 45
PRECISION FARMING MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2026
FIGURE 46
PRECISION FARMING MARKET: COMPANY FOOTPRINT
FIGURE 47
PRECISION FARMING MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2026
FIGURE 48
DEERE & COMPANY: COMPANY SNAPSHOT
FIGURE 49
AGCO CORPORATION: COMPANY SNAPSHOT
FIGURE 50
CNH INDUSTRIAL N.V.: COMPANY SNAPSHOT
FIGURE 51
AGEAGLE AERIAL SYSTEMS INC.: COMPANY SNAPSHOT
FIGURE 52
TOPCON CORPORATION: COMPANY SNAPSHOT
FIGURE 53
BAYER AG (CLIMATE LLC): COMPANY SNAPSHOT
FIGURE 54
HEXAGON AB: COMPANY SNAPSHOT
FIGURE 55
KUBOTA CORPORATION: COMPANY SNAPSHOT
FIGURE 56
PRECISION FARMING MARKET: RESEARCH DESIGN
FIGURE 57
PRECISION FARMING MARKET SIZE ESTIMATION METHODOLOGY
FIGURE 58
PRECISION FARMING MARKET: BOTTOM-UP APPROACH
FIGURE 59
PRECISION FARMING MARKET: TOP-DOWN APPROACH
FIGURE 60
PRECISION FARMING MARKET: DATA TRIANGULATION
FIGURE 61
PRECISION FARMING MARKET: RESEARCH ASSUMPTIONS
FIGURE 62
PRECISION FARMING MARKET: RESEARCH LIMITATIONS
Methodology
The research process for this technical, market-oriented, and commercial study of the precision farming market included systematic gathering, recording, and analysis of data about companies operating in the market. It involved the extensive use of secondary sources, directories, and databases (Factiva, Oanda) to identify and collect relevant information. In-depth interviews were conducted with various primary respondents, including experts from core and related industries and preferred manufacturers, to obtain and verify critical qualitative and quantitative information, as well as to assess the growth prospects of the market. Key players in the precision farming market were identified through secondary research, and their market rankings were determined through primary and secondary research. This included studying annual reports of top players and interviewing key industry experts, such as CEOs, directors, and marketing executives.
Secondary Research
In the secondary research process, various secondary sources have been referred to for identifying and collecting information relevant to this study. Secondary sources include annual reports, press releases, and investor presentations of companies; white papers, certified publications, and articles from recognized authors; directories; and databases. Secondary research has been mainly conducted to obtain key information about the supply of the industry; a total pool of key players; segmentation of the market according to industry trends, geographic markets, and key developments from market- and technology-oriented perspectives.
Primary Research
In the primary research process, primary sources from the supply and demand sides have been interviewed to obtain qualitative and quantitative information for this report. Primary sources from the supply side include experts, such as CEOs, vice presidents, marketing directors, technology and innovation directors, subject-matter experts, consultants, and related key executives from major companies and organizations operating in the precision farming market.
After the complete market engineering process (market statistics calculations, market breakdown, market size estimations, market forecasting, and data triangulation), extensive primary research has been conducted to gather information and verify and validate the critical market numbers.
Several primary interviews have been conducted with experts from the demand and supply sides across four major regions—North America, Europe, Asia Pacific, and RoW. Approximately 25% of the primary interviews were conducted with the demand side and 75% with the supply side. This primary data has been collected through questionnaires, emails, and telephonic interviews.
Breakdown of Primary Interviews

Notes: RoW mainly comprises the Middle East, Africa, and South America.
Other designations include product managers, sales managers, and marketing managers.
Three tiers of companies have been defined based on their total revenue as of 2025: tier 3: revenue lesser than USD 500 million; tier 2: revenue between USD 500 million and 1 billion; and tier 1: revenue more than USD 1 billion.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The bottom-up procedure has been employed to arrive at the overall size of the precision farming market.
- Analyzed major precision farming hardware, software, and service providers, studied their portfolios, and understood products/solutions/services based on their features and functions
- Analyzed the segmental revenue and scope revenue of the companies profiled in the study
- Arrived at the global precision farming market size by adding the scope revenue of key manufacturers in the market
- Conducted multiple discussions with key opinion leaders to understand different precision farming offerings (hardware, software, and service), technology, applications, and current trends in the market, and analyzed the breakup of the scope of study by major precision farming hardware, software, and service providers
The top-down approach has been used to estimate and validate the total size of the precision farming market.
- The global size of the precision farming market was estimated through the data analysis of major companies offering precision farming products/solutions/services.
- The geographic penetration splits were estimated using secondary sources, based on several factors, such as the number of players in a specific region (North America, Europe, Asia Pacific, and RoW).
- The country-level penetration split was analyzed for each region to estimate the market size.
- The market size for the global offering (hardware, software, and service) was determined by understanding the penetration split of each offering in each region.
- The market size for the global application segments was estimated by analyzing the penetration split of each offering for each application.
- The market size for the global technology segments was estimated by analyzing the penetration split of each offering for each technology.
Precision Farming Market: Top-Down and Bottom-Up Approach

Data Triangulation
After arriving at the overall market size using the market size estimation processes as explained above, the market has been split into several segments and subsegments. To complete the entire market engineering process and arrive at the exact statistics of each market segment and subsegment, data triangulation and market breakdown procedures have been employed, wherever applicable. The data has been triangulated by studying various factors and trends from the demand and supply sides in the precision farming market.
Market Definition
Precision farming, also referred to as precision agriculture, is a modern farm management approach that utilizes advanced technologies to monitor and enhance agricultural operations. It focuses on aligning field inputs with specific crop requirements. Technologies such as satellite positioning systems, including global positioning system (GPS), remote sensing, and variable rate technology (VRT), are used to manage crops efficiently and optimize the use of resources such as fertilizers, pesticides, and water.
Key Stakeholders
- Precision farming component providers
- Precision farming integrators and installers
- Precision farming solution providers
- Product manufacturers
- Precision farming-related associations, organizations, forums, and alliances
- Government and corporate bodies
- Research institutes and organizations
- Venture capitalists, private equity firms, and startups
- Distributors and traders
- OEMs
- End users
- Market research and consulting firms
- Agri-food buyers
- Agriculture technology providers
Report Objectives
- To define, describe, and forecast the size of the precision farming market by offering, technology, application, and region, in terms of value
- To describe and forecast the size of the precision farming market by offering, in terms of volume
- To forecast the market for various segments with respect to the main regions, namely, North America, Europe, Asia Pacific, and the Rest of the World (RoW), in terms of value
- To provide macroeconomic outlooks with respect to the main regions, namely, North America, Europe, Asia Pacific, and Rest of the World (RoW)
- To provide detailed information regarding the drivers, restraints, opportunities, and challenges influencing the market’s growth
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the total market
- To provide ecosystem analysis, value chain, trends/disruptions impacting customer business, technology analysis, pricing analysis, technology analysis, key stakeholders and buying criteria, case study analysis, trade analysis, patent analysis, Porter’s five forces, key conferences & events, AI impact, impact of 2025 US tariff, and regulations related to the precision farming market
- To analyze the opportunities in the market for stakeholders by identifying high-growth segments and detailing the competitive landscape for market players
- To strategically profile key players and comprehensively analyze their market rankings, core competencies, company valuation, and financial metrics, and product/brand comparison, along with detailing the competitive landscape for the market leaders
- To analyze the competitive developments, such as product launches, software launches, agreements, collaborations, joint ventures, and acquisitions, carried out by market players
- To map the competitive intelligence based on company profiles, key player strategies, and game-changing developments, such as product developments, collaborations, and acquisitions
- To benchmark players within the market using the competitive leadership mapping framework, which analyzes market players on various parameters within the broad categories of business strategy excellence and strength of product portfolio.
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to the company‘s specific needs. The following customization options are available for the report.
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Key Questions Addressed by the Report
What is the current size of the global Precision Farming Market?
The global Precision Farming Market was valued at USD 11.40 billion in 2025 and is projected to grow from USD 11.97 billion in 2026 to USD 23.07 billion by 2033.
What is the expected CAGR of the Precision Farming Market?
The market is expected to register a CAGR of 9.8% from 2026 to 2033, driven by the adoption of data-driven agriculture technologies and smart farming practices.
What are the major growth drivers of the Precision Farming Market?
Key growth drivers include increasing adoption of IoT, AI, machine learning, GPS/GNSS technologies, growing demand for sustainable agriculture, government support for digital farming, and the need to improve crop yields while optimizing resource usage.
Which offering segment holds the largest share of the Precision Farming Market?
The hardware segment holds the largest market share due to widespread deployment of sensors, drones, GPS devices, automated machinery, and monitoring systems that enable precision agriculture operations.
Which technology segment dominates the Precision Farming Market?
Guidance Technology dominates the market as GPS- and GNSS-based systems help farmers achieve precise field navigation, reduce overlaps, minimize input waste, and improve operational efficiency.
Which application segment accounts for the largest market share?
Yield Monitoring is the leading application segment because it provides real-time crop performance insights, enabling farmers to optimize inputs, improve productivity, and maximize profitability.
Which region leads the global Precision Farming Market?
North America holds the largest market share, accounting for more than 43% of global revenue in 2024, supported by advanced agricultural infrastructure, high technology adoption, and favorable government initiatives.
Which region is expected to grow the fastest in the Precision Farming Market?
Asia Pacific is projected to be the fastest-growing region during the forecast period due to increasing agricultural modernization, government initiatives, rising food demand, and rapid adoption of smart farming technologies in countries such as China and India.
Who are the leading companies in the Precision Farming Market?
Major companies include Deere & Company, AGCO Corporation, CNH Industrial N.V., Topcon Corporation, and Ag Leader Technology.
What does a Precision Farming Market report analyze?
A comprehensive market report analyzes market size, forecasts, growth drivers, technology trends, competitive landscape, regional opportunities, application segments, regulatory developments, adoption patterns, and strategic initiatives of leading market players.
Fact checked
Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Precision Farming Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS

Tetsuya Ohhira
Business Development Manager-Technology Business
Nikon Corporation,
Leading Japanese MNC specializing in optics and imaging productswww.nikon.com
MarketsandMarkets™ response
is quick. Their attitude is flexible and positive. Analyst Insights are globally considered and
significant. Client Services quickly respond to our inquiry and demand. Their wide range of global
surveys help us make our strategic plan.
We hope Knowledge Store will be easier to search
for a report.
VP - Marketing & Business Development
Leading Provider of Process Control Solutions
We engaged with MarketsandMarkets on a study to perform an analysis and recommend a Go-To-Market strategy for metrology and process control in the semiconductor market. The study was tailored to our targets and needs with well-defined milestones. Our overall experience with the MarketsandMarkets team was very good throughout the project in all aspects including the analysis methodologies used, the quality and depth of primary and secondary data sets, the professionalism and flexibility of the team and the ability to meet the target schedule and milestones. We want to thank MarketsandMarkets team for a job well done.
- India Precision Farming Market
- Australia Precision Farming Market
- Indonesia Precision Farming Market
- Malaysia Precision Farming Market
- Thailand Precision Farming Market
- Vietnam Precision Farming Market
- US Precision Farming Market
- Canada Precision Farming Market
- Mexico Precision Farming Market
- Germany Precision Farming Market
- UK Precision Farming Market
- France Precision Farming Market
- Spain Precision Farming Market
- Italy Precision Farming Market
- Poland Precision Farming Market
- China Precision Farming Market
- Japan Precision Farming Market
- South Korea Precision Farming Market
Growth opportunities and latent adjacency in Precision Farming Market



Bernard
Apr, 2026
How are technologies like Internet of Things, Artificial Intelligence, and GPS transforming modern agriculture?.
Joshua
Apr, 2026
Which precision farming technologies (GPS, GIS, drones, sensors) are most widely used and why?.
Ben
Apr, 2026
What are the main applications of precision farming in crop monitoring, yield tracking, and field mapping?.
User
Sep, 2019
Penetration of IoT and AI technologies in agriculture is increasing at rapid pace. Every year we are witnessing a large number of startups enetering this space. Does your report covers startups data and strategies adopted by them ?.
User
Feb, 2025
I would like to know the number of setups sold for both crop and livestock related precision Ag..
User
Sep, 2019
Automated Guidance steering, GPS, and remore sensing are playing critical role in automation of farm machinery and increasing productivity of farms. Does your report cover agricultural machinery automation data and their adoption trend?.
User
Apr, 2021
What is the future of Precision Farming in terms of Technology? What are the companies working on?.
User
Sep, 2019
I would require some market analysis, data and figures about the current and forecasted oeriod for precision agriculture market.
harshdeep
Dec, 2020
I need the detail of how many farmers have adopted precision farming and the results of the precision farming market when it comes out..
User
Nov, 2019
Have you included eastern European countries in your analysis. My focus is on major players in Estern Europe and Africa. What data you can provide? .
User
Mar, 2019
I would like to know the number of devices sold for both crop and livestock related precision Ag hardware, not just the dollar value of the market size..